Deriving the formula from scratch
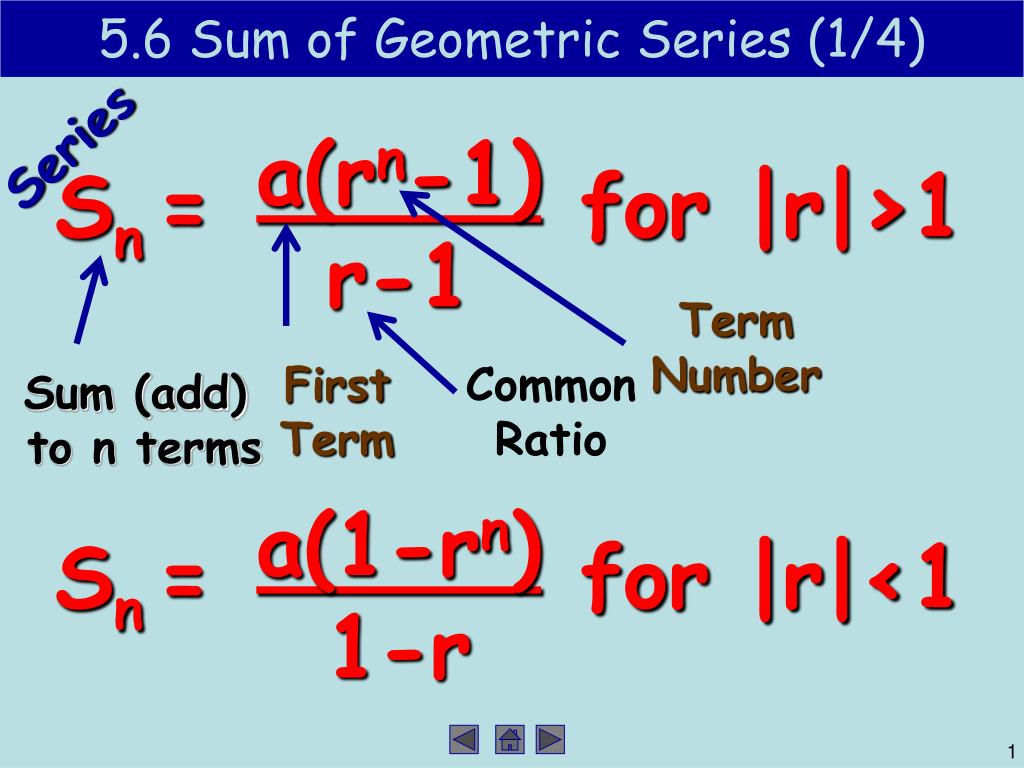
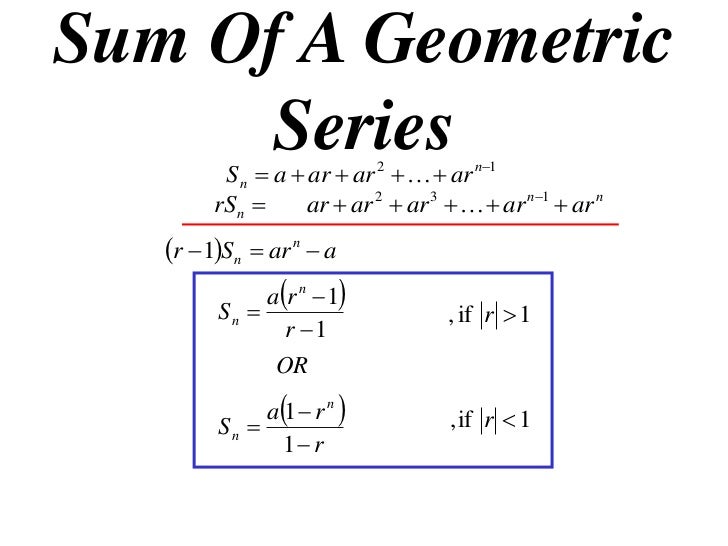
Start with S = a + ar + ar² + ... + ar¹. Multiply both sides by r and get rS = ar + ar² + ar³ + ... + ar. Subtract the second equation from the first and most terms cancel, leaving S(1 - r) = a(1 - r). That gives you S = a(1 - r)/(1 - r), which is the finite Sum Of A Geometric Series formula. The version you probably see in textbooks rearranges to S = a(r - 1)/(r - 1). They are identical. I used to mix them up in exams and lost points twice before I just picked one and stopped second-guessing myself.
Sum Of A Geometric Series in practice
The formula assumes you know four of the five variables: a, r, n, S, and sometimes the last term. In real problems you are usually handed three and asked to find the rest. If n is small, say under ten, you can verify your answer by just adding the terms out. If n is larger, the formula is what saves you from doing arithmetic by hand. I worked on a cash flow model once where the payment amounts grew by exactly 4.2 percent each period and there were 180 periods. The client wanted the total undiscounted sum. Plugging into the formula gave me the answer in about two minutes. Adding each line individually would have taken roughly forty-five minutes in a spreadsheet and still left room for a formula error somewhere in the middle.
When the formula breaks
There are a few cases where the standard approach fails outright and you need a different move. Case one: r equals 1. The denominator becomes zero and the formula is meaningless. When every term is the same value a, the sum is simply S = na. I learned this the hard way during a review where my check sheet had r listed as 1.000 to three decimal places but my calculator had stored it as a rounded float. The result was wildly off. I switched to a conditional check in the spreadsheet that forces S = na whenever |r - 1| is below a small threshold, which prevents the division-by-zero problem entirely. Case two: r is negative. The formula still works, but the signs oscillate. People sometimes forget that and get confused when their terms alternate and the sum ends up smaller than the first term. There is nothing wrong with that. It is just how alternating series behave.
Get the Full Details

Case three: r has absolute value greater than 1 and n is very large. r can overflow standard floating point. In financial work with compounding growth over dozens of periods, I have seen Excel return #NUM! on the r term alone. The workaround is to compute using logarithms or to rewrite the calculation in a form that avoids the extreme power directly. For example, you can express r as exp(n * ln(r)) and let the math library handle the exponentiation internally, which stays stable over a wider range.
The infinite case
When |r| is less than 1 and n approaches infinity, the term r drops toward zero. The formula simplifies to S = a/(1 - r). This is not a separate rule. It is the same formula with one term removed because that term vanishes. Beginners often try to apply this to any series without checking the convergence condition. If |r| is 1 or larger, the infinite sum does not exist in the ordinary sense, and using a/(1 - r) will give you a number that has no relationship to the actual partial sums. I once saw an intern use the infinite formula on a sequence with r = 1.05 and then wonder why the answer looked absurdly small compared to the spreadsheet output. A two-second check on |r| would have caught it.
Common pitfalls
The indexing is where most mistakes happen. The exponent on the last term is n - 1, not n. If your series starts at a and goes for n terms, the final term is ar¹. Confusing these off-by-one errors shifts your answer every time and the error does not cancel out. I count the terms on my fingers now. It sounds childish, but it has saved me more than once. Another frequent error is swapping a and the first term. The variable a is the first term itself. If your problem states the series starts at some other value, you need to adjust a to match. Using the wrong starting value is the fastest way to get a result that looks plausible but is completely wrong. Cash flow problems also trip people up because they mix up the geometric series with the present value formula for an annuity. The geometric sum gives you the raw total. Discounting changes the structure entirely and requires a different treatment. Do not substitute one for the other just because both involve r and n.
A note on precision
When r is close to 1 and n is large, the subtraction 1 - r loses precision in floating point arithmetic. This is a real issue, not a theoretical one. The workaround is to use the alternative form S = a * r^(n-1) * (r - 1)/(r - 1) rearranged carefully, or better yet, to use arbitrary-precision libraries if you are coding this into software. For hand calculations and normal spreadsheet work, the standard formula is fine until you hit those edge conditions. If you need a quick reference sheet or a calculator that handles the r equals 1 and overflow cases automatically, I recommend building one yourself rather than hunting for a third-party tool. Most online calculators do not warn you when r is exactly 1, and they will happily return a #DIV/0! error instead of the correct na result. A simple conditional statement in any spreadsheet does the job in under ten minutes.


