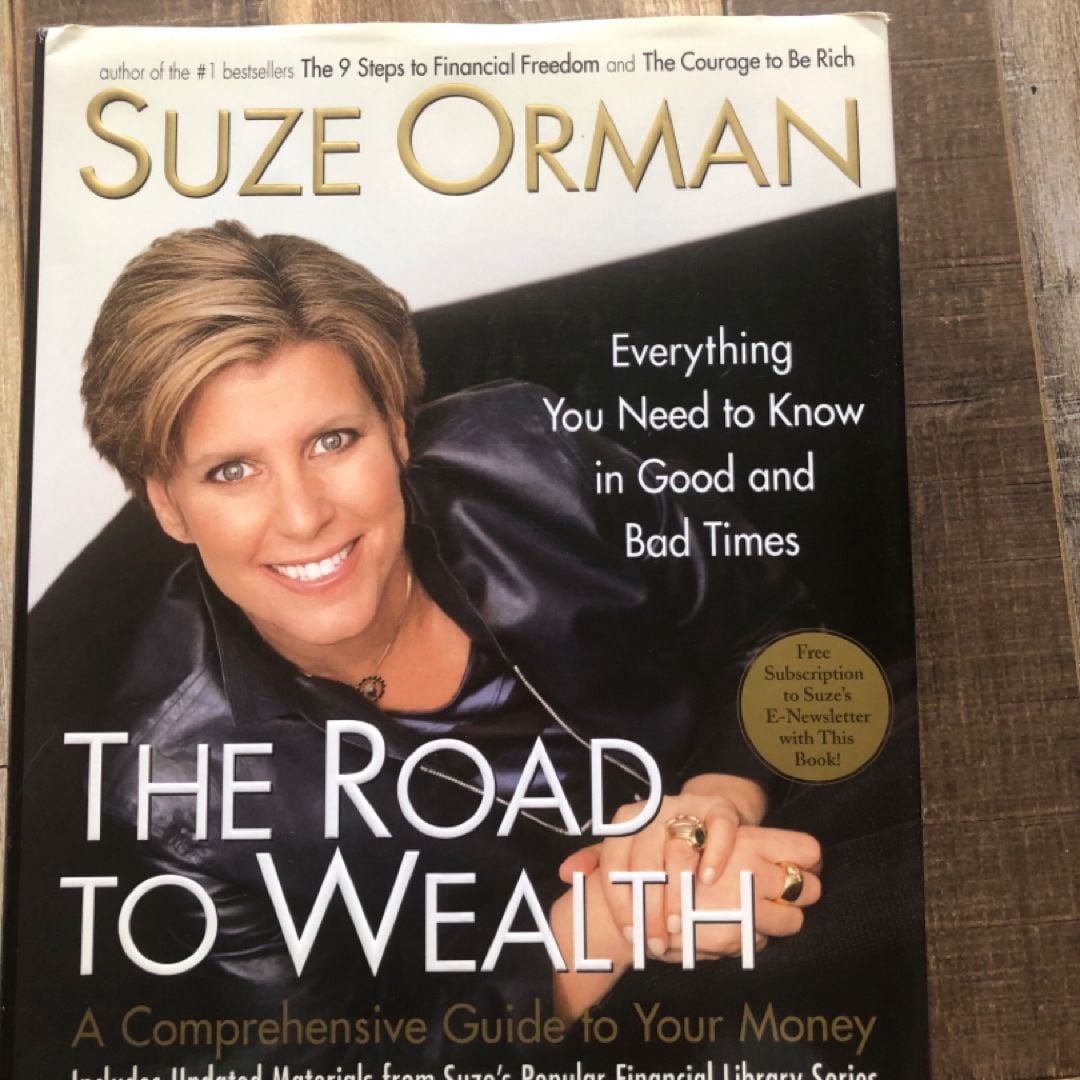
Getting Started With Suze Orman The Road To Wealth
The program is fundamentally a structured path for people who feel like they are always one emergency away from financial collapse. It covers budgeting, debt payoff strategy, and investing in plain language. Most financial guidance wraps concepts in jargon to sound authoritative. Suze just says what she means, which is why it resonates with a certain demographic, but that blunt tone also means it does not always account for niche situations. The core curriculum revolves around her well-known "money steps." You start with an emergency fund, then work through debt elimination, retirement savings, protecting the people you care about, and finally building lasting wealth. The sequence matters more than skipping ahead. I have seen people try to jump straight to investing because they are impatient, and they end up one missed paycheck from disaster. One thing most guides skip over: the emotional reframing piece. Suze spends a lot of time on shame and anxiety around money. That sounds fluffy until you realize how many clients stall at step one simply because they are embarrassed about their numbers. Once the shame drops, the rest usually moves faster.
How The Process Actually Works In Practice
You begin with a full financial audit. Every account, every debt, every monthly obligation. Put it all on paper or in a spreadsheet before you make any changes. I once worked with someone who had consolidated debt across three cards into one payment, but the program forced them to see the real interest rate after fees. It looked nothing like the promotional 0% they thought they were getting. That single realization changed their entire payoff order. Next, you build the emergency fund. Not the generic "three to six months" advice, but a proper cash cushion that lives in a high-yield account and stays untouched unless something actually breaks. Then you attack debt using either the avalanche or snowball method, though Suze leans toward psychological wins with the snowball approach. After that, retirement savings get prioritized, especially catching up if you are over fifty.
A Specific Problem And How I Got Around It
One edge case that comes up constantly involves self-employed income. The program assumes steady payroll deductions and predictable cash flow. When someone invoices irregularly, their budget looks completely wrong at the start of the quarter and then suddenly healthy two months later. The standard template breaks here. The workaround is to base your emergency fund and monthly obligations on your lowest earning quarter, not your average. I use a rolling twelve-month average and then apply the bottom twenty-fifth percentile as the real baseline. It feels conservative, but it keeps the whole structure from wobbling every time a client gets a slow month.
Get the Full Details
Common Pitfalls Beginners Miss
The first mistake is treating the roadmap as linear. Life is not. You will face setbacks. A medical bill or a job change will interrupt the sequence. The program accounts for this, but most people do not realize they are supposed to pause rather than restart completely. The second mistake is underestimating insurance needs. Step four covers protection, and people skim it. They have mortgage, term life, and maybe disability. If you are a contractor or work in a high-liability field, the default recommendations fall short fast. Get a proper review before moving forward.
Limitations You Should Know About
The approach is not optimized for high earners making seven figures. The strategies assume middle-income stabilization first. If you are already generating significant surplus cash flow, you will find yourself reinventing parts of the system anyway. In that case, a fiduciary advisor who understands tax optimization and estate structuring will move you faster than following the template line by line. Another limitation is the one-size-fits-all tone on certain investments. Suze is famously cautious about individual stocks and favors broad diversified funds. That works for most people, but it does not leave room for those who want to layer in other asset classes once their foundation is solid.
Where To Find The Full Program
You can find the complete Suze Orman The Road To Wealth materials through her official website and major book retailers. The core content is available as both a book and a digital program depending on which version you choose. There is no secret portal or paid community required to access the fundamental steps. Everything is out in the open. The real value comes from doing the work, not just reading about it. Print out the worksheets, update your accounts, and follow the sequence even when it feels slow. The people who get results are the ones who stick with it past the point where the novelty wears off.