How To Actually Use A Table Of Time Value Of Money
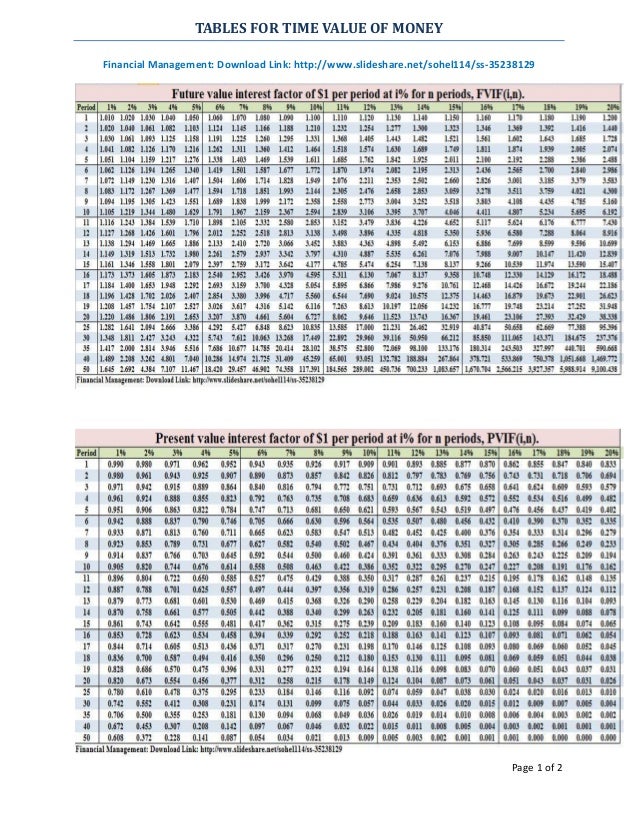
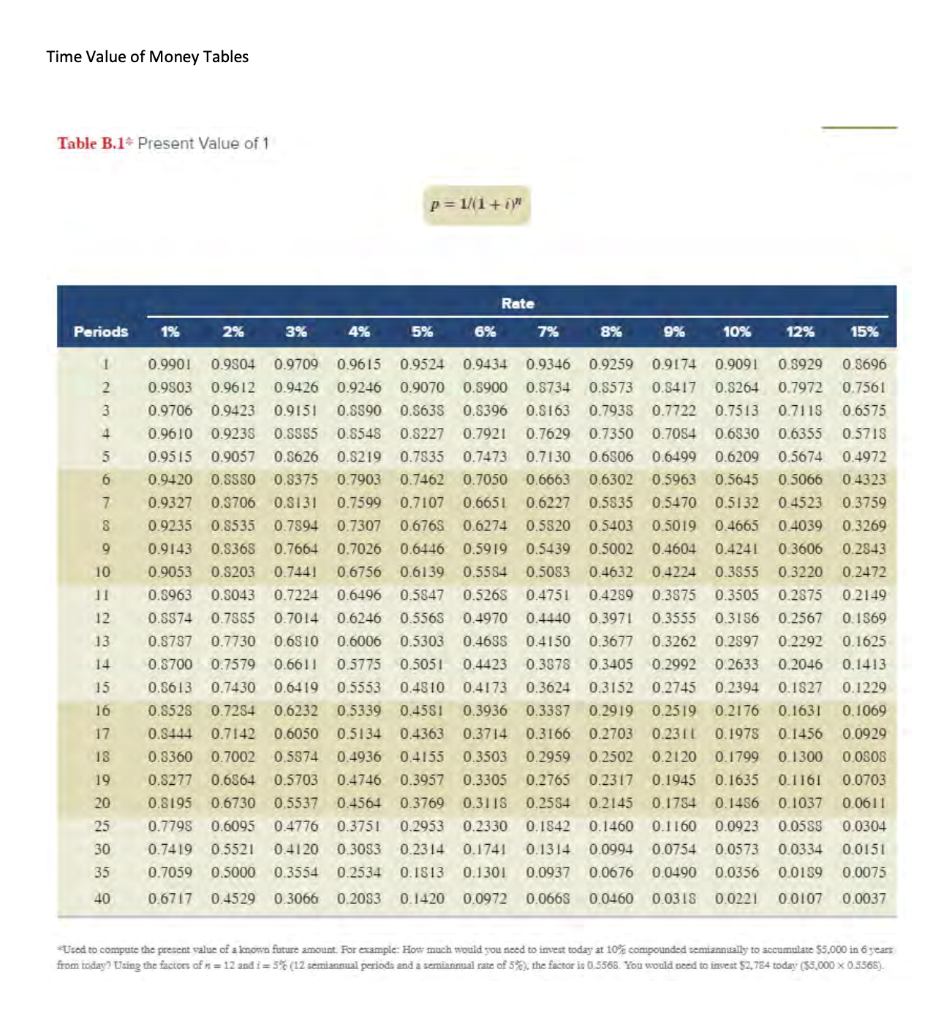
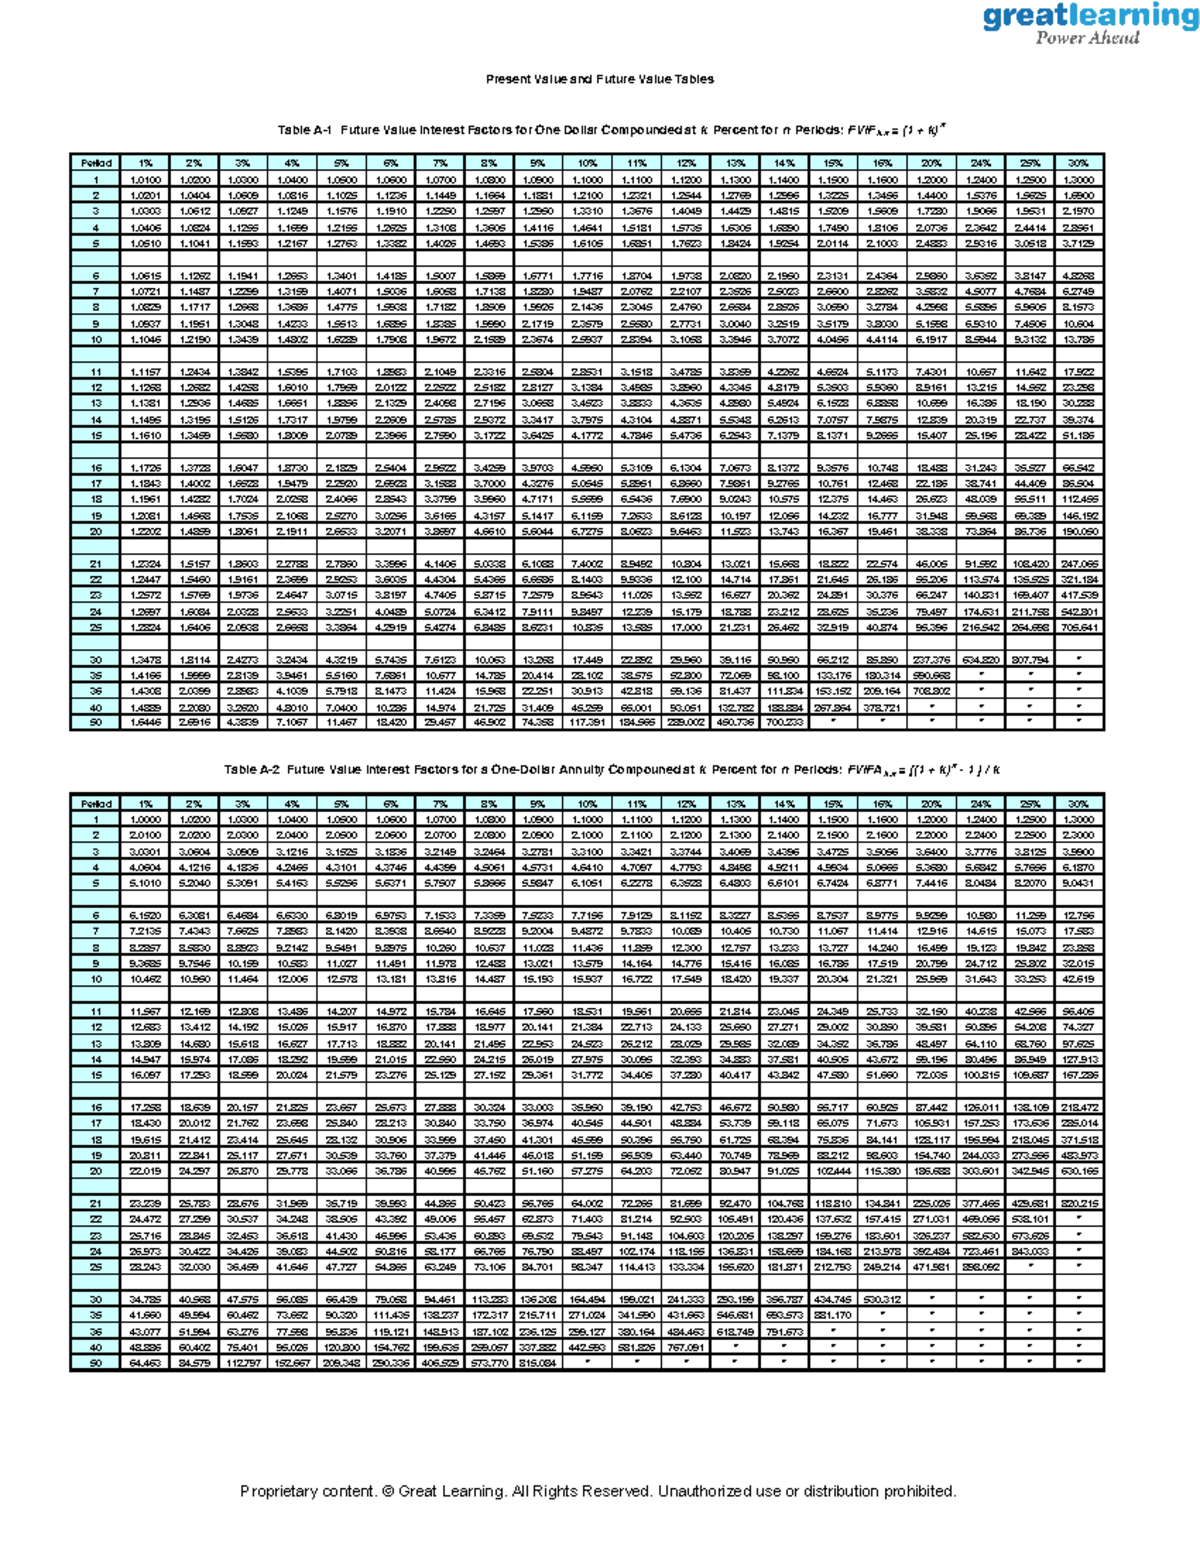
You grab a table when you need a quick PV or FV factor without firing up a financial calculator. That is the practical use case. The tables give you precomputed factors for various combinations of interest rate and periods, so you can multiply and move on. I have been doing this work for a long time, and I still reach for the tables more often than people expect. Here is how it works in practice. Take the Future Value of $1 table. Look up your rate across the top and your periods down the side. The intersection gives you the factor. Multiply that factor by your principal amount and you have your future value. Simple. Now do the same with Present Value of $1 if you need the reverse calculation. The Present Value of an Annuity table handles equal periodic cash flows. The Future Value of an Annuity table handles growth of those same periodic payments.
Most comprehensive tables include all four: PV of $1, FV of $1, PV of Annuity, and FV of Annuity. Sometimes they are separate pages. Sometimes they are in one booklet. It depends on the publisher. Sprenkle and Kline is a common source. Gordon and Pearson runs a bit thicker. Both cover rates from 1% to 20% and periods from 1 to 50 usually. Here is where people get tripped up. The tables assume end-of-period cash flows unless stated otherwise. If you need beginning-of-period calculations, like an annuity due, you adjust the result by multiplying by one plus the rate. That single step catches students and professionals off guard regularly. I ran into a specific problem last year on a lease valuation project. The lease payments came monthly but the table only had annual factors at 8%. I could not just divide the annual rate by twelve because that gives a nominal rate, not an effective one. The workaround was to convert the annual 8% to a monthly equivalent rate first. I calculated (1.08)^(1/12) minus one, which gave me approximately 0.643% per month. Then I looked up the monthly factor in the PV of annuity table using 120 periods and that converted rate. It saved me from building a spreadsheet model for something that should have taken five minutes.
Another thing worth knowing. Tables become unreliable past 30 periods at higher rates because the factors stop showing enough decimal places. Most tables give four to five decimal places. At 12% over 40 periods, you are working with numbers like 16.0033 and losing precision fast. The error compounds. For anything beyond 20 periods or above 10%, I switch to a formula or a calculator. The table method introduces rounding errors that add up. You can download blank template tables or find scanned copies online. Search for "present value tables pdf" or "time value of money factor tables." Many university finance departments post them. The AAA Publishing version is widely available. Some sites offer laminated reference cards you can keep at your desk. I keep a printed copy folded in my filing cabinet even though I use Excel most days. There is something about flipping to a page that forces you to slow down and think about what the numbers actually mean. The biggest limitation of tables is accessibility. They are static. You cannot search them. You cannot adjust for unusual compounding frequencies without extra math. A table with semiannual compounding requires you to double the periods and halve the rate, then hope you remember the rule correctly. If your cash flows are irregular, tables are useless. You need a spreadsheet or a financial calculator for uneven payment streams.
Get the Full Details
Also, tables do not handle negative interest rates, which exist in some markets now. If you are working in Europe or Japan, the tables you find online will not serve you. They were designed for positive rates decades ago. I learned that the hard way on a cross-border acquisition where the discount rate was negative 0.5%. Had to fall back to the direct formula: one divided by one plus rate, all raised to the power of periods. Tables would have given me nothing useful there. What tables do well is teaching. When you sit down with a printed table and trace the intersection yourself, you internalize the relationship between rate, time, and value faster than you ever will from a formula alone. The visual progression of factors down a column shows you how discounting accelerates. Each row gets smaller faster as the rate increases. That pattern recognition is worth the manual lookup effort when you are learning. For professionals, the tables are reference tools, not primary instruments. I use them to sanity-check calculator output or to explain concepts to junior analysts who are not comfortable with formulas yet. The act of looking up a factor forces you to state your assumptions out loud. What is the rate. How many periods. What type of cash flow. Those three questions matter more than the factor itself.
If you want a single source to buy, Amazon carries the Sprenkle and Kline tables in both hardcover and loose-leaf. Expect to pay around fifteen to twenty-five dollars. University bookstores often stock them during finance course registration seasons. Online alternatives include the CFA Institute materials and various finance homework help sites that host PDF versions. Just verify the decimal places before trusting a downloaded copy. Some scanned versions have smudged numbers that change a factor from 3.9927 to 3.9297 depending on how the scan came out. That kind of OCR error has cost me on take-home exercises before. The tables themselves are organized with rates as column headers running left to right and periods as row labels running top to bottom. The PV of $1 table starts near one and declines toward zero as periods increase. The FV of $1 table starts at one and grows without bound. The annuity tables sit between those two behaviors because they accumulate multiple single-period factors. Understanding that structural relationship helps you catch mistakes quickly. If your PV annuity factor is larger than your FV annuity factor at the same rate and period, something is wrong. I also keep a small card with the basic formulas written on it. The table lookup is fast, but occasionally you need the formula directly. The present value formula is one divided by one plus rate, all to the power of negative n. The annuity formula adds the geometric series component. Having both the table and the formula on hand covers the gaps where neither tool alone is sufficient.
One last thing nobody mentions. Tables assume a constant rate throughout the entire period. Real world cash flows rarely face a single fixed discount rate. Term structure changes. Inflation varies. Project risk shifts over time. If your cash flows span multiple years with different risk profiles, a single table lookup gives you a rough estimate at best. I use the table for initial screening and back-of-envelope checks, then move to a discounted cash flow model with varying rates for anything that actually moves money. The Table Of Time Value Of Money is a practical tool. It is not elegant. It is not always precise. But it is fast, it is visual, and it keeps you honest about your assumptions. Use it where it works. Know when to stop using it. That distinction is what separates people who can do the math from people who understand what the math means.