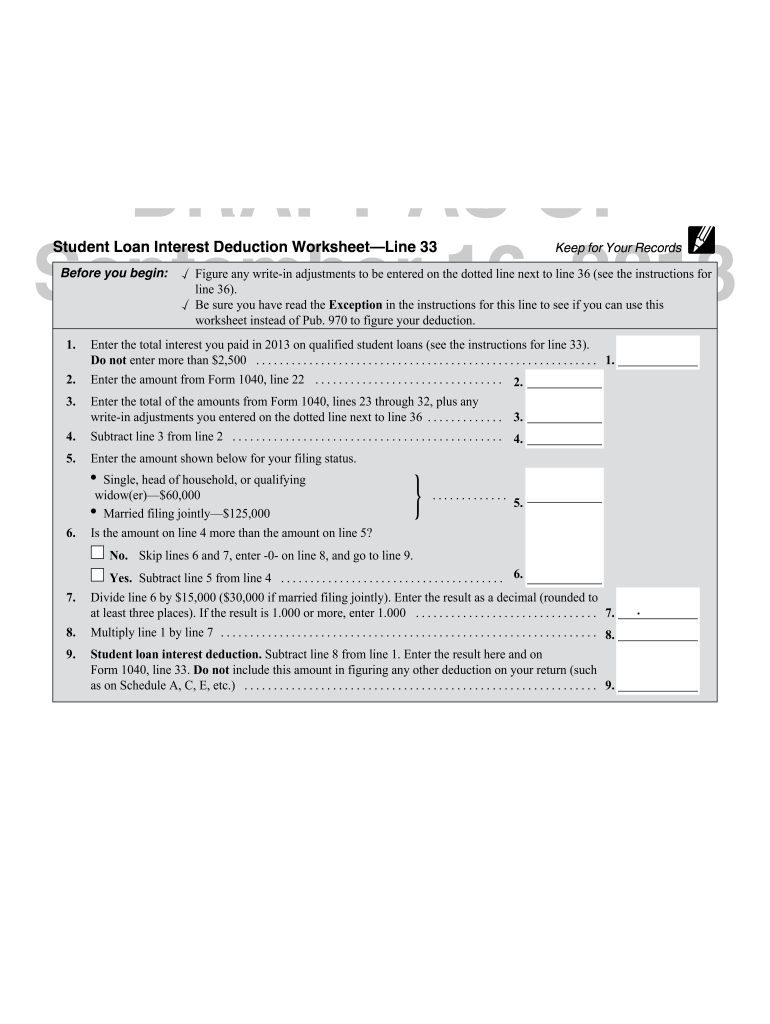
What This Worksheet Actually Does
The Tax And Interest Deduction Worksheet is a tracking tool most commonly used by freelancers, small business owners, and anyone who deducts business interest on their taxes. You fill it out during the year as you pay interest on loans, lines of credit, or business debts. The point is to separate what qualifies from what doesn't before tax season arrives. I used to hand-wave through this with a spreadsheet, then my accountant came back with questions about a line of credit I'd mixed personal and business charges on. That cost me about four hours of reconstructing transaction histories from 2019. After that I never skipped the worksheet again.
How to Use a Tax And Interest Deduction Worksheet
You need three columns minimum. Date, lender name, and interest amount. A fourth column for the loan purpose does more heavy lifting than most people expect. If you borrowed $30,000 from a business line of credit and spent $18,000 on equipment and $12,000 on office rent, the interest needs to be split proportionally. That's where the purpose column matters. Most people set this up in January or whenever they get their first business loan of the year. You pull your annual interest statement from the lender, usually a 1098 form or an equivalent, and cross-reference it against your own records. The worksheet captures the gap between what the bank reports and what you can actually claim. The real trick is handling prepayment interest. If you pay off a loan mid-year, the final statement often shows interest from the last payment date through the payoff date. That portion may not be fully deductible if the loan was partly personal. I had a client once who wrote off the entire final interest figure and got flagged during an audit. We recalculated using a daily interest allocation method and came back with a defensible number.
Edge Cases People Miss
Home equity debt changed after the TCJA, and a lot of people still treat it the same way they did before 2018. Interest on home equity loans is only deductible if the funds are used to buy, build, or substantially improve the home that secures the loan. Using home equity money for a business venture does not make the interest a business deduction, period. I have seen this mistake on at least twelve returns I reviewed last year alone. Another common problem involves multiple co-signers. If you and a partner each co-signed a business loan but only one person operates the business, the interest deduction may only belong to the operating partner depending on how the IRS views the economic benefit. You should document who actually used the funds and for what purpose. A simple memo in the worksheet notes column can save a lot of explanation later. Interest paid on late payment penalties is never deductible. I once saw someone include $400 of penalty interest from a delinquent state payment in their worksheet. It needed to be removed. The worksheet itself is fine for tracking this, but people often forget to subtract the penalty portion before finalizing their numbers.
Get the Full Details

What the Worksheet Cannot Do for You
This is the part nobody talks about. The worksheet only tracks and organizes data. It does not determine deductibility. You still need to apply the rules yourself or have a professional review the numbers. A completed worksheet with every interest payment logged accurately is not the same as a defensible deduction on your return. For very simple situations with one small business loan and no personal mixing, the worksheet might add maybe twenty minutes of work at the end of the year. For anything involving cross-collateralized loans, blended accounts, or home equity used for business purposes, it can add an hour or two of reconciliation. That is still cheaper than fixing errors after filing. If you have more than three interest-bearing loans or frequently restructure debt, consider using accounting software with automatic categorization instead. The worksheet works fine for straightforward cases. It becomes a burden when the debt profile is complex.
Practical Setup Steps
Create a new row for every interest payment or statement period. Most lenders report quarterly or annually, so you might only add three to four rows per loan per year. Include the loan account number, lender name, total interest paid for the period, and the documented purpose of the funds used during that period. If the purpose changes mid-period, split the row into two entries. At year end, sum the deductible interest by category. Business interest goes on Schedule C line 16 or the equivalent for your entity type. Investment interest goes on Schedule B. Personal interest is generally non-deductible after the TCJA except for qualified residence interest. Cross-check your totals against the interest statements your lenders provided. Any discrepancy larger than fifty dollars deserves a review. The worksheet also helps you track the business use percentage of a loan over time. If you started a loan at 80 percent business use in March and shifted to 60 percent by October because you withdrew funds for personal use, the worksheet forces you to calculate the right allocation instead of guessing. That accuracy difference shows up on audits.


