What You Need to Know Before You Start Looking at Numbers
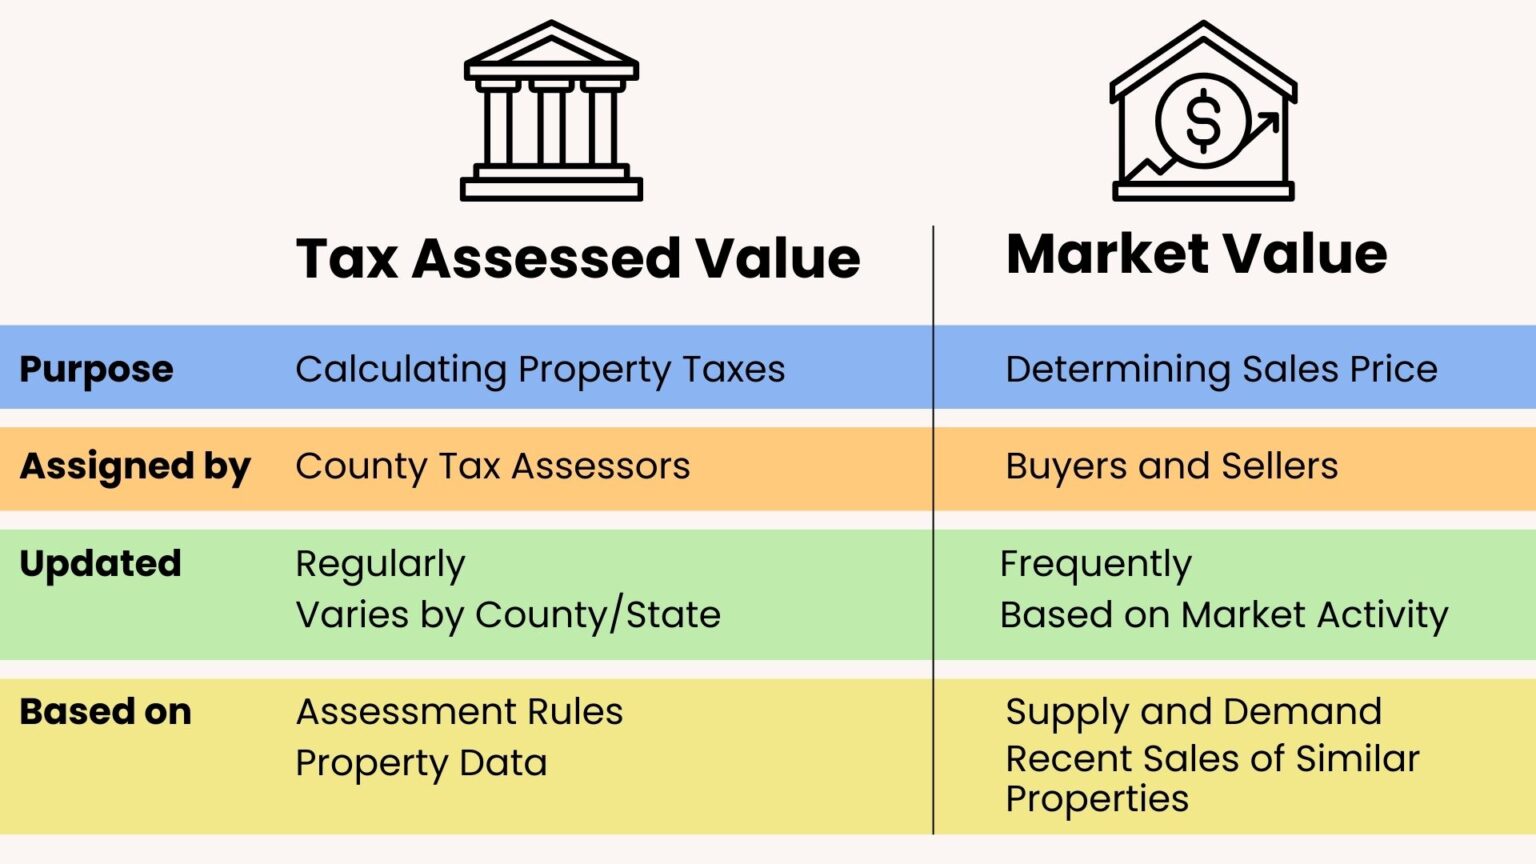
The Tax Assessment Value Vs Market Value debate comes up constantly in real estate, estate planning, and property tax appeals. Most people don't actually understand the difference until they get a surprise bill or an offer gets rejected because the financing fell through. Here is how it works in practice. Market value is what a willing buyer pays a willing seller with neither party under pressure. Assessment value is what the local taxing authority says your property is worth for tax purposes. They are not the same thing. They are not supposed to be the same thing. The gap between them is where problems start.
Tax Assessment Value Vs Market Value — How the Math Actually Works
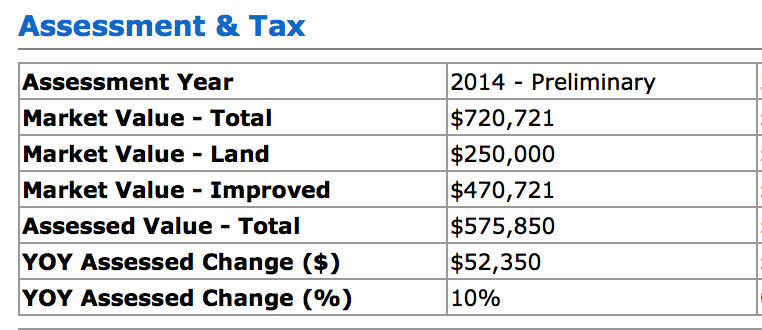
In most jurisdictions, the assessment value is calculated by taking the market value and applying an assessment ratio. That ratio varies wildly depending on where you live. In some counties, properties are assessed at 100% of fair market value. In others, it could be 80%, 50%, or even lower. The exact number matters a lot when you are trying to figure out why your property taxes jumped unexpectedly. I worked on a case a few years back where a commercial property in New Jersey had an assessed value that was roughly 40% below what comparable sales suggested as market value. The assessment lag was two full years because the municipality had stopped revaluations during a budget crisis. The owner filed an appeal, but the taxing district pushed back hard on the methodology because the most recent sale in the area was from three years prior. We ended up using a discounted cash flow analysis instead of direct comparable sales, which the board of taxation eventually accepted. It took nine months and about $18,000 in appraisal costs to save roughly $42,000 annually in reduced taxes over the remaining assessment period. Not every appeal is worth that kind of spend, but the math is worth checking before you write off the possibility. Residential properties tend to have different dynamics. The assessed-to-market ratio is usually lower, but inconsistencies are far more common because mass appraisal systems use statistical models rather than individual inspections. I have seen homes in the same subdivision with assessment ratios ranging from 65% to 89% despite being nearly identical in size, age, and location. The variance was not due to differences in the homes. It was due to when each property was last individually reassessed within the county cycle.
The common misunderstanding is that assessment value equals market value. It does not. Assessment value equals market value times the assessment ratio, minus any exemptions, plus any local surcharges that get layered on top. Exemptions can be structural, like homestead exemptions that reduce the taxable assessed value, or they can be incentive-based, like agricultural or senior citizen programs. Each one changes the denominator of your effective tax rate calculation. Here is a counter-intuitive point that most people miss: a lower assessment value is not always better. If your assessed value drops significantly below what the jurisdiction considers fair market value, the next reassessment cycle could produce a sharp catch-up adjustment. One client in Illinois saw his property taxes drop by $3,200 in year one after an appeal succeeded, then jump by $5,800 in year two when the assessor applied a new median ratio study. The net result was negative over two years because he had locked in a below-market assessment that triggered a steeper correction. You have to model the catch-up risk before you pursue an appeal, especially in jurisdictions with infrequent reassessment cycles. Another thing people get wrong is assuming that assessed value and market value move in the same direction at the same pace. They do not. Assessment values are typically backward-looking, based on data from the prior calendar year or even the prior decade in places with weak compliance. Market values respond to current conditions — interest rates, inventory levels, buyer demand. During a rapid market shift, the divergence can be massive. I reviewed a portfolio in Arizona where market values had increased approximately 35% in two years while assessment values had only moved 12%, creating what the county called an "acquired equity" problem where the gap itself became the issue during refinancing.
Get the Full Details

If you need to determine the actual market value of a property for any reason — sale, refinance, appeal, insurance — the most reliable approach is a comparative market analysis from a licensed appraiser who knows the local jurisdiction's assessment practices. General online estimates are useful for a rough range but completely inadequate for anything involving money or legal exposure. A proper appraisal with reconciliation of sales, cost, and income approaches takes between 10 and 15 business days for a typical residential property and runs roughly $400 to $750 depending on complexity. Commercial properties cost more and take longer because the income approach becomes necessary.
When the Gap Between Assessment and Market Value Becomes a Problem
The gap matters most in three situations: property tax appeals, financing transactions, and estate transfers. In each case, the numbers tell different stories and you need to know which one applies. For tax appeals, the burden of proof is on the property owner in most states. You cannot simply say the assessed value feels too high. You need documentation showing the correct market value and often proof that the assessor's methodology is flawed. I have seen appeals fail because the appellant brought comparable sales that were too old or not truly comparable, and the hearing officer accepted the assessor's valuations by default. Get recent, verifiable data. Three to five closed sales within the last 12 months from the same neighborhood are a reasonable starting point. Properties sold under foreclosure or to relatives do not count as arm's length transactions and usually get excluded by the board. During financing, lenders care about market value, not assessment value. The assessment number might appear on your mortgage application paperwork, but the appraiser hired by the bank determines the collateral value. Some borrowers get confused when the bank's appraisal comes in significantly lower than their perceived market value and the loan amount gets reduced. This has nothing to do with the assessor. It is a separate valuation for a separate purpose.
Estate transfers introduce another layer. The assessed value for property tax purposes has no bearing on estate tax valuation. The Internal Revenue Service requires fair market value as of the date of death, which may differ from both the last assessed value and the current market price. If a property sits in the family for several years between the initial death and the eventual sale, the stepped-up basis is fixed at the date-of-death value, and any subsequent appreciation becomes taxable to the heir. I handled a situation where a client in Pennsylvania inherited a rural parcel with an assessed value of $85,000 but a date-of-death fair market value of $310,000 based on a contemporaneous appraisal. The property sold two years later for $340,000. Without the date-of-death appraisal on file, the capital gains calculation would have been wildly inaccurate and potentially exposed the estate to IRS penalties. Insurance valuation is yet another number entirely. Replacement cost is what your homeowner's insurance policy should be based on, and it has no relationship to either assessed value or market value. A house that costs $420,000 to rebuild from scratch is not necessarily worth $420,000 on the open market, and it certainly does not have an assessment value of $420,000. I have seen homeowners underinsured by 30 to 50% because they used the assessed value as a proxy for replacement cost. When a fire occurred in one case, the insurance payout covered only partial reconstruction and the homeowner had to pay the difference out of pocket. Check your policy's dwelling coverage limit against current construction costs in your area, not against your tax bill. If you are considering filing a tax appeal, start by pulling your current assessment record from the county assessor's website. Note the assessed value, the assessment ratio if it is published, and the year of the last reappraisal. Then request the comparable sales data the assessor used, which they are required to provide in most jurisdictions upon request. Review it for errors — wrong square footage, incorrect room count, misclassified property condition. These errors happen frequently and are the easiest ground for a successful appeal because they require minimal additional work to correct.
The appeal process itself varies by jurisdiction. Some counties require you to file within 60 days of the assessment notice. Others allow appeals year-round. The filing fee ranges from $50 to $500. The hearing can be informal or formal depending on the dollar amount at stake. In New Jersey, for example, appeals over a certain threshold go before the Board of Taxation and can proceed to superior court if dissatisfied. In Texas, you file with the county appraisal district and then potentially go to the state panel. Knowing your local process before you invest time matters. Spending two weeks researching your county's specific procedures usually saves more time than jumping straight into the appeal with incomplete knowledge. One practical note about mass appraisal systems: they are not designed to be precise for individual properties. They are designed to produce defensible aggregate valuations across thousands of parcels efficiently. The error rate at the individual property level is often higher than owners expect. That does not make the system broken, but it does mean that targeted appeals based on specific data errors have a reasonable chance of success even though systemic overvaluation across an entire neighborhood is much harder to challenge. Focus on what you can change rather than trying to fix the whole system. If your goal is simply to understand what your property is actually worth for planning purposes rather than for dispute resolution, a professional appraisal is still the right tool. There is no free alternative that comes close to the accuracy you get from someone who has walked the property, researched the comps, and understands local market dynamics. Online valuation tools give you a number. An appraiser gives you a supported opinion with documentation you can actually use.