Why Most People Miss Real Tax Savings
Most people think tax avoidance is about finding some clever loophole. It isn't. It's mostly about making sure you're already doing the things the code rewards and not accidentally throwing money away on things you could have structured differently. I dealt with this for years filing returns for people who made decent money but still ended up overpaying because nobody showed them how the basics actually work together. Here's the thing nobody tells you: tax-advantaged accounts don't compound the way you think they do. The magic isn't just in the deferral. It's in the basis adjustment. A traditional IRA doesn't save you taxes when you withdraw. A Roth does. That distinction alone changes retirement planning more than any deduction ever will.
Tax Avoidance Strategies For Individuals
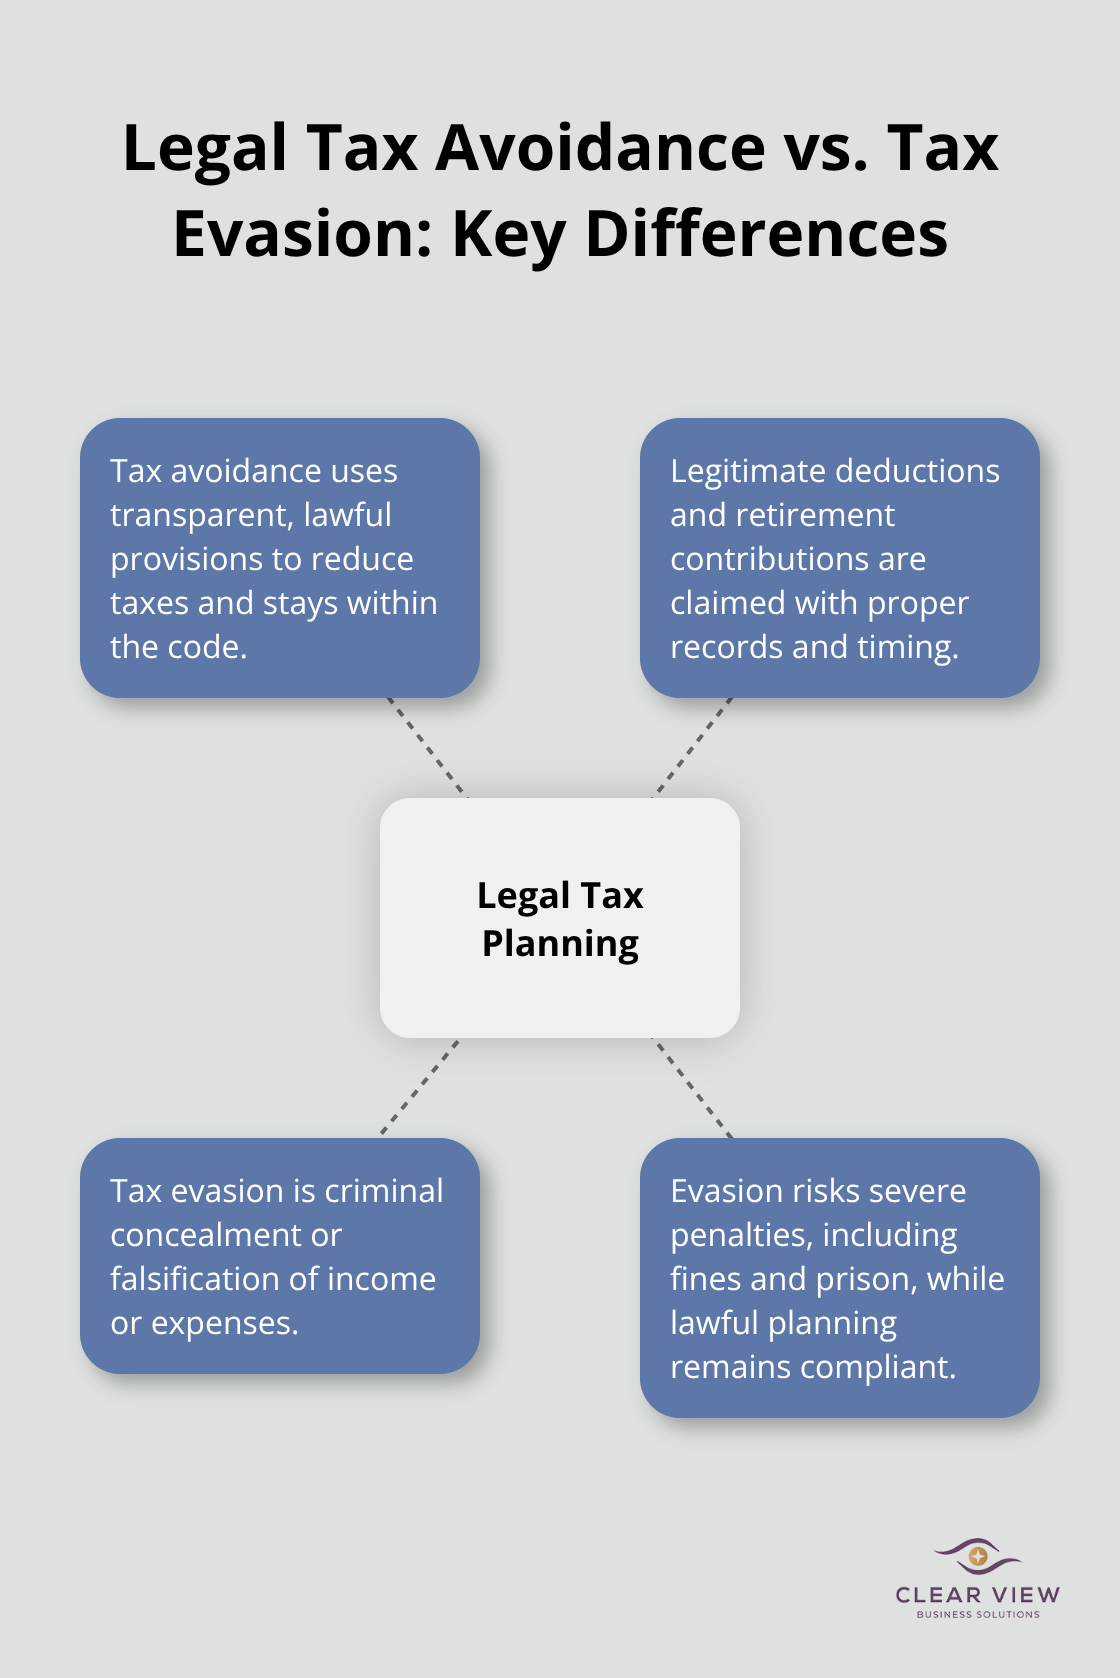
I need to be clear about something before we go further. Avoidance is legal. Evasion is not. The difference matters more than people realize because the line between "aggressive" and "criminal" is thinner than most tax advisors want to admit. I've seen people cross that line without meaning to because they followed a Reddit thread instead of a licensed professional. Let's start with the three buckets that matter most for average individuals. Everything else is optimization theater. 401(k) and Traditional IRA
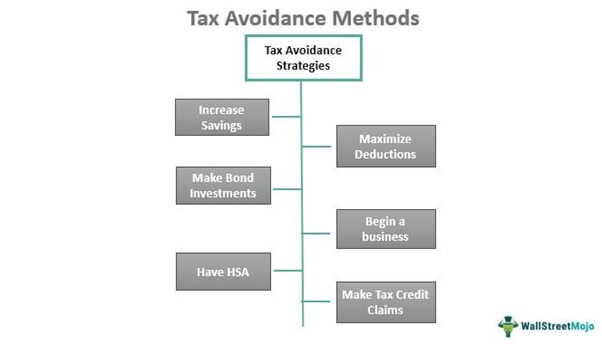
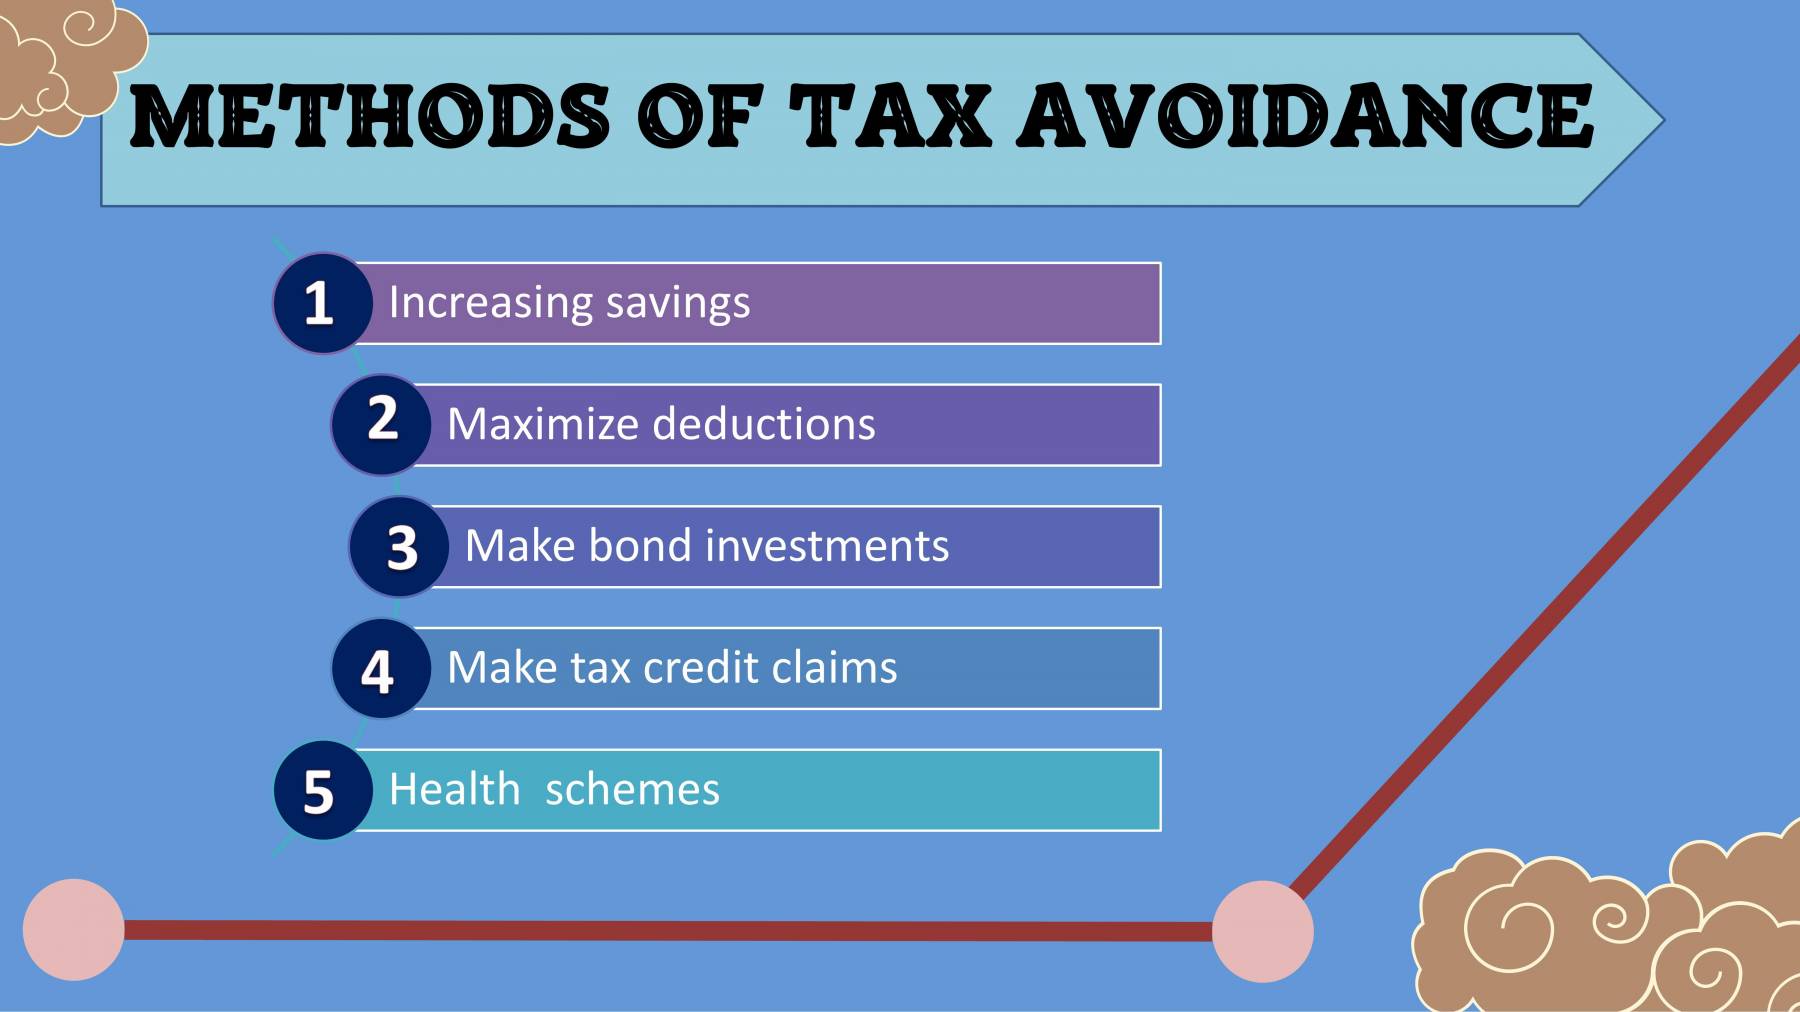
These reduce your taxable income now. That's straightforward. But here's what trips people up: the contribution limits reset every year, and many employers match partially or fully. If you're not getting the full match, you're leaving free money on the table. I had a client once who was contributing to his 401(k) but skipping the employer match because he thought the paperwork was too much. He was losing about $4,200 a year in free money. That's not a tax strategy. That's just stupidity, but it's incredibly common. Roth IRA and Roth 401(k) These don't give you a current-year deduction. They give you tax-free growth and tax-free withdrawals in retirement. The real advantage shows up when you're in a lower tax bracket now than you expect to be later. Younger earners, people with irregular income, or anyone expecting a career jump should heavily favor Roth accounts. The math works against you if you're already in a high bracket and staying there.
Get the Full Details

HSA (Health Savings Account) This is the most underrated account in the American tax code and most people don't even know it exists. Contributions are triple-tax-advantaged: deductible going in, tax-free growth, tax-free withdrawal for qualified medical expenses. After age 65, you can withdraw for anything and just pay regular income tax. It essentially becomes a second retirement account with penalty-free access. I recommend funding this to the maximum every year if you have a high-deductible health plan. The tax savings alone are significant, and the investment potential makes it worthwhile even for healthy people.
Deductions That Actually Matter
Standard deduction or itemizing? This decision alone can save or cost thousands. The standard deduction for 2024 is $14,600 for single filers and $29,200 for married filing jointly. You need to itemize above those thresholds to benefit. Common itemizable expenses include: Mortgage interest (capped at $750,000 of debt for loans taken after December 15, 2017)
State and local taxes (SALT) - capped at $10,000 Charitable contributions (cash donations up to 60% of AGI for 2024) Medical expenses exceeding 7.5% of AGI
Here's where people get burned: they assume every expense is deductible. It isn't. Gym memberships, cosmetic procedures, most travel, regular clothing - these don't count unless there's a very specific reason tied to medical care or business. I once helped someone who kept receipts for everything for three years only to find out half of what they collected had no deductibility basis. Three years of unnecessary record-keeping for nothing.
The Self-Employment Loophole Most People Don't Know About
If you have any side income, even a small one, you should seriously consider forming an LLC or sole proprietorship and treating it as a business. This opens up deductions that W-2 employees simply cannot access. Home office expenses, health insurance premiums, retirement plan contributions beyond standard limits, business-related travel, equipment purchases - all of this becomes deductible when you're operating as a business. The Qualified Business Income deduction (Section 199A) lets you deduct up to 20% of your qualified business income from your taxes. For a side gig making $30,000 a year, that's potentially $6,000 in reduced taxable income. I discovered this accidentally when I was helping a friend who did freelance graphic design on the side. She was paying taxes on her entire $28,000 as if it were wages. Once we set her up properly as a sole proprietor, she took home an extra $4,200 that year. She'd been doing it wrong for five years. The catch: you need real business activity. Selling stuff occasionally doesn't qualify. You need to be operating with some continuity and profit motive. The IRS looks at factors like whether you hold yourself out as a business, whether you keep separate books, and whether you're trying to make a profit. If you're just collecting hobbies, this won't work for you.
Harvesting Losses and Managing Capital Gains
Capital gains tax rates are 0%, 15%, or 20% depending on your income. Long-term holdings (more than one year) get these preferential rates. Short-term holdings are taxed at your ordinary income rate. The difference between 15% and 37% on a $50,000 gain is $11,000. That's not theoretical. That's real money people leave on the table. Capital loss harvesting is the counter-move. If you have investments that have gone down, selling them at a loss can offset capital gains. You can deduct up to $3,000 of net capital losses against ordinary income each year. Any excess carries forward indefinitely. I had a client who had $12,000 in realized losses from a poorly timed stock purchase. By harvesting those losses strategically over two years, he reduced his tax bill by roughly $3,600 combined. Small number, but it was free money he'd been ignoring. Wash sale rules are the trap here. You cannot claim a loss if you buy substantially identical securities within 30 days before or after the sale. I watched someone try to harvest a loss on a tech stock, sell it, and immediately buy it back. The IRS disallowed the deduction and flagged the return. It's an easy mistake to make if you don't know the rule.
Education Benefits That Fly Under the Radar
The American Opportunity Tax Credit (AOTC) and Lifetime Learning Credit (LLC) can reduce your tax bill by up to $2,500 per student per year for AOTC, or $2,000 per return for LLC. These are credits, not deductions, which makes them significantly more valuable. 529 plans offer another angle. Contributions grow tax-free when used for qualified education expenses. Some states offer additional deductions or credits for 529 contributions. I helped a family in New York who was contributing to a 529 and getting an additional state tax deduction on top of the federal tax-deferred growth. They were stacking benefits without realizing it. The downside: 529 plans have contribution limits and withdrawal penalties if used for non-qualified expenses. The AOTC phases out at higher incomes ($90,000 for single, $180,000 for married filing jointly). Know your numbers before you commit.
Real Estate Strategies That Actually Work
If you own rental property, depreciation is your best friend. You can deduct the cost of the property (not the land) over 27.5 years for residential rentals. That's a non-cash deduction that can create paper losses even when the property is cash-flow positive. I had a client with a rental that showed a $8,000 "loss" on paper because of depreciation, which offset other income and saved him roughly $2,400 in taxes that year. He was confused at first until I explained how depreciation works. The passive activity loss rules complicate this. Generally, you need $25,000 of active participation to deduct rental losses against ordinary income. This phases out completely at $100,000 of MAGI. Real estate professionals who meet specific tests can bypass these limitations entirely, but the requirements are strict: more than 750 hours per year in real estate activities and more than half of your personal services in real property trades or businesses.
A Problem I Encountered That Shows Why This Matters
Here's a specific edge case I ran into last year. A client had both a traditional IRA and a Roth IRA. She was nearing retirement and wanted to minimize her required minimum distributions (RMDs). She also had significant capital gains from selling a second home. The interaction between these two issues created a surprising problem. Her RMDs from the traditional IRA were pushing her into a higher tax bracket, which increased the taxable portion of her Social Security benefits. Meanwhile, the capital gains from the house sale were also hitting in the same year. She was looking at a tax bill that would have been thousands higher than necessary. The workaround: we converted part of the traditional IRA to a Roth in a year where her income was temporarily lower due to a sabbatical. This reduced future RMDs and gave her more flexibility in retirement. We also structured the home sale proceeds to be recognized over two tax years by using an installment sale arrangement. The total tax savings came to approximately $18,000 over two years. Not bad for recognizing that these issues interact.
The lesson: individual tax strategies don't exist in isolation. They interact in ways that can surprise you. What looks like a good move in one area can create problems elsewhere.
What Doesn't Work Anymore
I need to mention what has become less effective so you don't waste time on outdated strategies. Tax shelters from the 1980s and 1990s are mostly dead. The laws changed significantly after the Tax Reform Act of 1986 and subsequent legislation. Some passive activity losses that were once broadly available are now restricted. Depreciation methods have tightened. The era of aggressive tax avoidance through complex structures is over for most individuals. Certain charitable strategies have also changed. The CARES Act expanded charitable contribution deductions temporarily, but many of those provisions expired. The rules around non-cash donations became stricter. If you're donating property, get a qualified appraisal and proper documentation. The IRS has been cracking down on overvalued donations.
The Bottom Line
Effective tax avoidance comes down to understanding the structure you're already in and optimizing within it. Most people don't need complex schemes. They need to maximize their retirement accounts, take the deductions they're already entitled to, avoid wash sales, and understand how different income sources interact. The biggest mistake I see is people treating tax planning as an annual afterthought. It should be a continuous process. Quarterly checks, rebalancing strategies mid-year, and understanding how life changes affect your tax situation. A promotion, a marriage, a child, a house purchase - each of these changes your tax landscape significantly. If you're serious about this, consider working with a CPA or enrolled agent who understands your specific situation. Generic advice from the internet can get you in trouble. The tax code is detailed enough that a small misunderstanding can cost you more than the advice would have been worth.
The strategies I've outlined here are legitimate and widely used. They require attention to detail and ongoing management, but they're accessible to anyone willing to put in the effort. The people who benefit most are the ones who treat tax planning as a skill to develop rather than a chore to endure.
