How the Tax Computation Worksheet Actually Works
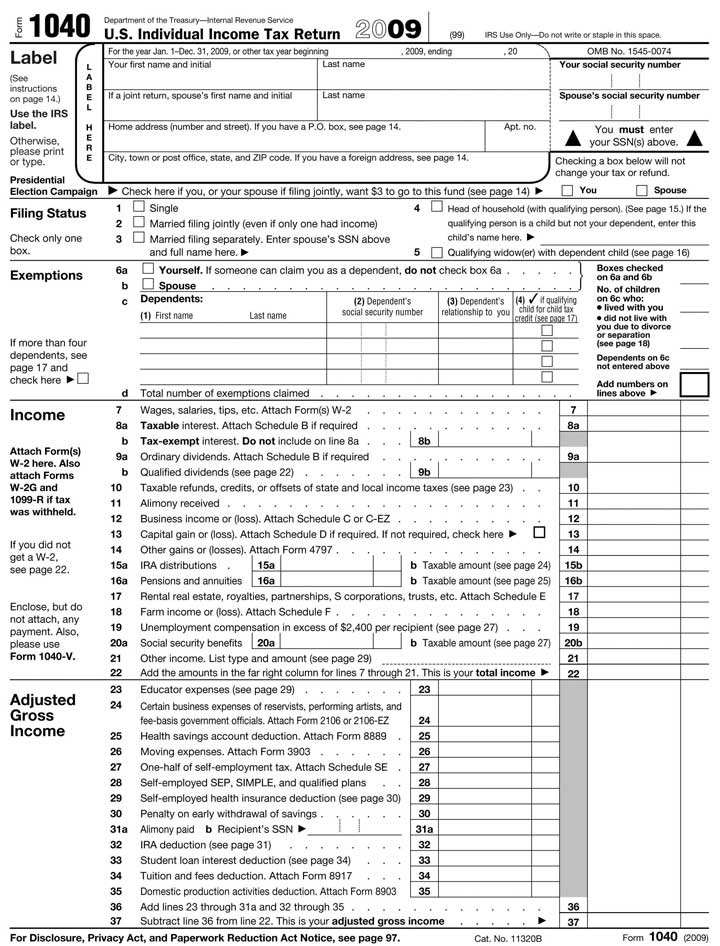
The Tax Computation Worksheet is the section most people skip because it looks intimidating, but it is just a bridge between the standard tax tables and your actual calculated tax liability. When your taxable income falls outside the range covered by the IRS tax tables, you cannot just look up a number anymore. The worksheet forces you to do the math manually using the tax rate schedules. I see people online asking whether they should even bother filling it out. Yes, you need to. The penalty for getting this wrong is that your return will either be rejected electronically or processed with the wrong tax amount, which means a letter showing up three months later asking for more money. Here is how it works in practice. You take your total taxable income from line 15 of Form 1040 and you go to Part I of the worksheet if you are filing as single or married filing separately. You match your income against the income brackets listed for the 2024 tax year. Each bracket has a base tax amount and a marginal rate. You calculate the difference between your income and the bottom of the bracket, multiply by the rate, and add the base tax. That gives you your actual tax before credits. It takes about five minutes if you have your numbers organized. It takes about forty-five minutes if you are scrambling to find where each number came from.
Tax Computation Worksheet 2024 Common Mistakes
I filled out a return last year where the preparer used the 2023 tax brackets on the 2024 worksheet because the forms looked nearly identical. The difference between the two years was small, maybe twenty dollars in tax, but it was still wrong and required an amended return. The IRS does not send you a friendly reminder when this happens. They just adjust the account and send a notice. I learned to verify the bracket thresholds against the actual 2024 IRS publication before touching the worksheet every single time. Another thing nobody warns you about is the interaction between the worksheet and the Qualified Business Income deduction. The QBI deduction reduces your adjusted gross income to arrive at taxable income, but it does not reduce your tax calculation on the worksheet itself. If you are trying to figure out your effective tax rate after the QBI deduction, you have to run the numbers twice. Once to get taxable income and again to back out the real percentage. I use a simple spreadsheet now instead of doing this mentally. It saves me from making errors on returns over a certain complexity threshold. The worksheet also does not handle alternative minimum tax. If you have significant depreciation preferences, incentive stock option exercises, or miscellaneous itemized deductions that were disallowed after the TCJA changes, you might owe AMT instead. The regular tax computation worksheet is irrelevant in those cases because you need Form 6251 first. People confuse the two. They fill out the worksheet, get a tax number, and then later discover their AMT liability is higher. The worksheet result simply becomes a comparison point on Form 6251 to determine which tax is actually owed.
When the Worksheet Becomes Necessary
You only need the computation worksheet when your taxable income exceeds the top threshold of the IRS tax tables. For the 2024 tax year, the tax tables generally cover income up to a certain ceiling depending on your filing status. Once you go above that, the tables stop being useful. The worksheet kicks in automatically at that point. The IRS designed it this way so taxpayers with moderate incomes can still use the lookup method while higher earners do the actual calculation. There is also a second part of the worksheet for married filing jointly taxpayers. The brackets are different, the base tax amounts are different, and the marginal rates align differently. I always double-check the filing status on the form before starting. A common error is using the single filing status section when the return is joint. The tax difference can be thousands of dollars because the joint brackets are wider but not perfectly double the single brackets in every range. If you are dealing with capital gains, the regular worksheet does not apply to that portion of your income. Capital gains use their own tax computation. You calculate the ordinary income tax first using the worksheet, then you calculate the capital gains tax separately using the 0/15/20 percent brackets, and then you add them together. This is one of the trickier parts of the 2024 form. The worksheet itself does not have a line for capital gains. You have to compute that outside the worksheet and then plug the total into the correct line on Form 1040.
Get the Full Details
Where to Get the Official Worksheet
The official Tax Computation Worksheet 2024 is available directly from the IRS website as part of the Form 1040 instructions package. You do not need a separate document. It is printed inside the instruction booklet that accompanies Form 1040 for the 2024 tax year. You can download the PDF from irs.gov under the 2024 Forms and Instructions section. Search for Form 1040 and the worksheet will be included in the back pages of the instructions. Third-party sites host it too, but there is no reason to use them when the source is free and guaranteed to be current. Most tax preparation software handles the worksheet automatically. You enter your numbers and the program computes the tax without showing you the actual worksheet. This is fine for simple returns. When your return involves multiple income sources, adjustments, deductions, and credits, it is worth looking at the worksheet output from the software just to confirm the numbers make sense. Software can silently apply the wrong bracket if you enter something in the wrong field.
Limitations and When to Step Away
The worksheet is only reliable if your situation is straightforward. It breaks down if you have foreign earned income exclusion, if you are subject to the excess business loss limitation, or if you are claiming the domestic production activities deduction, which was repealed but still affects some pass-through calculations indirectly. In those cases, the worksheet alone does not capture the full picture. You need additional forms layered on top. I recommend using the worksheet for ordinary wage income, standard deduction, and basic investment income scenarios. If your tax situation involves self-employment, rental properties, stock options, or any kind of pass-through entity, you should probably use professional software or consult a preparer who understands how the worksheet interacts with those forms. The worksheet is not wrong. It is just incomplete on its own for complex returns. The one honest bottleneck with the 2024 worksheet is that the IRS does not publish a simplified version for taxpayers who find the full worksheet confusing. You either do the worksheet or you use software that does it for you. There is no middle ground officially. Some tax forums suggest breaking the calculation into smaller pieces on paper, but that introduces its own risk of transcription errors. The cleanest approach is to verify your final tax number against the worksheet after the software runs it, not to do the worksheet by hand unless you have no other option.