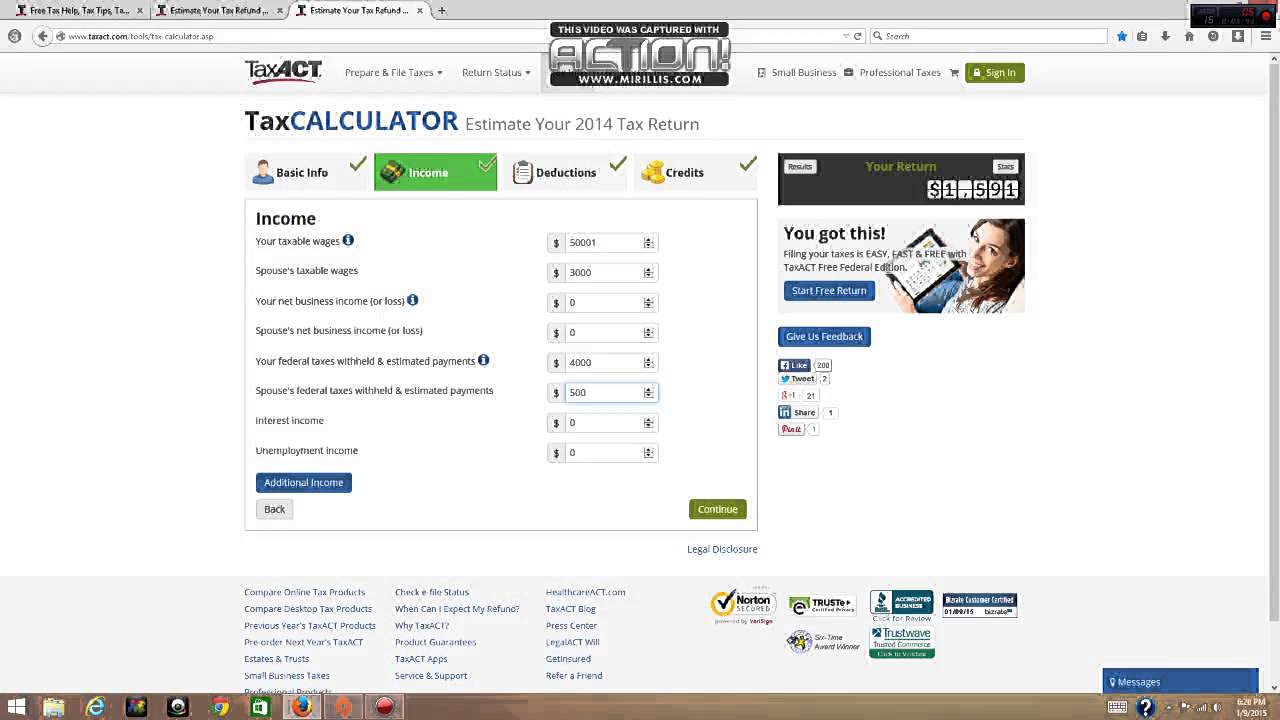
Understanding the Tax Estimator 2017 Calculator
Most people pull up a 2017 tax estimator because they either lost a W-2 somewhere in the mess of paperwork or they're trying to reconcile what they actually owed versus what they estimated during the year. The 2017 tax year was the last one before the TCJA completely rewrote the rules, which means any tool you use has to account for the old bracket structure, the pre-reform standard deduction amounts, and a bunch of phase-outs that don't exist anymore. I've seen plenty of taxpayers get tripped up by this, especially when they're comparing 2016 and 2017 side by side. I'll walk through how these calculators work, where they fall short, and what I usually tell people to do when the output looks slightly off. Most of it is practical stuff you won't find in the IRS publications.
How the Tax Estimator 2017 Calculator Actually Works
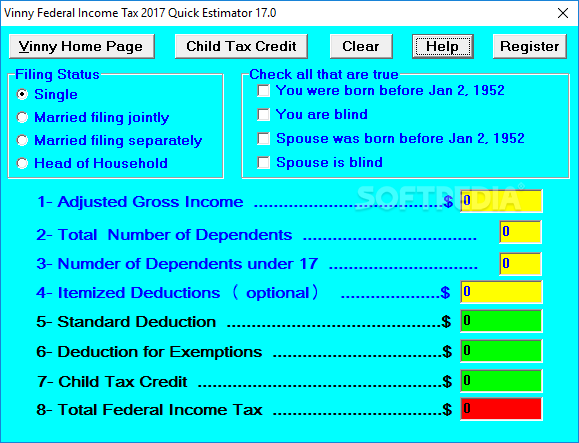
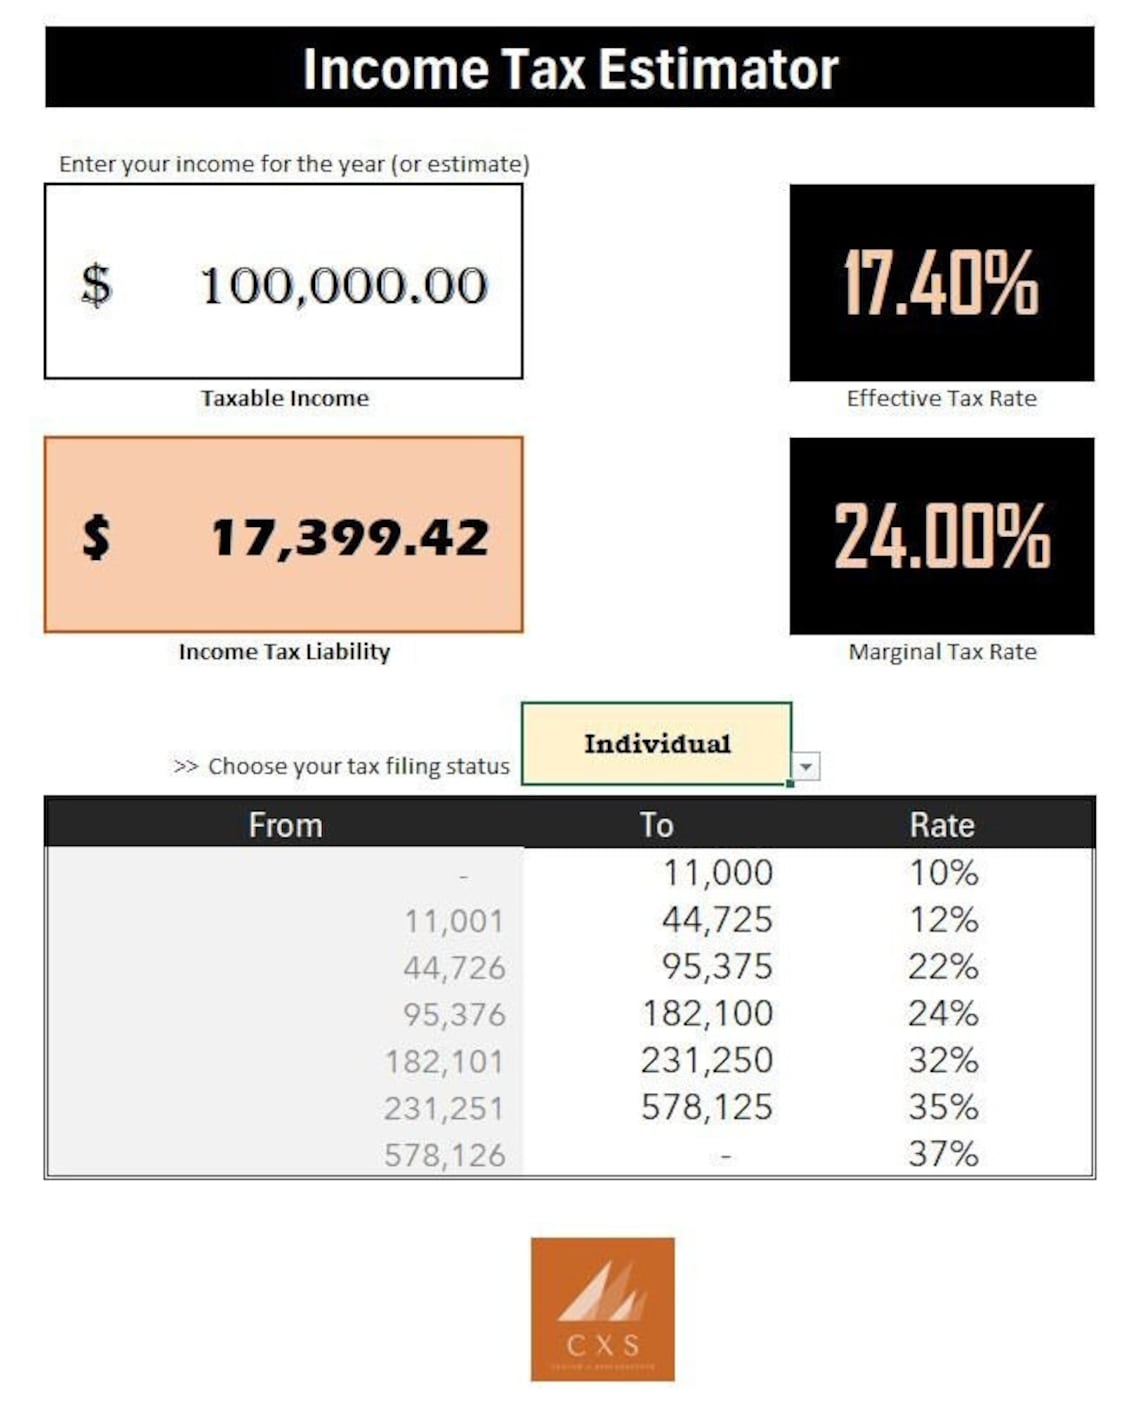
At its core, the calculator takes your filing status, gross income, deductions, credits, and any other relevant inputs, then runs them through the 2017 tax tables and forms. It computes your taxable income by subtracting either the standard deduction or itemized deductions from your AGI. For 2017, the standard deduction was $6,350 for single filers and $12,700 for married filing jointly. Those numbers jumped after 2017, so if you're comparing it to 2018 onward, don't get confused. The brackets for 2017 were: 10% up to $9,325 single, 15% up to $37,950, 25% up to $91,900, 28% up to $191,950, 33% up to $416,700, 35% up to $417,100, and 39.6% above that. Married filing jointly had different thresholds that roughly doubled but weren't exactly double in every bracket. The calculator factors all that in. Then it applies the qualified dividend and long-term capital gains rates, which were 0%, 15%, or 20% depending on your income. It subtracts any tax credits directly from your liability. Simple in theory. The devil is in the details.
Where These Calculators Go Wrong
The biggest issue I run into is that most free online 2017 tax estimators don't fully account for the interaction between the Net Investment Income Tax and the Phase-Out of Itemized Deductions, also known as Pease. If you're earning above certain thresholds, your itemized deductions get reduced. For 2017, that started at $259,400 for single filers and $311,300 for married filing jointly. The NIIT kicks in at $200,000 single and $250,000 married. Most basic calculators miss this entirely, and the difference can be a few hundred dollars depending on your situation. Another common gap is the Alternative Minimum Tax. The 2017 AMT exemption was $54,300 for single filers and $84,500 for married filing jointly, with phase-outs starting at $117,300 and $157,650 respectively. If your calculator doesn't run the AMT worksheet, your estimated tax could be way off, especially if you have large deductions like state and local taxes or miscellaneous itemized deductions subject to the 2% floor. I once had a client who used a free 2017 estimator and it showed him owing about $4,200. When we ran the actual numbers with AMT and the Pease phase-out included, he owed closer to $6,100. The gap wasn't huge, but it was enough to trigger an underpayment penalty he hadn't planned for. He'd been paying estimated quarterly taxes based on the lower number the calculator gave him.
Get the Full Details
What to Check Before You Trust the Output
First, confirm the calculator actually uses 2017 parameters and not the current year's. A lot of sites just pull default tax tables and nobody updates them properly. Second, look for whether it handles self-employment tax, which is 15.3% on net earnings and can quietly add $2,000 to $4,000 to your liability if you have a side gig. Third, check if it accounts for the Saver's Credit and the Earned Income Tax Credit properly, since those are refundable and can change your refund significantly even if you thought you wouldn't qualify. If you're self-employed and running a sole proprietorship, make sure the calculator subtracts the deductible portion of self-employment tax from your AGI. That adjustment matters. It's easy to overlook and it affects your taxable income directly. I also recommend running your numbers through at least two different tools if possible. If one shows you getting a $3,000 refund and another says you owe $800, something is misconfigured in at least one of them. Cross-checking catches more errors than you'd expect.
Troubleshooting When the Numbers Don't Add Up
If your calculator result seems off, start by verifying your filing status. That's the most common source of error. People accidentally select married filing separately when they should be filing jointly, or vice versa. The tax brackets for MFS are brutal and the standard deduction is only $6,350, same as single, but you lose access to several credits. Next, double-check your income types. Wage income, interest, dividends, capital gains, rental income, retirement distributions, and business income are all treated differently. If you have a 1099-R showing a traditional IRA distribution, the calculator should include it in your AGI but also apply the proper tax treatment. If it's a Roth conversion, that's taxable income even though it's not "earned." Mix that up and your estimate will be wrong. One edge case I deal with fairly often involves the Foreign Earned Income Exclusion. For 2017, the maximum exclusion was $102,100. If you're a US citizen working abroad and qualify, most consumer calculators won't factor this in at all. You'd need to manually adjust your gross income downward by the exclusion amount before feeding it into the estimator, or just run the numbers manually on Form 2555. I've lost count of the times someone came to me with a "refund" the calculator predicted, only to discover later they hadn't claimed the FEIE and their actual liability was substantially higher.
For most people doing straightforward W-2 income with maybe a 401(k) contribution and the standard deduction, a basic 2017 tax estimator will get you within 5% of the real number. If your situation involves any of the items above, plan on spending another 20 or 30 minutes going through it line by line instead of relying on the tool alone.
When to Move Beyond a Calculator
If you're filing a simple return with no self-employment income, no investment gains beyond a 1099-DIV, and no complex deductions, a free 2017 tax estimator is fine for a rough idea. It'll save you the time of filling out the actual forms just to see what the number comes out to. But once you have a Schedule C, rental income, stock option exercises, or anything that touches the AMT, you're better off using paid software or a CPA. The calculator might save you fifteen minutes, but it could cost you two hundred dollars in adjustments and penalties down the line. I generally recommend the Software for the 2017 tax year for anyone with a moderately complicated return. It has built-in audit risk analysis and it walks you through the AMT computation, which most free calculators skip entirely. If you're comfortable doing it yourself and your situation is straightforward, free tools are adequate. Just don't treat the output as gospel when your actual filing involves more than a couple of W-2s.