The paperwork nobody tells you about
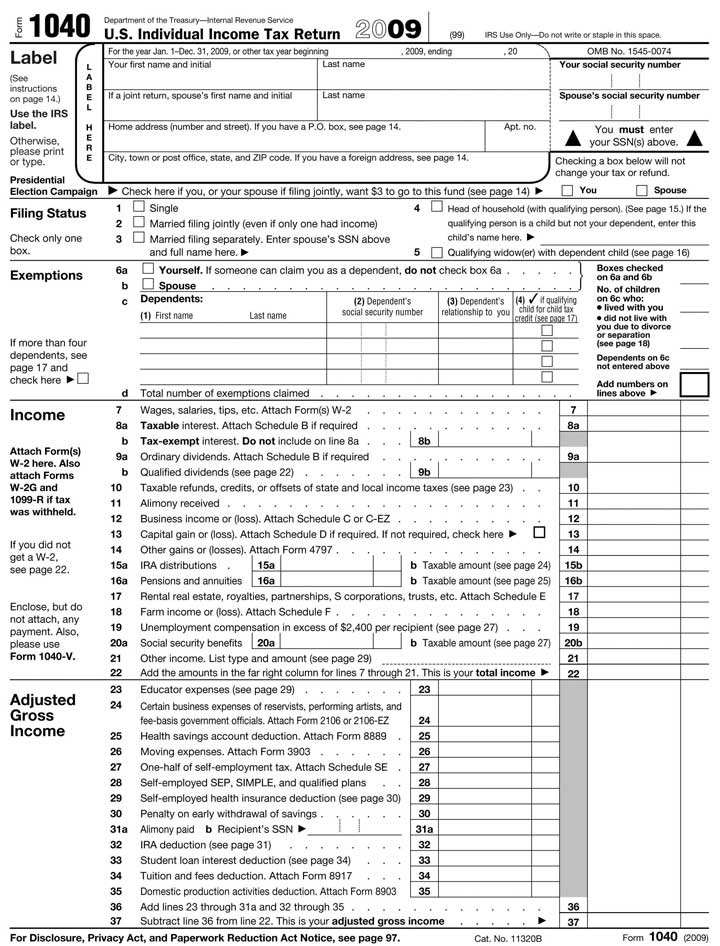
If you run a business, you will deal with tax forms whether you want to or not. Most owners learn this the hard way, after receiving a notice from the IRS or waiting four months for a refund that should have come much sooner. The forms themselves are not difficult. What trips people up is the timing, the mismatch between income you receive and income you report, and the small details that change depending on how you structured your entity. Here is what actually matters. You are probably looking at four or five core documents, not twenty. Everything else branches from those. The single most important distinction is whether you are a sole proprietor, a partnership, an S corporation, or a C corporation. Each one uses a different form to report income, and each one has different deadlines. Get the entity type wrong and the rest of the process becomes a mess of corrections and amended filings. For sole proprietors and single-member LLCs, you will file Schedule C with your personal Form 1040. That is it. The income goes on line 3 of Schedule C, deductions below the line, and the net profit or loss flows to your individual return. If you had employees, you also need Schedule B if you paid interest, and quarterly if you withheld payroll taxes, Form 941. Simple on paper. Not always simple in practice.
I learned this the hard way back in 2019. I was running a consulting business as a single-member LLC at the time, and I had hired a bookkeeper who classified my independent contractor payments as W-2 wages instead of 1099 expenses. By the time I caught it, I had already filed my return. The fix was filing Form 1040-X, an amended return, and requesting a corrected 1099-NEC from the contractor. Took me about three weeks of back-and-forth and cost me nothing in penalties because the error was mine, not theirs. The lesson was simple: verify every 1099 before you file, even if it comes from your own accounting software. Software does not think. It just copies what you tell it to copy.
What you actually need to file
Partnerships use Form 1065. It is an informational return. The partnership itself does not pay income tax. Instead, each partner receives a Schedule K-1 showing their share of income, deductions, and credits. You then report that on your personal 1040. The trap here is that the K-1 instructions often do not match the partner's actual tax situation. A partner might need to adjust items based on their own basis limitations or passive activity rules. I have seen two partners in a real estate partnership get K-1s that showed depreciation deductions larger than their basis allowed. They filed anyway and got flagged during an audit. The workaround is to calculate your own basis before the K-1 even arrives, not after. S corporations file Form 1120-S. Like partnerships, they are pass-through entities. Shareholders receive a Schedule K-1. The critical difference from a partnership is that S corp owners who work in the business must be paid a reasonable salary through payroll, with employment taxes withheld. Skip that and the IRS will reclassify a portion of your distributions as wages, add Social Security and Medicare taxes, and assess penalties. Reasonable compensation is not a fixed percentage. It depends on your industry, your role, your geography, and what similar businesses pay. I once advised a client who was taking $40,000 in salary while pulling $180,000 in distributions. We ran a benchmark study using compensation data from comparable companies and ended up adjusting to $72,000 before filing. That saved us from a much more expensive conversation with the IRS later. C corporations file Form 1120. This is the only structure where the entity itself pays tax at the corporate rate. Distributions to shareholders are dividends and taxed again on the personal return. Double taxation is the reason most small businesses avoid this structure unless they have a specific reason for it, like retaining earnings for growth or dealing with fractional ownership that makes pass-through treatment impractical.
Get the Full Details

Payroll and quarterly estimated taxes
If you have employees, you are on a completely different clock. Federal payroll taxes are due quarterly via Form 941. If you withhold more than a certain threshold during the quarter, you have to deposit those taxes monthly or semi-weekly, not quarterly. The deposit schedule depends on your lookback period, which is calculated from your tax liability in the previous four quarters. Most small businesses start as monthly depositors and only move to semi-weekly when their withholding crosses roughly $50,000 in a lookback period. Form 940 is your annual federal unemployment tax return. It is easy to overlook because the rate is low, about 6 percent on the first $7,000 of wages per employee, but most states give you a credit that reduces that to 0.6 percent if you are current on state unemployment contributions. If you pay your state unemployment taxes on time, you are effectively paying 0.6 percent federally. Missing that credit costs money without any real reason. Estimated taxes for business owners usually come down to Form 1040-ES. You pay quarterly if you expect to owe more than $1,000 in tax after subtracting withholding. The safe harbor rule says you avoid underpayment penalties if you pay either 90 percent of your current year tax or 100 percent of your prior year tax, whichever is less. If your prior year adjusted gross income was over $150,000, that jumps to 110 percent. This matters most in years where your income varies significantly, like a project-based business that makes most of its money in Q4.
Information returns you probably forgot about
Form 1099-NEC replaced the old 1099-MISC box for non-employee compensation. You must issue it to anyone you paid $600 or more in the course of your business during the year, including contractors, freelancers, and attorneys. The deadline is January 31st. Filing it with the IRS happens by February 28th if you file paper or March 31st if you file electronically. The penalty for late filing starts at $70 per form in 2026, goes up to $190 if you file more than 30 days late, and can reach $380 per form if you file intentionally late. That last tier applies if you owe more than $500,000 in total corrections during the year. Form 1099-K is the payment card and third-party network form. It applies when you receive over $5,000 in gross payments through platforms like Stripe, Square, or PayPal. The threshold was supposed to drop to $600 in 2025 but the IRS delayed that again. As of now, it stays at $5,000. You still need to reconcile your 1099-K with your actual sales because these forms include gross payments, not net revenue, and they include things like refunds and chargebacks that do not belong on your tax return.
A practical filing workflow
Set up a system in October. Most people wait until January, which means they are working under time pressure with incomplete information. In October, pull your annual summaries from your bookkeeping platform, reconcile your bank and credit card accounts, and confirm that every vendor you paid over $600 has the correct TIN and address. If a contractor did not provide a W-9, request one immediately. You cannot accurately prepare your 1099s without it, and you risk backup withholding if you file with an incorrect number. Run your depreciation schedule before you start filing. If you purchased equipment, vehicles, or furniture during the year, you need to decide between Section 179 expensing, bonus depreciation, and regular depreciation. Section 179 lets you deduct the full purchase price in the year you place the asset in service, up to $3,050,000 in 2026, with a phase-out threshold at $3,050,000 in total equipment purchases. Bonus depreciation is currently at 60 percent for property placed in service in 2026, dropping 20 percent each year until it reaches zero in 2029. Regular depreciation spreads the deduction over the asset's useful life. Most small business owners max out Section 179 on qualifying assets because it gives them the largest immediate deduction, but that is not always the right call if you expect higher income in future years. I ran into a situation last year where a client had purchased a $45,000 vehicle for his landscaping business and wanted to Section 179 the entire amount. The problem was the luxury automobile depreciation limits cap the first-year deduction at around $25,000 for vehicles over 6,000 pounds, and much less for lighter ones, regardless of Section 179. We ended up splitting it: Section 179 on the first $25,000 limit, then bonus depreciation on the remainder, then regular MACRS depreciation on whatever was left. He still got a large deduction upfront but avoided the audit risk of claiming more than the code allows.
Where people get stuck
The home office deduction is one of the most misunderstood items. You need to use part of your home exclusively and regularly for business. "Regularly" means consistently. A desk you use two days a week does not qualify. The exclusive use test is strict. If your spare bedroom doubles as a guest room, it generally does not qualify, though the IRS has been somewhat flexible with single-room offices that serve dual purposes in practice. The two calculation methods are the simplified option, which lets you deduct $5 per square foot up to 300 square feet, or the regular method, which allocates actual expenses based on the percentage of your home used for business. The simplified method is faster but often under-reports your deduction. The regular method takes more work but frequently results in a larger write-off, especially if you have high mortgage interest or utilities. Mileage is another area where owners lose money by being too conservative. The standard mileage rate for 2026 is 70 cents per mile for business use. You do not need a fancy tracking app. A spreadsheet with date, origin, destination, purpose, and miles driven is enough. The key is consistency. Record every trip that qualifies, not just the big ones. Business owners I work with who track every trip average about 12,000 to 18,000 deductible miles per year. That translates to $8,400 to $12,600 in deductions at the current rate, which directly reduces your taxable income. Health insurance premiums for self-employed individuals can be deducted on Schedule 1 of your 1040, but only if you had net profit from the business that year. If your business shows a loss, you cannot take the deduction. This is not a loophole. It is a structural rule. The deduction also cannot exceed your earned income from the business, and you cannot claim it if you are eligible to participate in a subsidized health plan through a spouse's employer.
State and local considerations
Federal forms are only part of the equation. Most states have their own equivalent of Schedule C, and many require a separate state 1099 filing. California, New York, and Pennsylvania are particularly aggressive about matching 1099s between state and federal filings. If you file a 1099 with the IRS but not with the state, you will get a notice. Some states also impose a gross receipts tax or a minimum franchise tax that is due regardless of whether your business made any profit. Delaware charges an annual franchise tax of $300 for LLCs, for example. Oregon has no income tax but requires a annual report fee. Check your specific state requirements before you assume the federal forms cover everything. You will make a mistake. It is not a matter of if. The most common error I see is forgetting to attach a Schedule K-1 to a Form 1065 or 1120-S filing, or submitting a K-1 with the wrong allocation of income. The fix is usually an amended return, but amendments take time. An amended partnership return requires filing Form 1065-X within three years of the original filing date or two years after the tax was paid, whichever is later. Missing that window closes the door. Another frequent issue is failing to file a required 1099 and then trying to fix it after the deadline. The best approach is to file as many as you can by the January 31st deadline, even if the list is incomplete. You can always file additional 1099s later with a late filing penalty. What you should never do is ignore it. The IRS cross-references 1099s with recipient tax returns, and a missing form shows up in their automated system within about six weeks of e-filing. You will get a CP225J notice asking why the income does not match. Responding to that notice is far more expensive than filing the form on time.
Tools and resources
IRS.gov has every form and instruction you need, free. Form 1040, Schedule C, Form 1120-S, Form 1065, Form 941, Form 940, 1099 series, Form 1040-ES. The instructions have become much more detailed over the past decade. Each form now includes a worksheet section and examples that cover edge cases. Read the instructions before you fill anything out. The form alone does not tell you everything. For bookkeeping, QuickBooks Self-Employed and QuickBooks Online are the most common choices for small business owners. Xero and FreshBooks are solid alternatives. The one thing all of them do well is generate 1099 reports and estimate your quarterly tax payments. The one thing none of them do well is handle multi-state tax obligations or complex depreciation scenarios. When your business gets to the point where you are spending more than two hours a month on tax-related questions, that is the point where a CPA or enrolled agent pays for themselves. The bottom line is that tax forms for business owners are manageable if you stay ahead of deadlines and understand which forms apply to your specific structure. Most of the pain comes from surprises, not complexity. Set up your records early, reconcile before you file, and do not assume that what your software generates is automatically correct. The IRS does not care what your software thinks. They care what the form says.