How Tax Havens Actually Work In Practice
The idea that tax havens are some mysterious offshore fortress is mostly marketing from people who want to sell you a package. In reality, most of what passes for tax haven structuring is just routing income through jurisdictions with favorable treaty networks and registration requirements. I've watched companies burn six figures on structures that ultimately achieved nothing because nobody checked the substance rules before filing. Let me walk through how this actually functions on the ground, not how a lawyer's brochure describes it.
What People Mean When They Say Tax Havens In The World
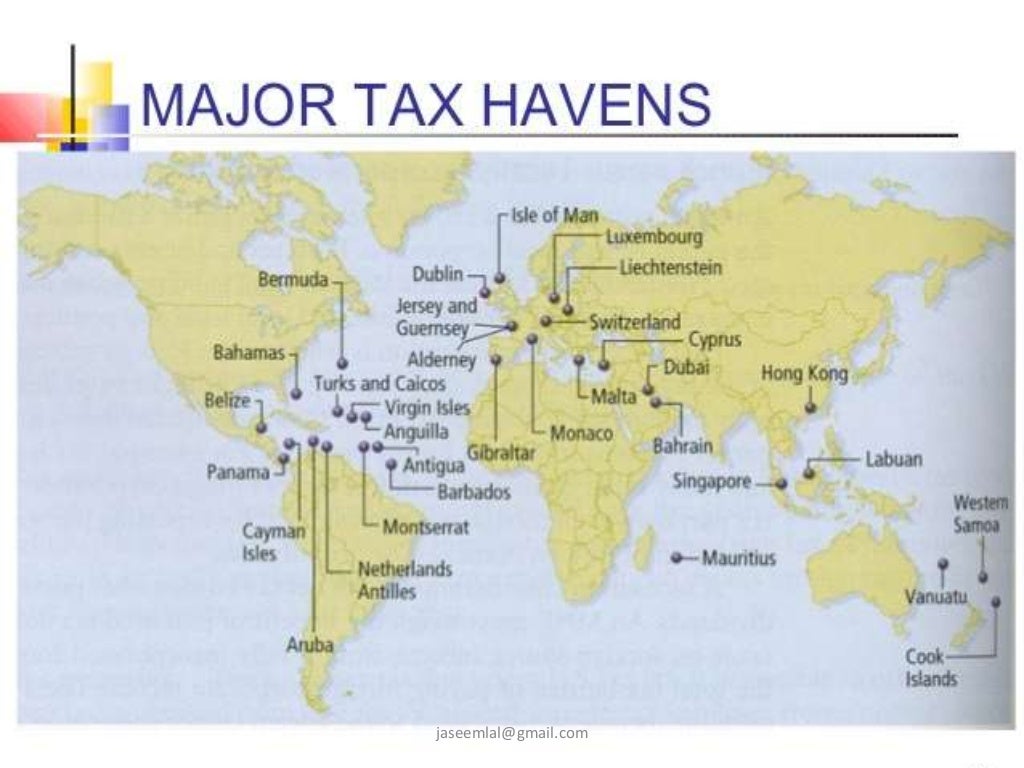
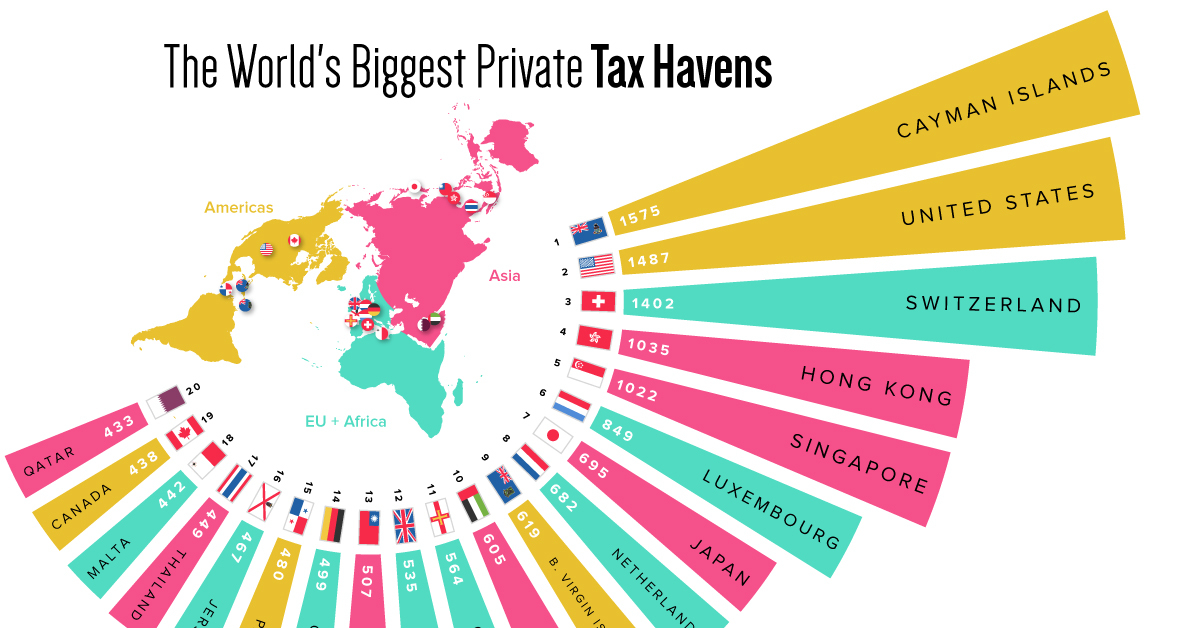
A tax haven is simply a jurisdiction that taxes little to nothing on certain types of income and maintains information secrecy or weak exchange protocols. That definition covers about forty to fifty jurisdictions globally depending on who you ask. The OECD list, the EU blacklist, and the CARICOM register all differ slightly because each has its own political agenda. The most commonly referenced ones fall into tiers. Tier one includes places like the Cayman Islands, Bermuda, and the British Virgin Islands where corporate registration is fast, anonymous in practice if not in law, and there is zero corporate income tax. Tier two covers countries like Ireland, the Netherlands, and Luxembourg which are technically low-tax but have been heavily shaped by EU state aid rulings and the OECD BEPS framework. Tier three includes places like Singapore and the UAE free zones where the tax rate is low but compliance expectations are genuinely higher. Most people trying to set up a structure want tier one. Most of them end up with something that looks like tier one on paper but gets reclassified as resident elsewhere under controlled foreign corporation rules once they actually start operating.
The Mechanics Nobody Talks About First
Setting up an offshore entity is trivially easy. You pay a registered agent three to eight hundred dollars and you have a company in forty-eight hours. The hard part starts when you try to use that company without triggering scrutiny from your home tax authority. Here is the practical workflow. You incorporate in a jurisdiction like Nevis or the BVI. You open a bank account, which takes longer than anyone tells you, usually four to ten weeks if you are doing it properly with a mid-tier provider. Then you need to make sure the entity has economic substance. This is the part that catches most people out. Since 2019, the BVI, Cayman Islands, and a growing number of other jurisdictions require entities to demonstrate real substance. That means physical office space, local employees, and a minimum level of directed and managed activity within the jurisdiction. If you do not meet this, the entity can be struck off and information shared automatically with your home country's tax authority under the Common Reporting Standard.
Get the Full Details
I learned this the hard way in 2021. A client had a BVI holding company that owned intellectual property for their e-commerce business. The company generated about two million in annual licensing revenue and paid zero tax. Everything looked clean on paper. Then the BVI Economic Substance Authority sent a request for information about board meetings, director attendance, and expense records. My client had none of this. We ended up restructuring the entity into a Delaware holding company with a proper operating agreement, paying substantive U.S. tax on the IP income, and accepting a significantly higher effective rate. The alternative would have been disclosure to both the BVI and the IRS under the automatic exchange framework, which would have triggered penalties roughly three times the back taxes owed.
The Real Pitfalls And How To Avoid Them
The biggest mistake people make is assuming that having an offshore company means they do not have tax obligations at home. Your citizenship, residency, and place of incorporation are three separate things that all matter. If you are a U.S. citizen, you are taxed on worldwide income regardless of where the company is registered. The Foreign Earned Income Exclusion and foreign tax credits help, but they do not eliminate the filing requirement. Form 5471 and FBAR are mandatory and the penalties for non-compliance start at twenty-five thousand dollars and scale up from there. If you are not a U.S. person, the rules are less aggressive but still substantial. Most developed countries have CFC rules that attribute passive income earned by offshore entities back to the resident shareholder. Ireland has strict exit taxation. The UK has dormant foreign company rules that can resurrect tax liability decades later. Germany treats foreign foundations as transparent in many cases. Another common error is confusing tax neutrality with tax advantage. A jurisdiction with zero corporate tax is not automatically better than one with a low corporate tax and a strong treaty network. The Netherlands may tax at twenty-five percent but its treaty with the U.S. eliminates withholding tax on dividends and interest in most cases. A BVI company with zero tax may face thirty percent withholding on every payment it receives because there are no treaties to override the default statutory rates. This is counter-intuitive for most people and it matters enormously when you are moving millions in intercompany payments.
A Practical How-To
If you are considering this, here is the sequence that actually works without getting flagged. First, determine your tax residency. This is not your passport country. This is where you spend more than one hundred eighty-three days, where your family lives, where your bank accounts are, where you receive your salary. Get this wrong and everything downstream is wrong. Second, identify the type of income you want to structure. Passive investment income, trading income, intellectual property royalties, and service fees are all treated differently under domestic law and treaty provisions. There is no single structure that works for all of them.

Third, choose the jurisdiction based on substance requirements and treaty access, not just the headline tax rate. The Cayman Islands is excellent for investment funds. Delaware is often the right answer for holding companies owned by U.S. persons. The UAE free zones make sense for regional trading operations but only if you maintain real office and staffing there. Fourth, engage a qualified tax advisor in your home jurisdiction before you incorporate anything. This is not optional. A proper advisor will cost you two to five thousand dollars for an initial assessment and might save you two hundred thousand in penalties and back taxes. Most people skip this step and regret it. Fifth, maintain proper books from day one. Board resolutions, expense documentation, transfer pricing studies if you are related-party transacting, and annual filings in every jurisdiction where you have a nexus. The administrative burden is real and it never goes away.
When It Simply Does Not Work
There are scenarios where tax haven structuring is a waste of time and money. If your annual revenue is under five hundred thousand dollars, the compliance costs alone typically exceed any tax benefit. If you operate in a highly regulated industry like financial services or healthcare, offshore structures attract disproportionate scrutiny regardless of how clean they are on paper. If you are a resident of a country with aggressive beneficial ownership registries and cross-border audit programs, the likelihood of detection is high even with professional setup. Also, the landscape is changing rapidly. The OECD's Pillar Two framework, which establishes a global minimum corporate tax of fifteen percent, is being implemented by over one hundred jurisdictions. This will eliminate much of the advantage of traditional low-tax jurisdictions for large multinational groups. By 2026, the actual benefit of many existing structures is already being eroded. If you are building something new, factor this in from the start rather than discovering it three years later.
Bottom Line
Tax haven structuring is not a secret weapon. It is a specialized area of international tax planning that requires ongoing maintenance, professional advice, and a clear understanding of how your home country's rules interact with foreign jurisdiction requirements. The people who make it look simple are usually the ones selling you something. The people who actually do it well tend to be very quiet about it.