The Actual Process Nobody Talks About
Most small business owners treat tax prep like something that happens once a year when the panic sets in. It doesn't work that way. The people who sleep fine in April are the ones who've been quietly handling pieces of their taxes for eleven months straight, and I'm going to walk you through how that actually looks.Tax Preparation For Small Business: A Practical How-To
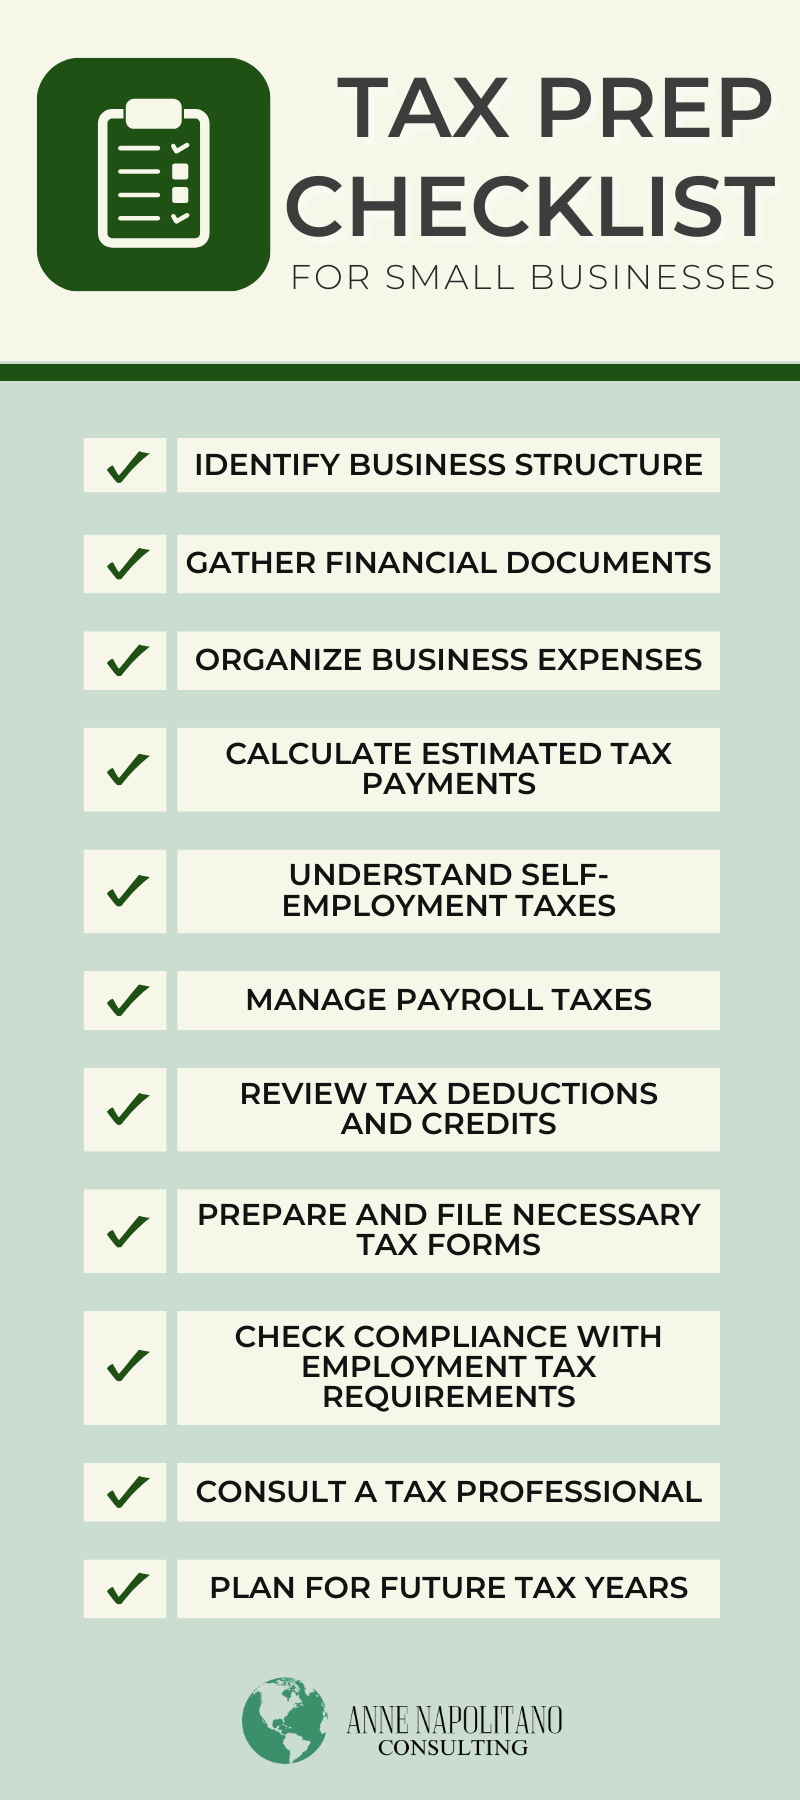
Start by picking your accounting method and sticking with it. Cash basis or accrual basis — cash basis is simpler and fine for most small operations under $25 million in revenue. That's the IRS threshold you'll hit eventually, but right now if you're booking revenue when money hits the bank and expenses when they leave, you're good. Don't switch methods mid-year. That requires filing Form 3115 and usually just creates a mess for no real gain. I run my books in QuickBooks Online, and I sync it directly to my bank and credit card accounts. This is where you save or lose hours. The automated categorization is about 70% accurate out of the box. You spend your Tuesday evenings for the first month scrubbing miscategorized transactions. After that, it stays clean. I also run a separate expense for merchant fees and payment processor charges — Square, Stripe, PayPal — because that deduction gets missed constantly and adds up fast for anyone processing card payments. Here's the thing about quarterly estimated taxes that trips people up: you don't calculate them on your annual profit. You calculate them on your expected annual income, and then you adjust mid-year when things shift. The penalty for underpayment is 5% to 8% depending on how late you are, and it compounds monthly. I set a rule — 25% of every client payment goes straight into a separate savings account labeled QTR TAX. It earns zero interest but it keeps me honest. When April comes and I need to pay Q1 through Q4 estimated, the money is already there.
Self-employment tax is the part that surprises people. You pay Social Security and Medicare on 92.35% of your net profit from self-employment. That's 15.3%. On top of your regular income tax, that's nearly another 15% of your profit going straight to the IRS before you've even thought about deductions. The employer-equivalent half of that — 7.65% — is deductible on Schedule 1, which you file with Form 1040. File it. People forget this line every single year.
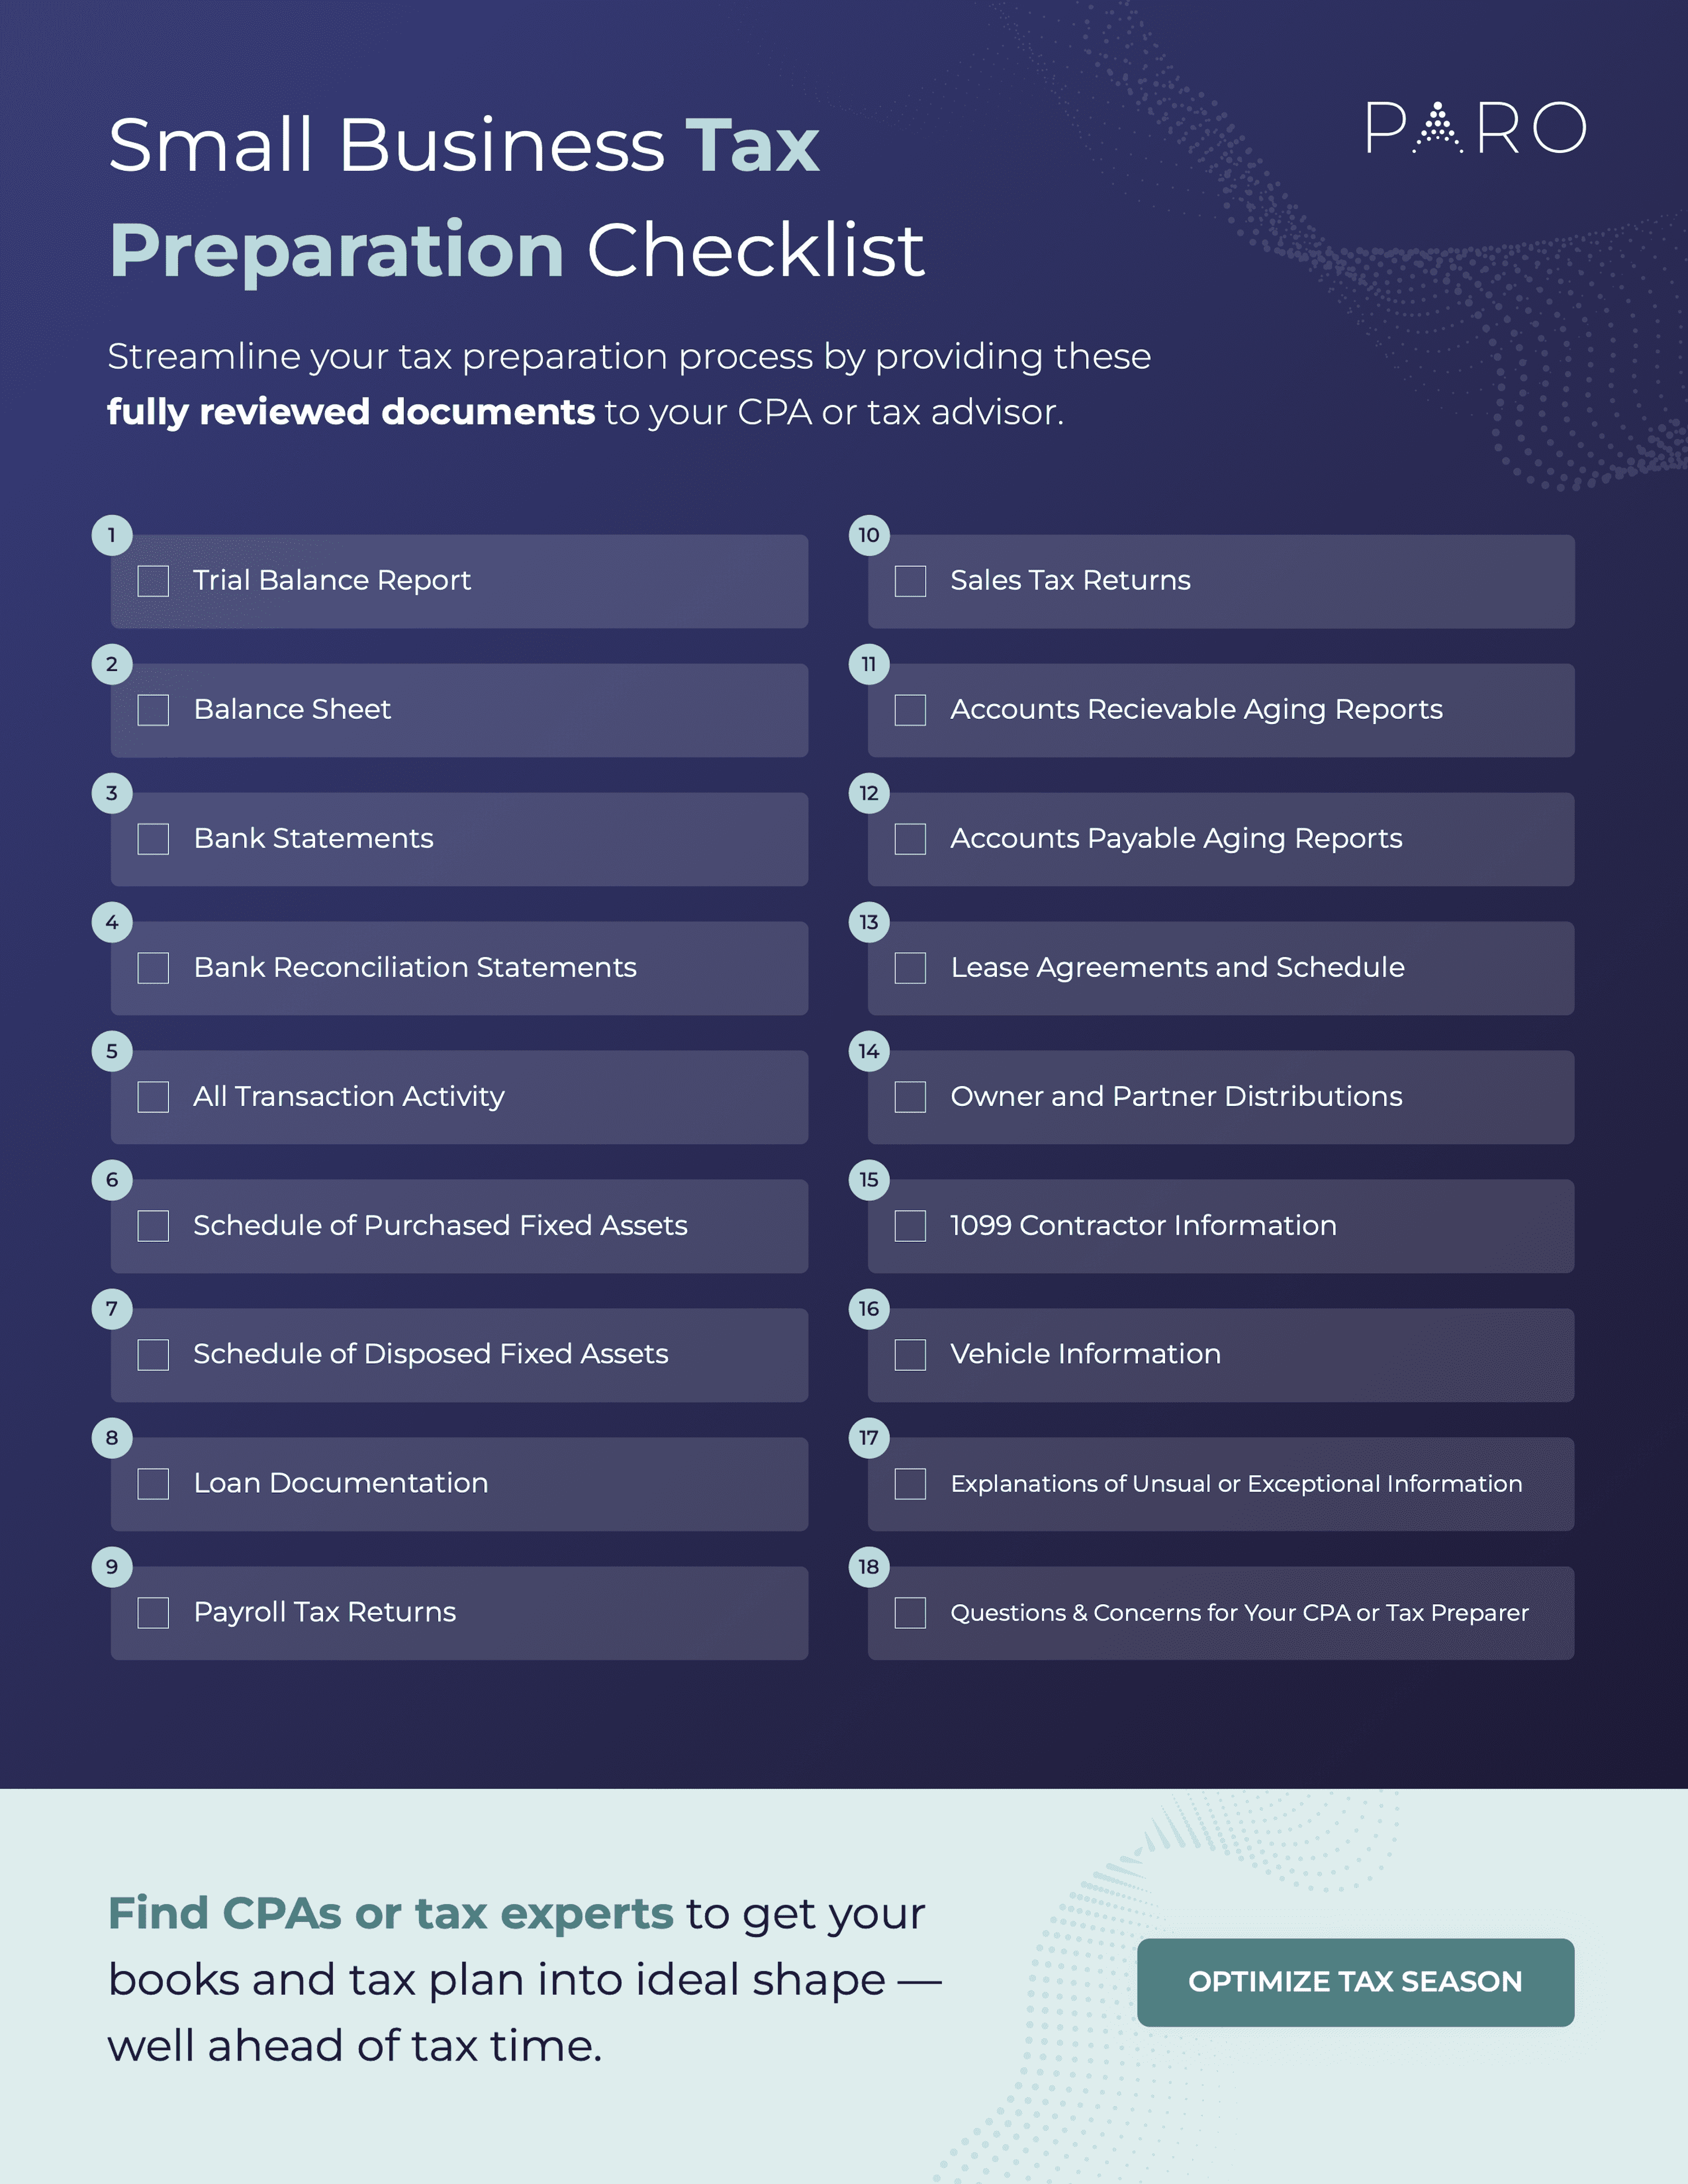
I had a specific problem last year that took me three weeks to sort out. A client had been using a third-party scheduling platform for their consulting business, and those payouts were net amounts — they'd withhold their own fees before depositing. I was reconciling the bank feed and the numbers never matched. Every transaction from that platform showed up as income but at a reduced amount. I thought I had a classification error, then I thought the account was compromised, then I considered whether I was missing a whole chunk of revenue somewhere. It turned out the platform deposits are gross income less the platform fee, and the fee itself is a separate business expense. QuickBooks wasn't set up to handle it. I created a clearing account, mapped all the incoming deposits to it as a 100% amount (the gross fee before the platform took its cut), and then recorded the platform fee as an expense. The bank reconciliation finally balanced. This should have been obvious but it wasn't, and if you work with any marketplace or platform-based revenue, this setup saves you from a reconciliation nightmare at tax time.What to Track All Year (Not Just Before You Hire Someone)
Mileage logs. I know they're annoying. But if you drive your car for business — and by business I mean client meetings, site visits, supply runs, anything that isn't your daily commute — you can deduct either the standard mileage rate or actual expenses. The standard rate for 2024 is 67 cents per mile. If you drive 15,000 miles a year for work, that's over $10,000 in deductions. People let that fall off their radar and lose thousands. I use Everlapse on my phone and it logs everything automatically. Takes about ten seconds to start and stop. That's it. Home office deduction. You qualify if you use a portion of your home exclusively and regularly for business. Exclusive use means a desk in your garage works. A corner of your living room where you answer emails doesn't, unless you can demonstrate it's used only for work. The simplified method lets you deduct $5 per square foot, up to 300 square feet, so that's a max of $1,500 without any depreciation calculations. The regular method requires actual expense allocation but lets you claim more and handle depreciation. Most sole proprietors under $50,000 in revenue benefit more from the simplified method because it's less paperwork and the numbers are usually similar anyway. Possibly the biggest misunderstanding I see: the health insurance deduction. If you're a sole proprietor or partner, you can deduct 100% of your health insurance premiums on Schedule 1. This is above the line — it reduces your adjusted gross income directly, which also lowers your taxable income for purposes of other deductions. Your spouse's premium counts if you file jointly. But you can't take this deduction if you're eligible to participate in a health plan through your spouse's employer, even if you don't actually enroll. The IRS sees eligibility, not participation. That distinction matters and it catches people off guard.
Get the Full Details

When You Need a Professional vs. When You Don't
There's no universal answer, but here's the rule I give myself: if you're a sole proprietor with under $100,000 in revenue, one business bank account, and no employees, you can handle this yourself with TurboTax Self-Employed or a similar product. I've done my own taxes this way for twelve years and I've never had an issue. If you have a partnership, S-corp election, multiple revenue streams, or employees, hire someone. The cost of an error outweighs the $500 to $1,500 you'd pay for a competent preparer. A competent preparer is not the same as a cheap preparer. I once watched a CPA try to file a client's Schedule C from three years prior because the client had lost their records. The form was wrong. The income was understated. The penalties and interest from the IRS audit far exceeded what the CPA would have charged to do it right the first time. Get references. Check your state board's website for disciplinary actions. A cheap preparer who makes a mistake costs you more in the long run than an expensive one who gets it right.
The One Thing That Actually Matters
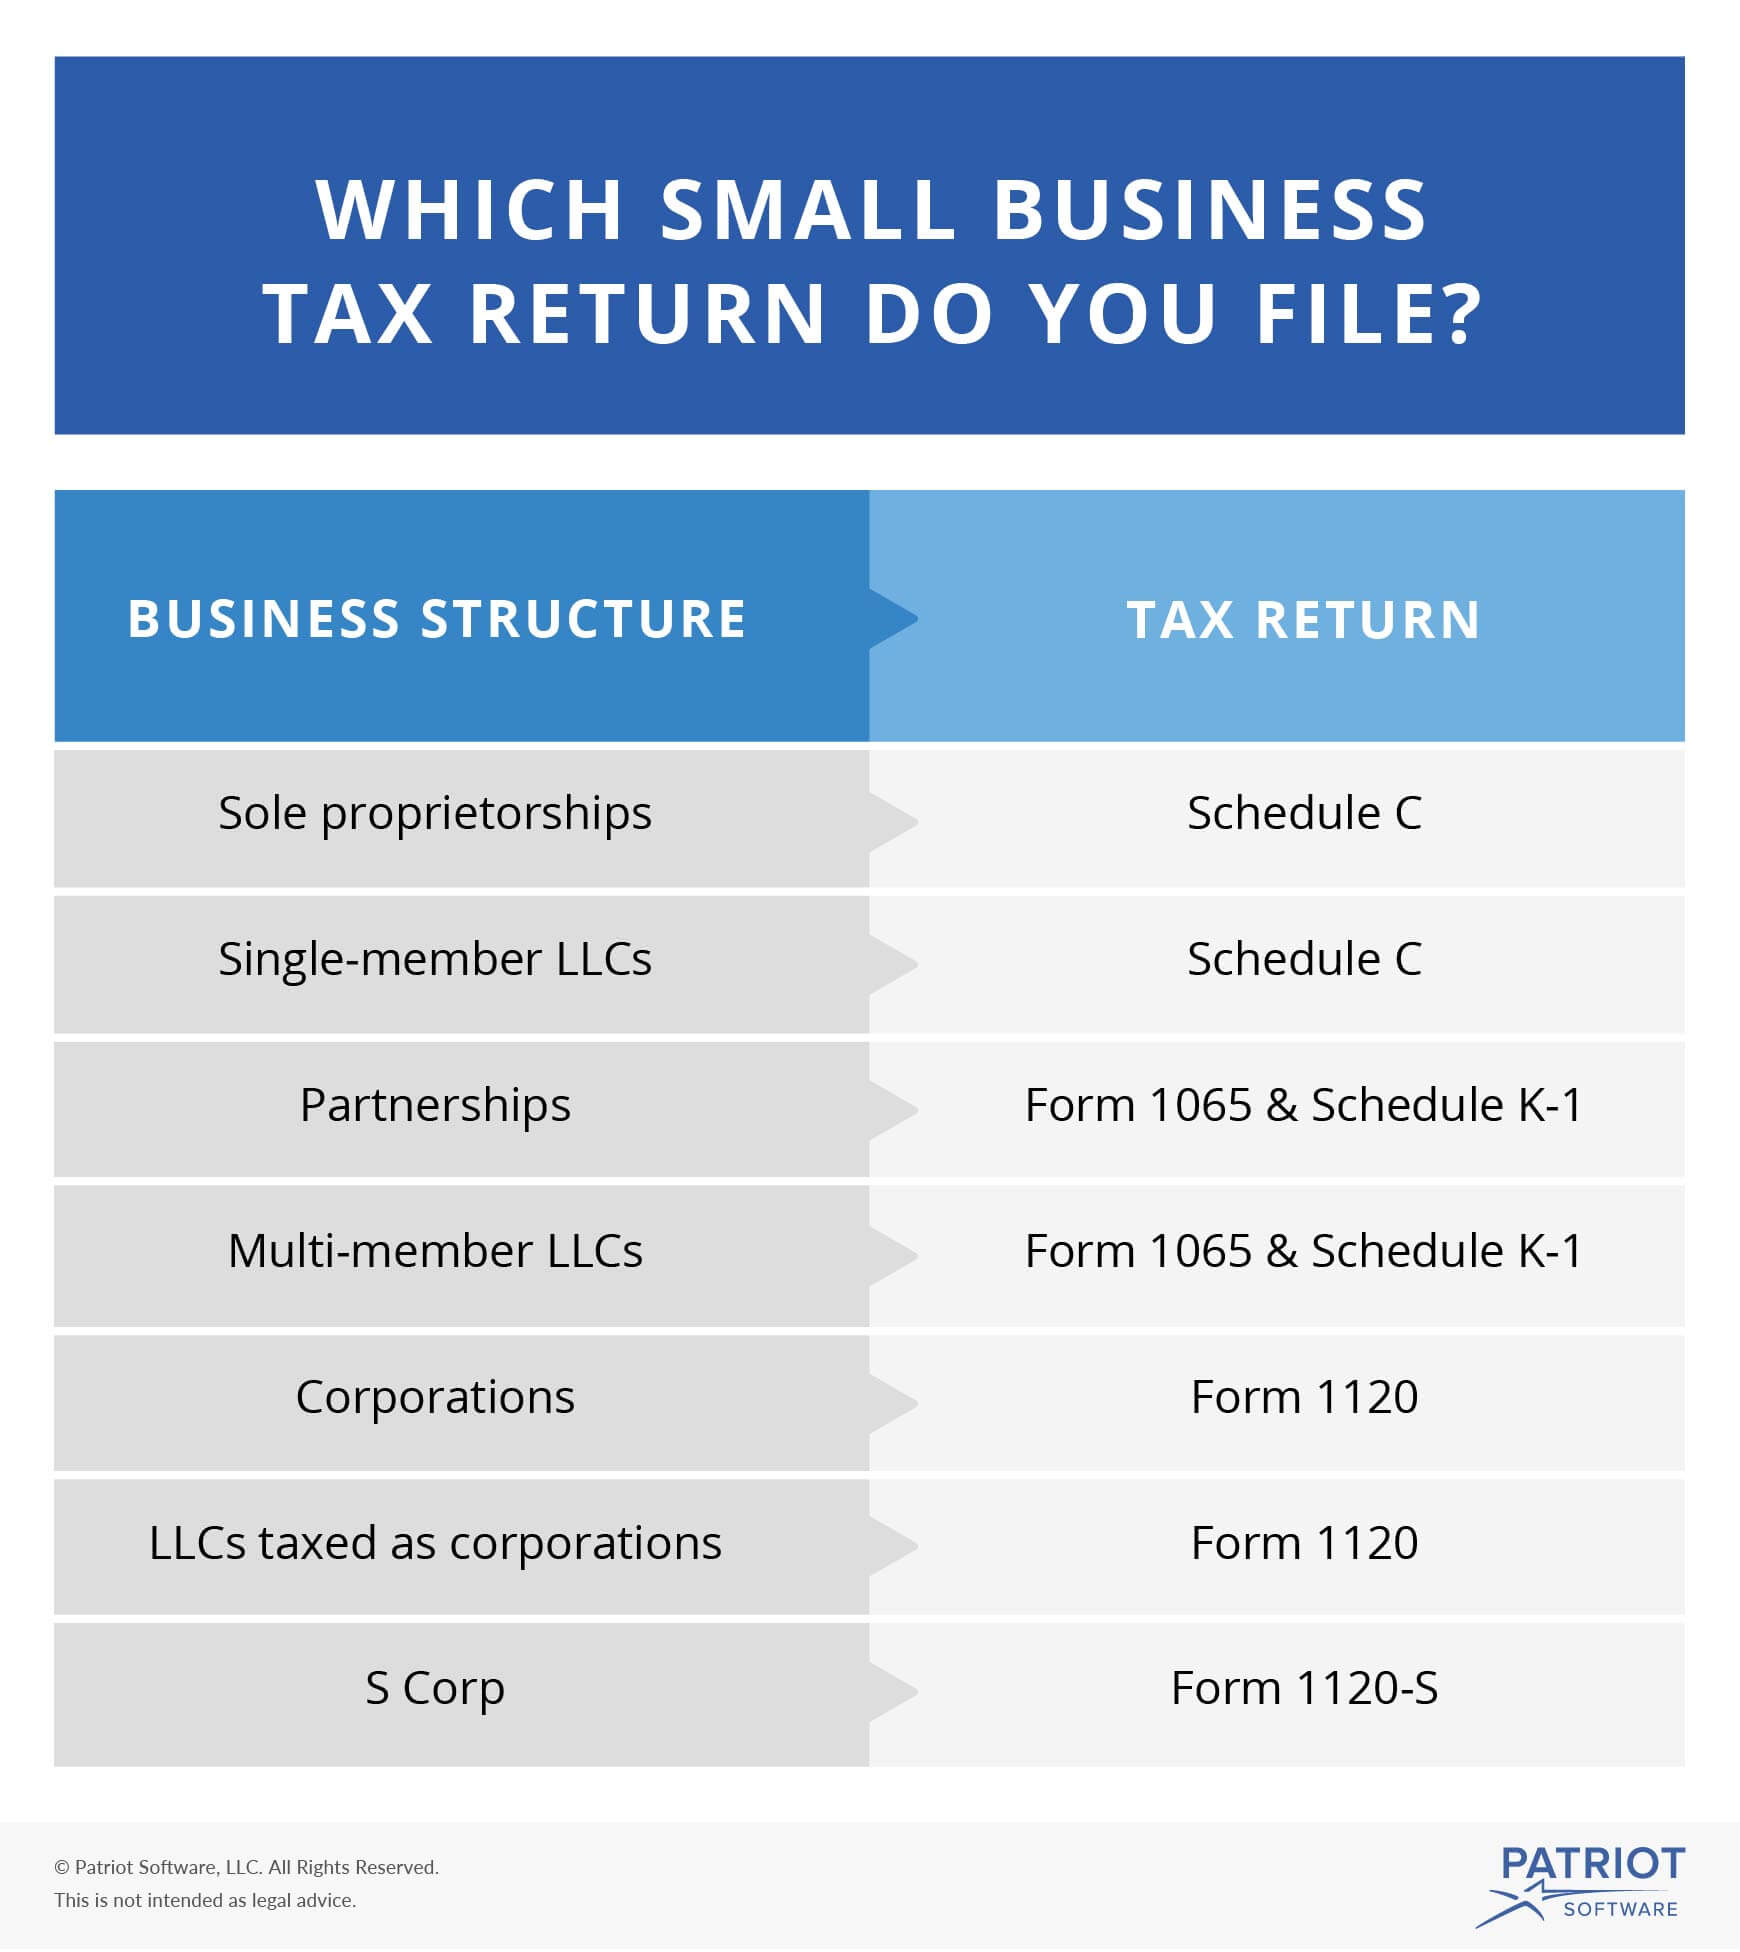
Consistency. Everything I've described here is noise if you're not doing it regularly. The difference between a smooth tax season and a two-week panic spiral is whether you reviewed your books in the last thirty days. Not sixty. Thirty. If you haven't looked at your expense categories since March, you're about to find out why that matters. Schedule 1, Form 1040, Form 1065, Form 1120-S — these forms exist for reasons. Each one applies to different business structures. Sole proprietorship: Schedule C with your 1040. Partnership: Form 1065 plus a K-1 for each partner. S-corporation: Form 1120-S plus K-1s. Don't guess which form applies. Pick the right one and file it correctly. The IRS matches K-1 income against your personal return automatically now. Mismatches get flagged in about forty days.