
What Actually Goes Into a Tax Interview
A standard tax preparation interview isn't just asking someone what their W-2 says. You're pulling together income streams, deductions, credits, life events that happened mid-year, and trying to figure out which filing status makes the most sense when the person sitting across from you genuinely doesn't know the difference between itemizing and taking the standard deduction. I've been doing this for long enough that I can spot a mismatched 1099-NEC in about three seconds flat. The core concept behind structured Tax Preparation Interview Questions is that you need a repeatable framework. Without one, you're leaving money on the table either by missing deductions or by asking redundant questions that waste thirty minutes of billable time. The framework does three things: it captures all reportable income, it identifies every potential deduction and credit, and it flags red flags before you even open the software.
Tax Preparation Interview Questions You Actually Need
Here's the list most preparers end up using. It's not fancy, but it works because it was built from mistakes, not from a textbook. Income identification: - All W-2s received this year, including any from side gigs or contract work
- 1099-INT, 1099-DIV, 1099-B, 1099-MISC, 1099-NEC, 1099-R, any 1099-K from payment processors - Social Security or pension income - Rental or royalty income
Get the Full Details
- Unemployment compensation - Any other income that doesn't fit the above buckets Deduction identification:
- Mortgage interest statements (1098) - Property tax payments - Charitable contributions, including non-cash with values over $500
- Medical expenses exceeding 7.5% of AGI - Student loan interest - Education-related expenses

- Business expenses if self-employed or freelancing - HSA, FSA, or health insurance premium payments - Retirement contributions made after the tax year began
Credit and situation check: - Dependent information including SSNs and relationship - Health insurance coverage (Form 1095-A, B, or C)
- Earned Income Credit eligibility - Child Tax Credit and dependent care credit - Any life events: marriage, divorce, death in family, birth, home sale, divorce

I built my original questionnaire about six years ago after losing a client who had a second job that reported income on a 1099 instead of a W-2. They hadn't mentioned it because they considered it "just extra cash." That's still the most common gap I see. People don't consider gig income or small freelance payments as something they need to tell you about.
How to Run the Interview So It Doesn't Take Two Hours
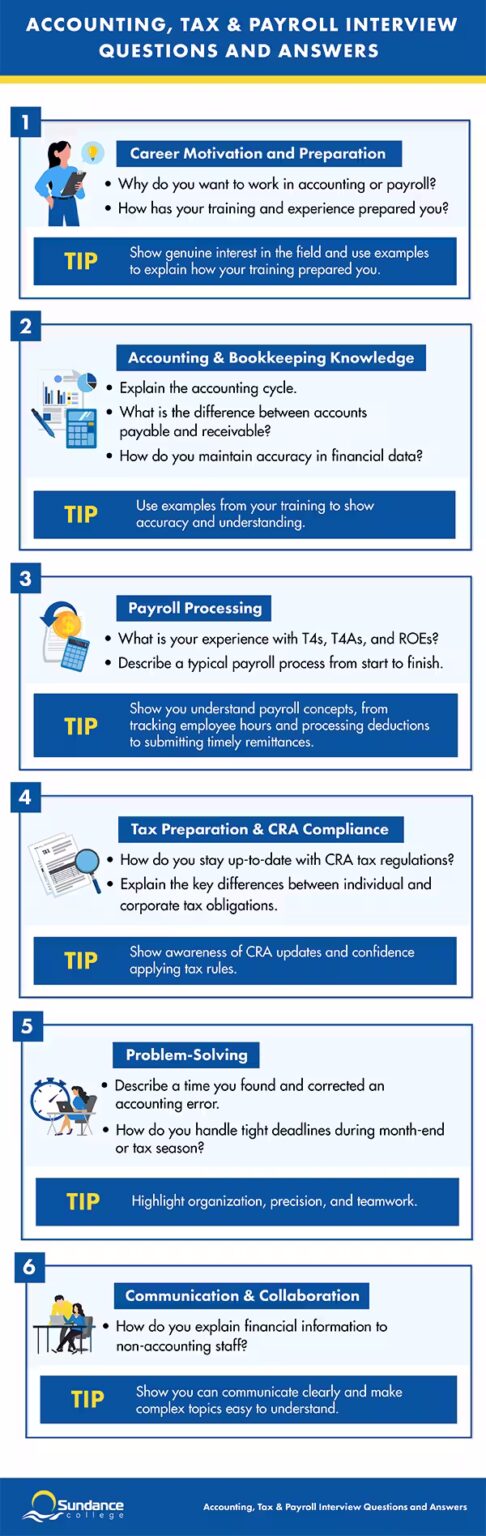
The first version of my questionnaire took me twenty minutes to get through because I was writing everything in a conversational way. "So tell me about your job" and "Did you do any work on the side" are terrible questions. They invite stories instead of data. Switch to direct, specific questions and the whole process compresses from twenty minutes to roughly four for a straightforward return, sometimes less if the client is organized. When I use a written questionnaire ahead of time, clients fill it out before the meeting. I've seen this cut intake time from fifteen minutes down to about two, and more importantly, it surfaces documents early. If someone writes "I have rental income" on the form, I ask for the Schedule E details before we meet. Then when we sit down together, I'm verifying, not discovering. The trick that most people miss is the reverse-check technique. Instead of only asking what happened, ask what didn't happen. "Did anything change this year? No? Okay, did you sell anything? Change jobs? Get married? No? Alright." This catches the edge cases without making the client feel like you're fishing. It usually surfaces one or two items that would have otherwise been missed.
I had a client last year who checked every box as "no changes" on the standard life event section. When I used the reverse-check approach, they mentioned offhand that they'd received a 1099-C from a creditor forgiving part of a personal loan. Not business debt, just a personal one. That triggered taxable income of about eleven thousand dollars and a conversation about whether they should have gotten that form in the first place. We caught it because the standard questionnaire wouldn't have caught it. Another thing worth noting: clients will hand you everything they think is relevant and forget everything else. This is normal. Don't correct them in the moment. Let them dump the papers. Sort through it yourself afterward. Arguing with someone about whether they have the right form is unproductive and eats time you don't have.
Common Mistakes and Where the Method Breaks Down
The biggest limitation of any standardized questionnaire is that it assumes the client understands what they're looking at. They rarely do. A client will hand you a bank statement and say "that's my income" when it's actually a return of capital or a gift. Another will hand you a Form 1099 and not realize it's from the wrong year. The questionnaire is only as good as the documents the client provides, and document accuracy is the weak link in the entire process. Another problem is self-employed clients with messy records. The standard questionnaire works okay for wage earners. For someone who runs a side business out of their house, you need a separate flow that covers business classification, expense categorization, depreciation schedules, and whether they should have been issuing 1099s to their own contractors. I keep a supplementary questionnaire just for this group, and even then, the process takes longer because the variables multiply fast. Here's a counter-intuitive point: asking for more information upfront doesn't always help. In my experience, giving a client a fifty-question form before they've ever worked with a preparer makes them anxious and either fill it out incorrectly or not at all. I switched to a shorter initial form with about fifteen core questions and a promise to dig deeper during the meeting. Conversion rates for completed forms went up, and the quality of information improved because people weren't guessing at answers to questions they didn't understand.
Also worth mentioning: the questionnaire approach assumes you're working with individual tax returns. For complex situations involving trusts, estates, partnerships, or multi-state filings, the standard Tax Preparation Interview Questions list becomes insufficient and you need specialized questionnaires for each entity type. There's no shortcut around that.
Building Your Own Version
If you're putting together your own set of Tax Preparation Interview Questions, start with the IRS lookup tool and the 1040 instructions rather than copying someone else's form. The IRS website has a clear breakdown of what triggers what on the return, and mapping your questions directly to line items means less rework when you're actually inputting the data. I've spent countless hours converting interview answers into return fields, and having the questions aligned to the form lines from the start saves maybe ten to fifteen minutes per return on average. Keep it modular. Separate the income section from the deduction section from the credit section. You can skip sections based on the client's situation without creating an entirely new form. I have a master template with about forty questions and a subset view for simple returns that shows roughly twenty. This cuts intimidation for straightforward clients while keeping the full version available for complex cases. Update it once a year when the tax code changes. Last year that meant adding questions about the new student loan forgiveness reporting rules and the expanded child tax credit provisions. Missing an update is how you get a return wrong, and fixing it after filing is worse than updating the form beforehand.
I also keep a running log of questions that came up during the year but weren't in the form. Every time I spot a gap, I add it. This is how the form evolved from a basic template into something that actually works. The version I use now took about four years to get to where it is, and it still changes slightly every cycle.
What Works Better When the Questionnaire Isn't Enough
When a client's situation is complicated enough that the standard questions miss something, switching to document-first intake is usually faster. Ask them to gather everything and send it through a secure portal before scheduling. Sort through it yourself, then ask targeted follow-up questions based on what you find. This reverses the traditional flow and tends to be more efficient for complex returns because you're directing the conversation instead of hoping the client remembers to mention something. For recurring clients, maintaining a permanent file with prior-year information eliminates most of the repetitive questions. You only need to ask about changes, not recapture everything every year. This cuts interview time significantly and reduces the chance of missing a new issue because the client assumed you already knew. The bottom line is that a good questionnaire is a starting point, not a complete solution. It catches the obvious stuff and flags the routine items so you can focus your attention where it actually matters. That's about it.
