How I Actually Use a Tax Preparation Worksheet Without Losing My Mind
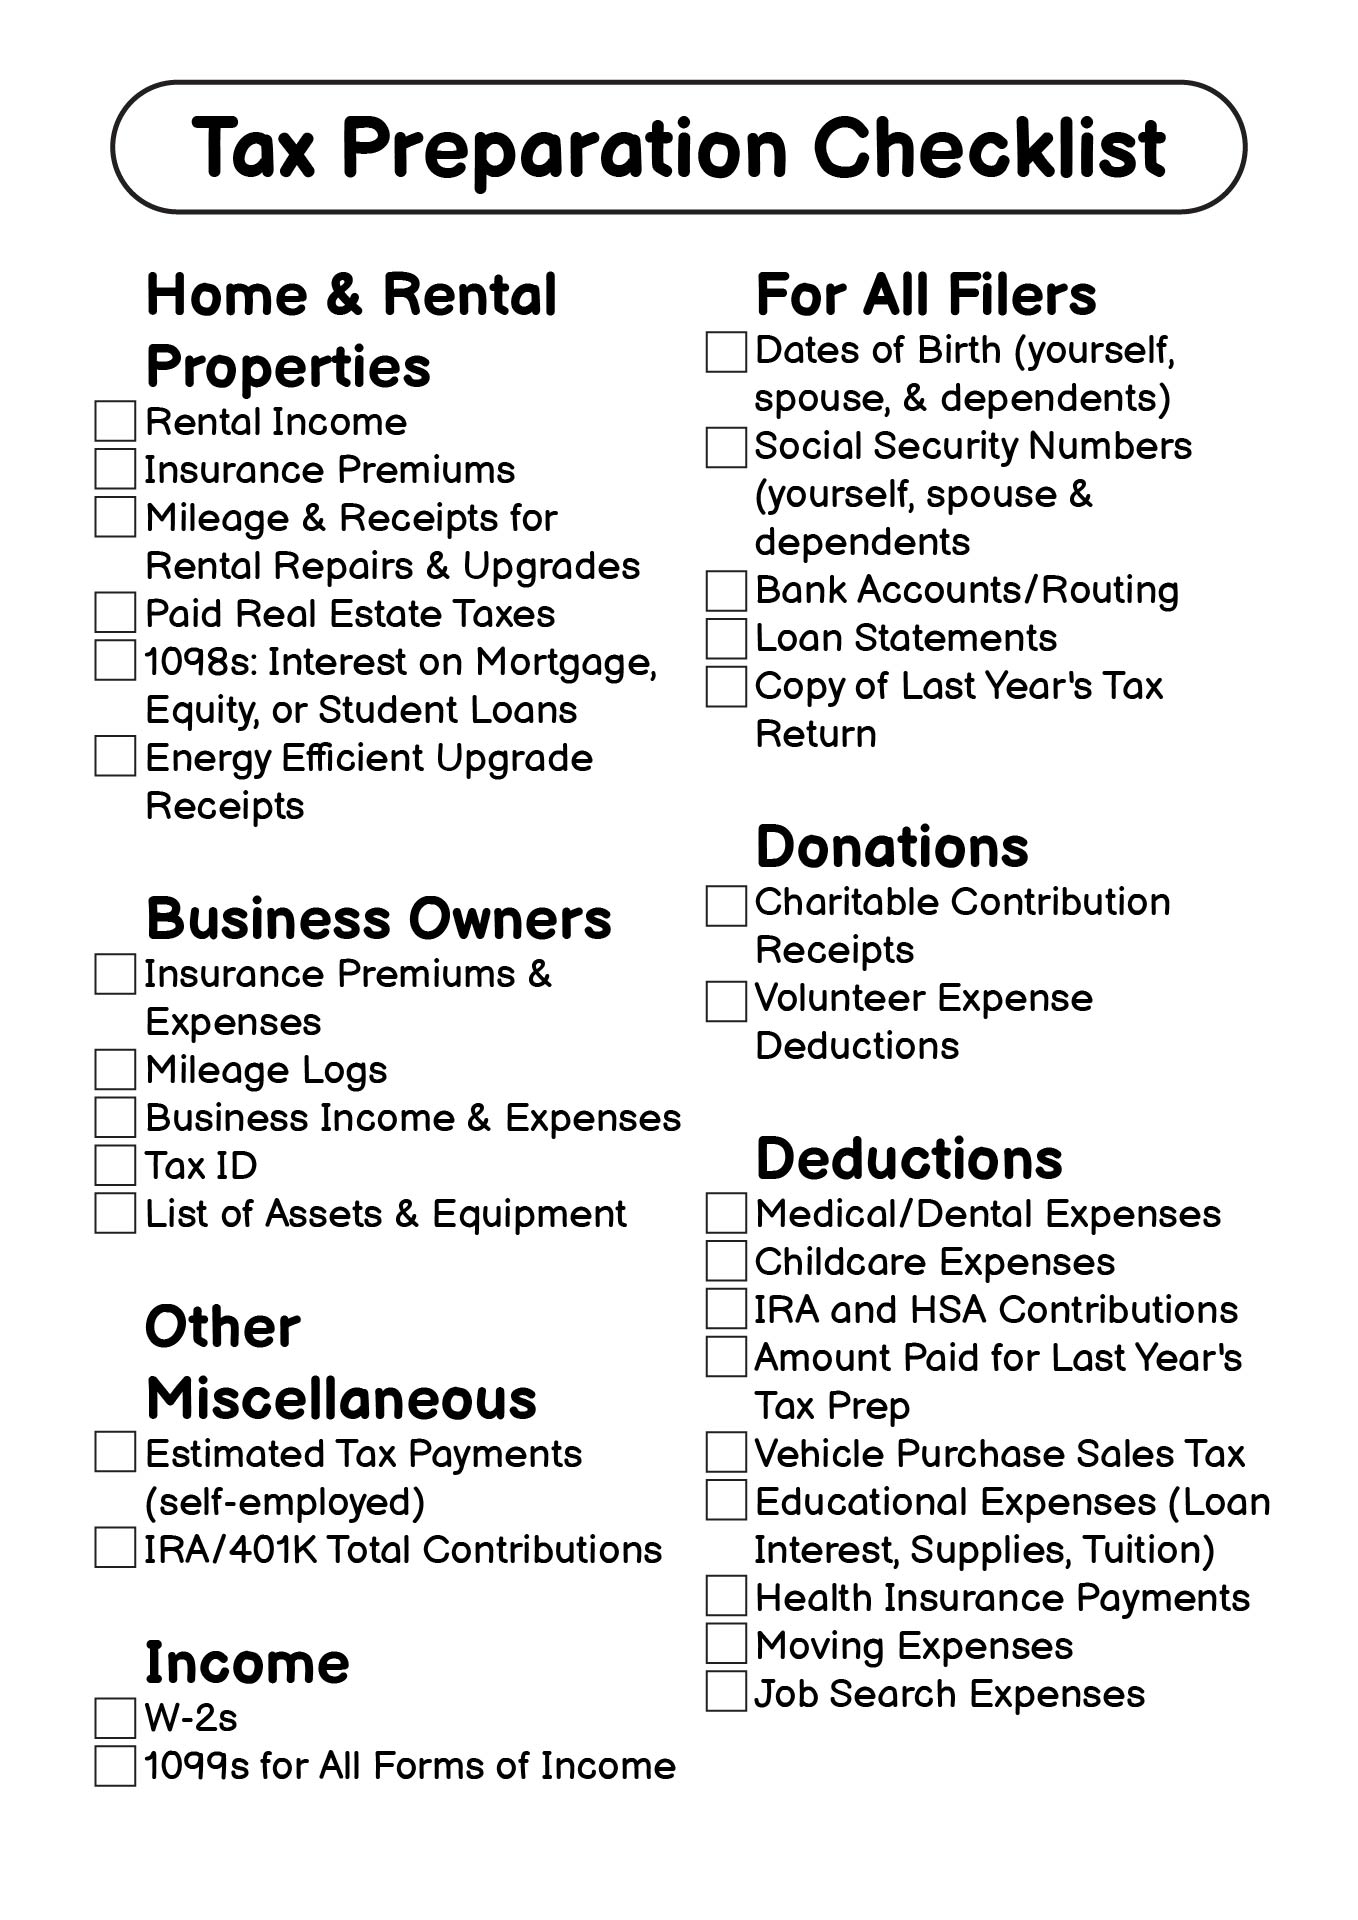
I spent years doing taxes by hand before anything like TurboTax was even a whisper. A blank 1040 on your kitchen table at 11 PM in April is not how anyone wants to start their evening. That was the original motivation for building something structured around the form itself. Now I still use a Tax Preparation Worksheet, though my version looks nothing like what the IRS publishes. The principles are the same, but the execution is where things fall apart for most people. Here's how it works in practice. You need a single document that mirrors the flow of your actual tax return, not just a list of blanks you fill in randomly. I set mine up with four sections: income, adjustments, deductions, and credits. Each section pulls from source documents—W-2s, 1099s, receipts—so you aren't guessing at numbers months later. When I built my current version, I made sure every line had a source column. That way, if the IRS asks where a number came from, you can point to it instead of spiraling.
Setting Up a Tax Preparation Worksheet That Actually Holds Up
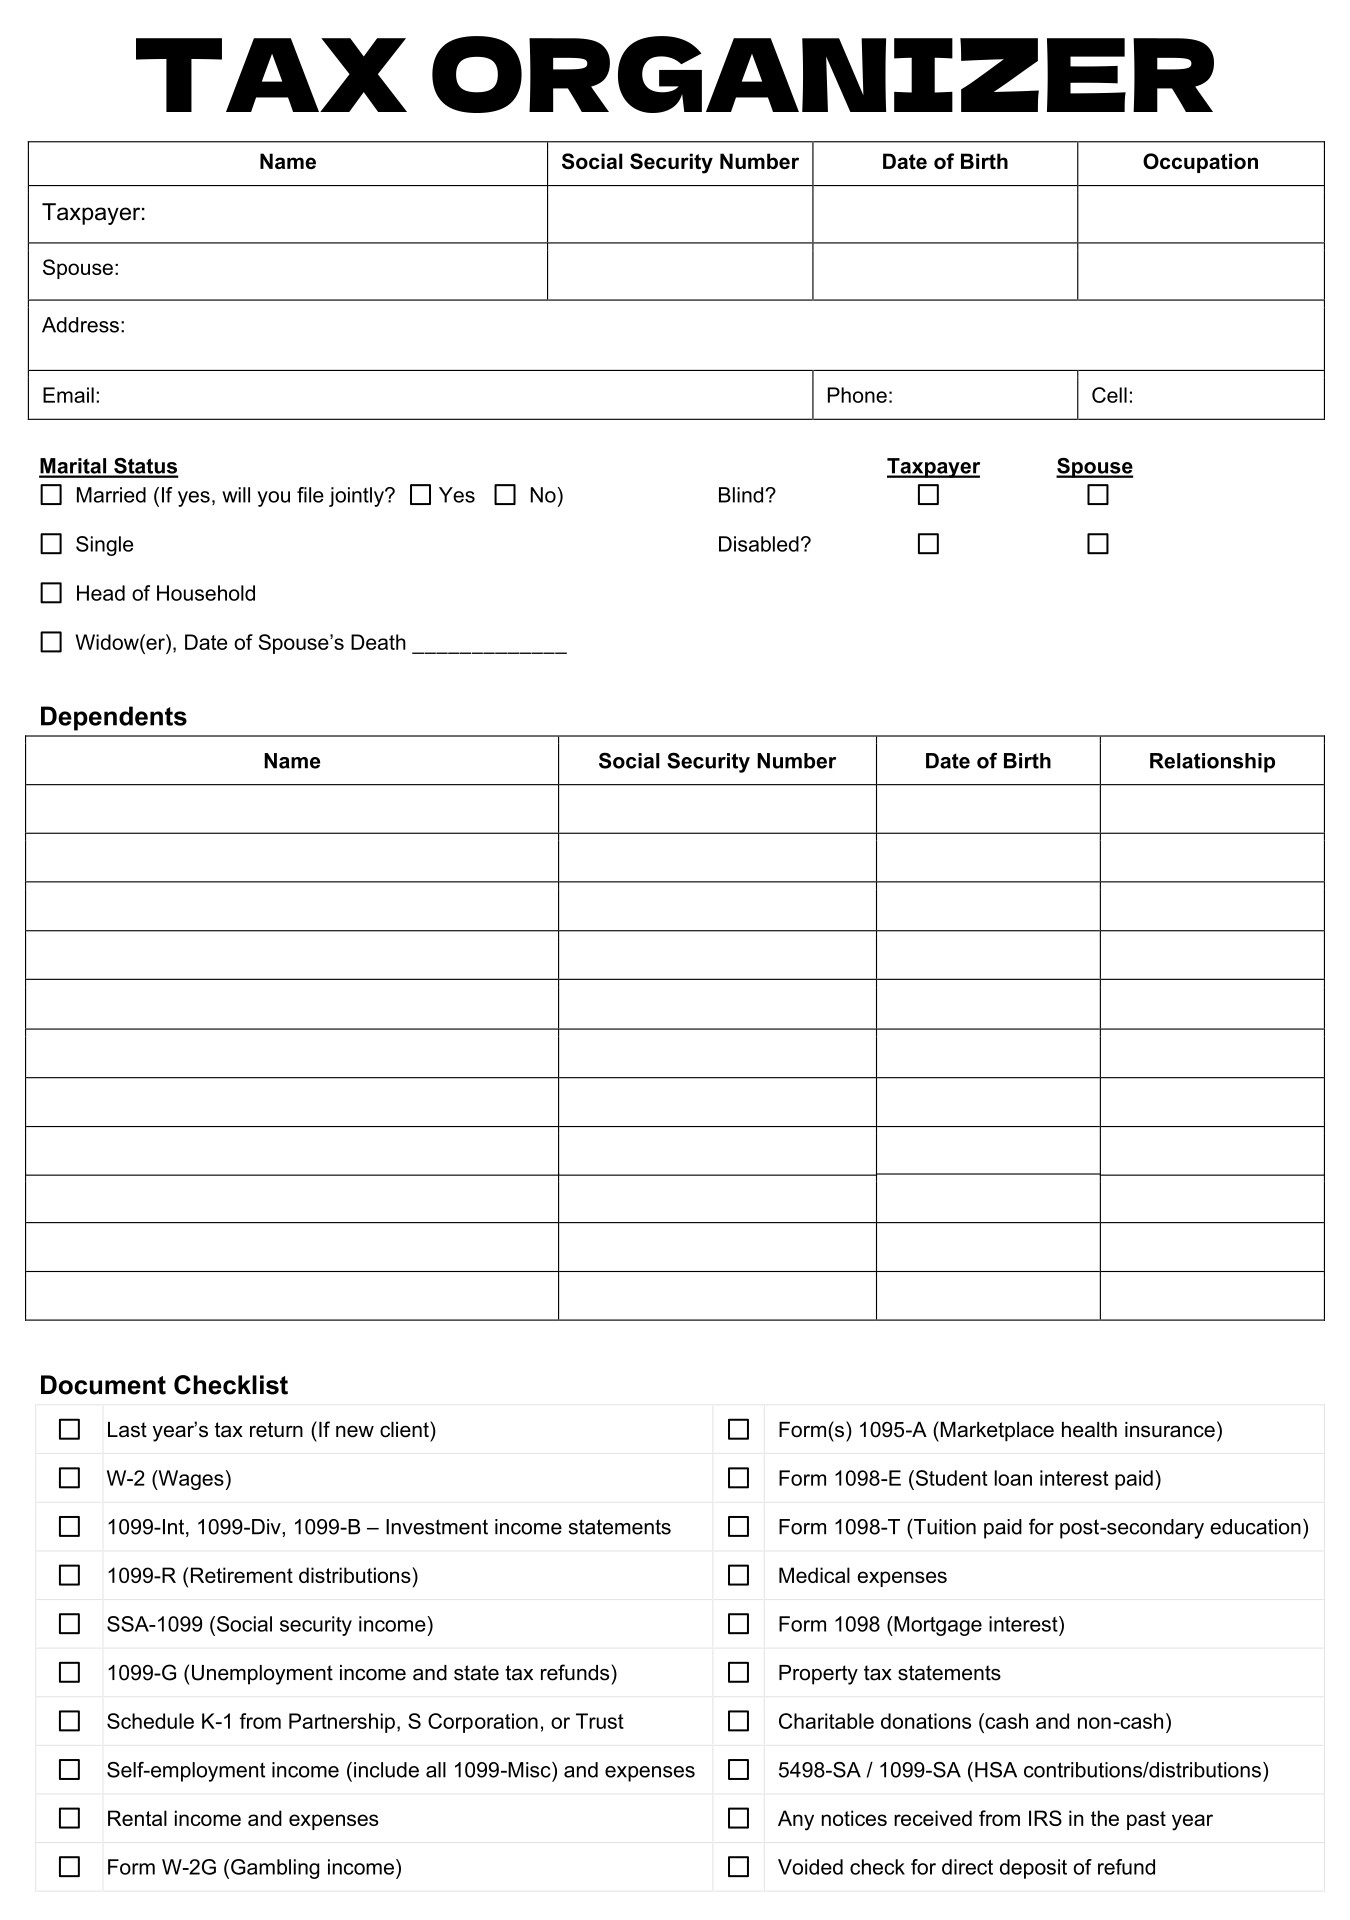
Start with whatever tax year you're dealing with. Most people skip this and jump straight into filling boxes, which is how mistakes happen. The worksheet needs to track dates, forms, and amounts in a consistent format. I use a spreadsheet for this, but a printed form works fine if you keep it neat. The key is making sure each line on your worksheet maps directly to a line on your actual tax form. When you pull your W-2, enter the exact box numbers. Box 1 for wages, Box 2 for federal withholding, Box 16 for state wages if applicable. Don't round. Don't estimate. If you have multiple W-2s, each one gets its own row. I learned this the hard way when I combined two W-2s into a single line one year and the math looked right on the surface but was wrong on the backend. The IRS computer caught it. They always catch it. I have not forgotten that letter. 1099s are where most people lose track. 1099-NEC for freelance income, 1099-DIV for dividends, 1099-INT for interest, 1099-B for broker transactions. Each type flows to a different part of your return. The worksheet should flag which form goes where before you even look at the final numbers. I put a category column next to each form type so I know instantly whether something is ordinary income, capital gains, or something that requires a schedule.
The Parts Nobody Talks About Until It Breaks
Most worksheets I see online stop at the basics. They tell you to add up your income and subtract your deductions. That's technically correct and practically useless because the actual tax calculation happens in the spaces between those numbers. Let me explain what I mean by walking through something specific. Self-employment tax is one of those things that looks simple until you sit down to compute it. You take your net earnings from Schedule C, multiply by 92.35%, then apply the 15.3% rate. But here's the thing most people miss: you can deduct half of that self-employment tax on your Form 1040. The worksheet needs to show both calculations side by side so you don't forget the deduction later. I used to forget it. I kept writing it off in my head and then realizing I hadn't actually entered it. Now my worksheet has a dedicated section that calculates the tax and the deduction in the same cell block. It takes five seconds instead of causing a panic three weeks later. Credits are another area where worksheets routinely fail. The Earned Income Credit has income thresholds that change every year. The Child Tax Credit has age requirements and refundability rules that depend on your filing status. A proper worksheet doesn't just list these credits—it walks you through the qualification check before you claim them. I built that into my system after a friend of mine claimed the full credit for a child who had aged out the year before. He got a notice in the mail. It was not fun.
Get the Full Details
Capital losses deserve special attention. You can deduct up to $3,000 in net capital losses against ordinary income per year. Anything above that carries forward. Most worksheets don't account for this carryforward at all. You need a separate tracking section that records your excess losses and applies them year over year. I track mine in a running column that updates each year. When I sold stock at a loss last year, I knew immediately that $2,100 would carry forward to this year instead of wondering if I'd already used it up.
A Problem I Ran Into and How I Fixed It
About three years ago, I hit a wall with my worksheet when dealing with rental income and depreciation. I had a property where I'd taken cost segregation in a prior year, which meant I had accelerated depreciation kicking in on the current year's return. The standard worksheet format didn't have a place to track accumulated depreciation versus current-year depreciation. I ended up mixing up the numbers and underreported my income by a significant amount. The fix was adding a depreciation schedule section that tracks three numbers per asset: original basis, accumulated depreciation, and current-year depreciation. You also need a column for the depreciation method and the remaining life. This took my worksheet from something that handled simple income and deductions to something that could handle actual complexity. It added maybe ten lines to the form but eliminated an entire category of errors. I've used the same structure ever since, adjusting it only when a new situation comes up that the existing sections can't handle.
Where This Approach Falls Apart
A Tax Preparation Worksheet is not a magic bullet. It will not replace professional help if your situation involves international income, pass-through entities with multiple schedules, or anything that requires interpretation of ambiguous tax code sections. It will also not save you if you are chronically disorganized. The worksheet only works if you actually fill it out as income comes in, not all at once in March when you're digging through shoeboxes of paper. There's also a hard limit to what a manual worksheet can do with things like AMT calculations or the Net Investment Income Tax. These require cross-referencing multiple forms and doing calculations that are easy to mess up by hand. If you're dealing with those, the worksheet is a starting point, not a destination. You should be using software or a CPA at that stage. The worksheet helps you understand what the software is doing, but it won't do the work for you. Another limitation is that tax law changes every year. A worksheet you built last year may not account for new provisions this year. I spend about two hours each January reviewing any changes and updating my template. Skipping that step means you're filing based on outdated assumptions. I've seen people do this and come back with surprise balances owed because a deduction they relied on was modified or eliminated.
What to Do Instead When Your Situation Gets Complicated
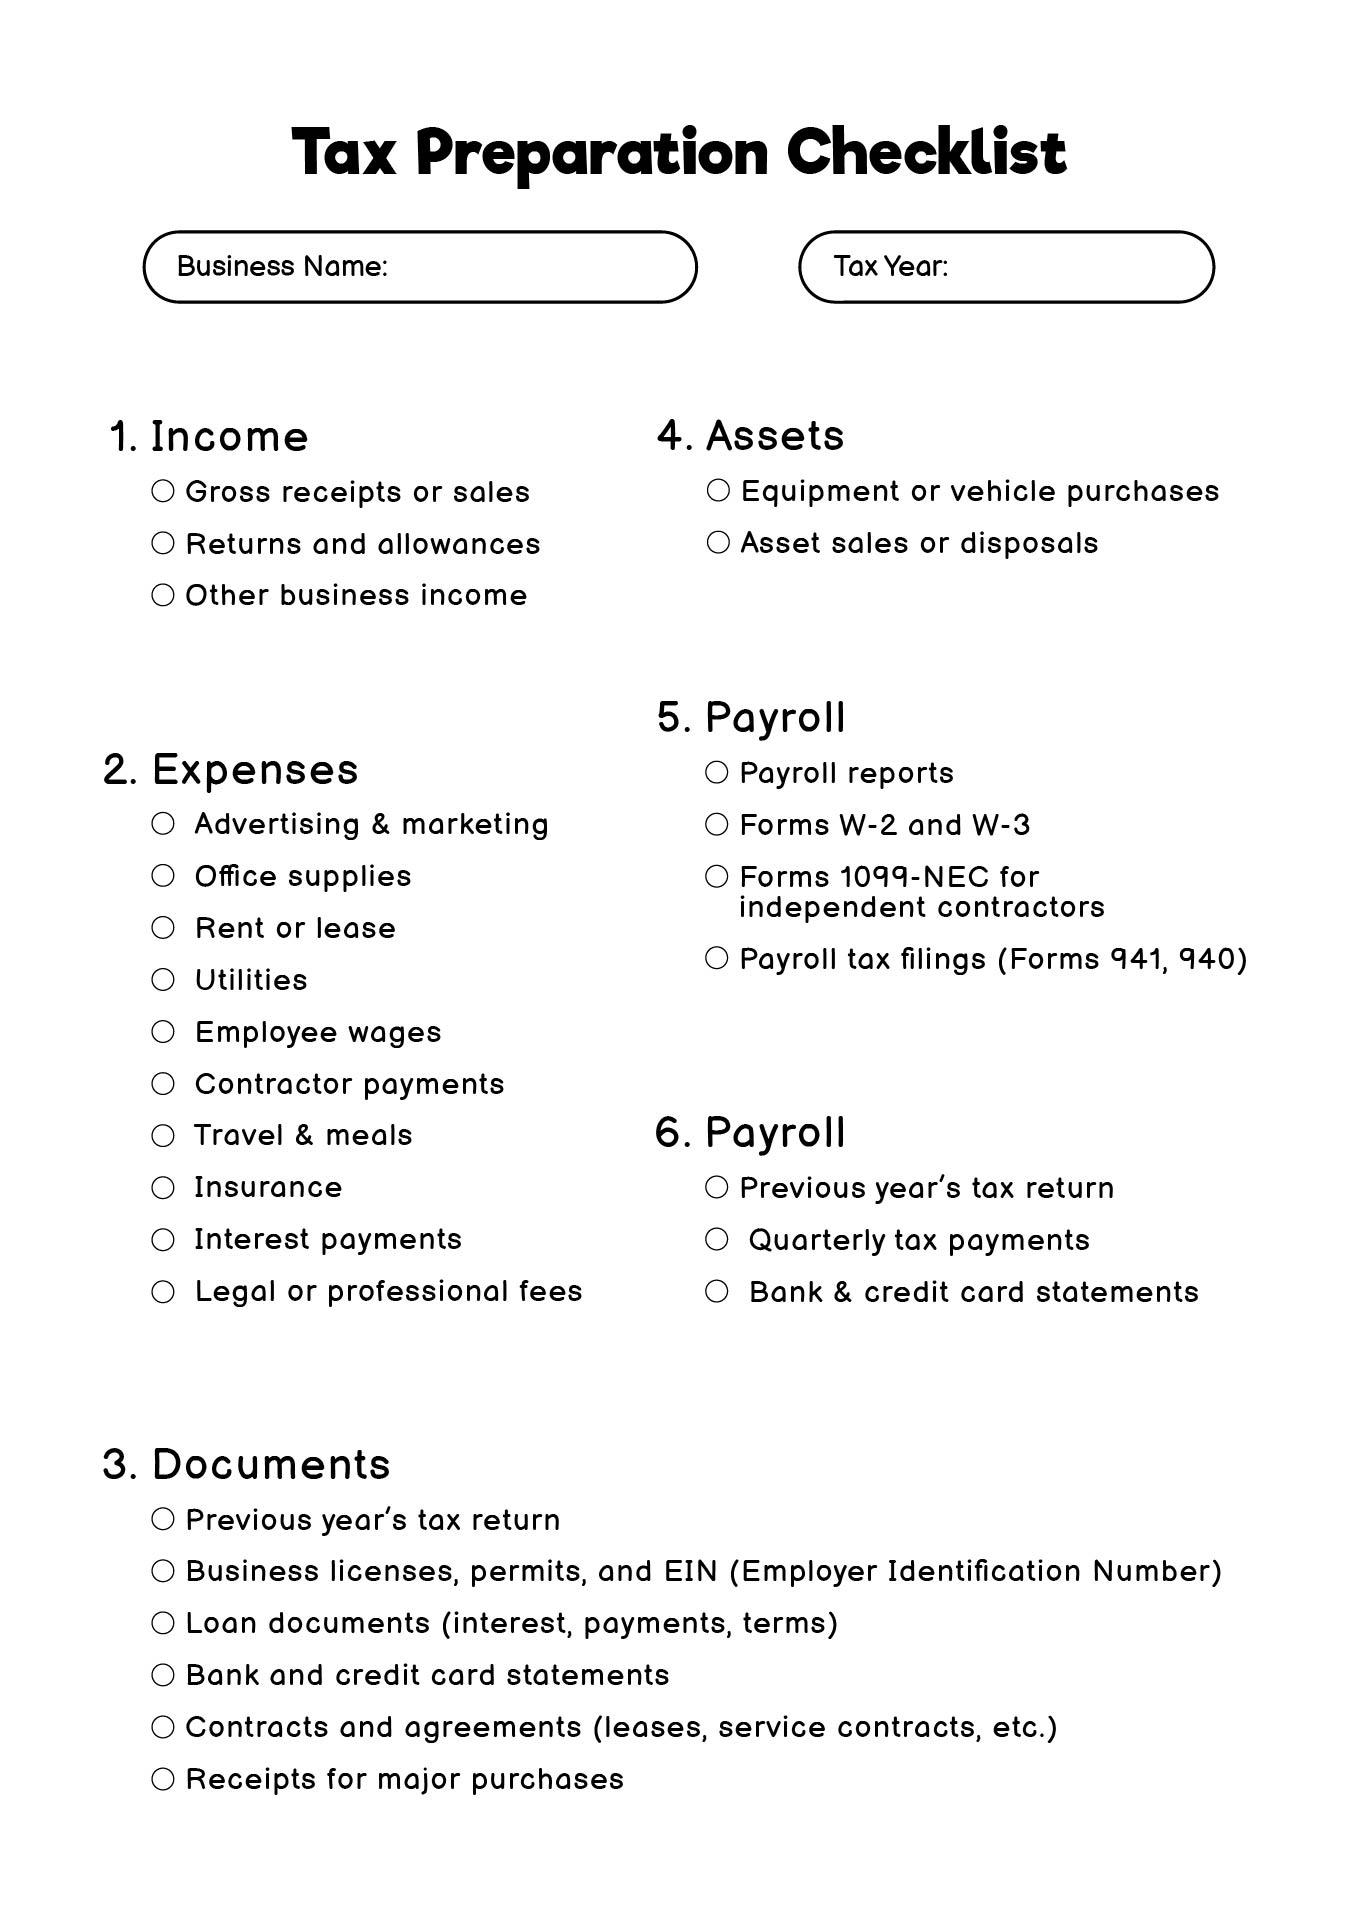
If your income comes from more than one source, if you have dependents, or if you've ever bought or sold anything significant, a worksheet is still worth using as a planning tool. But pair it with tax software for the actual filing. The software catches computational errors that a human will inevitably make. Use the worksheet to organize your data, then export or manually enter it into the software. This gives you the best of both approaches: the clarity of having everything laid out and the safety net of automated calculations. If you're earning self-employment income over $400 a year, a worksheet alone will not protect you. The quarterly estimated tax payments are a separate beast that most worksheets ignore entirely. You need to factor those in or you'll face underpayment penalties that are straightforward to avoid but painful to pay. I calculate my estimated taxes on the same worksheet, just in a separate section. It keeps everything in one place and makes it obvious when I'm falling behind. The bottom line is that a Tax Preparation Worksheet is a thinking tool, not a filing tool. It helps you understand what you owe before you owe it. It surfaces problems you wouldn't otherwise see. But it has limits, and knowing those limits is what separates people who use it well from people who trust it too much. If you're going to use one, build it to match your actual situation, update it every year, and don't pretend it does more than it actually does.