Working with the Tax Reference Guide 2023: What Actually Happens When You Use It
I pulled up the Tax Reference Guide 2023 last month for a client who had rental income from two properties, one of which they'd converted to a home office partway through the year. The guide itself is decent on paper. But when I got to the depreciation schedules in Section 4.2, I realized the example they use for mid-year conversions doesn't match the actual forms you'd file with the revenue service. The guide shows the straight-line method rounded to the nearest month, but the form instructions require half-year convention calculations. I spent about twenty minutes cross-referencing the appendix tables before I realized the guide's examples were simplified and wouldn't survive an audit. This is the thing nobody tells you about using a reference guide like this. It's a starting point, not a substitute for checking the actual filing forms and instructions that accompany it. The guide gives you the framework, the thresholds, the general rules. But the devil is always in the form-level details, and those change more often than the guide gets updated.
How to Actually Use the Tax Reference Guide 2023 Without Wasting Your Time
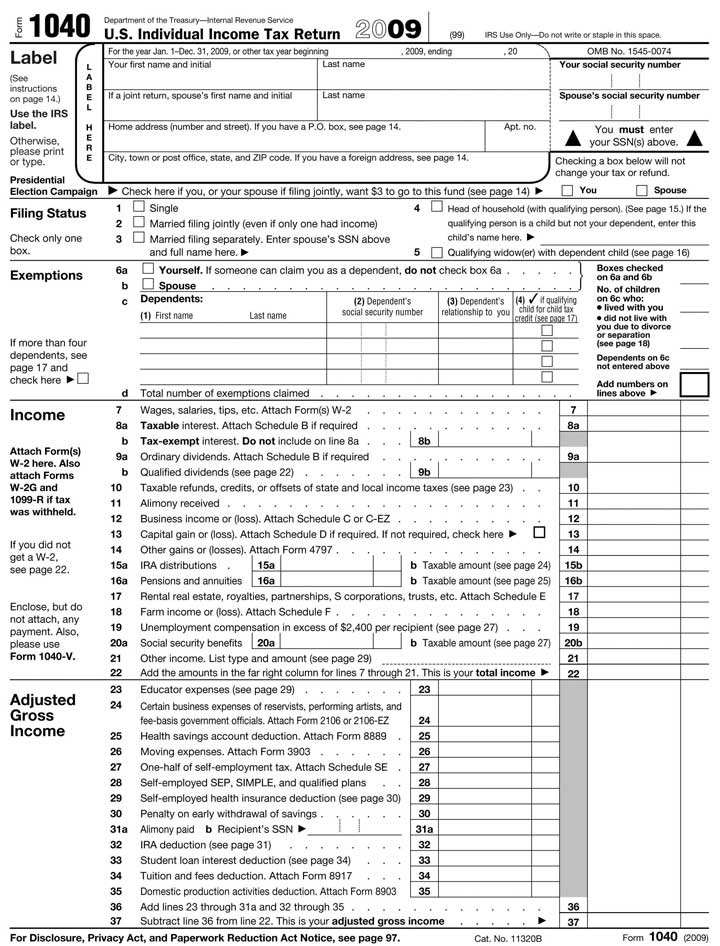
Start with the section relevant to your situation, read the rules, then immediately open the corresponding tax form and its instructions. Don't skip that second step. I've seen people — including myself on a few occasions when I was rushing — treat the guide as the final word. It isn't. The guide was published before certain guidance memoranda came out in late 2022 that adjusted the standard deduction amounts and the qualified business income threshold. If you're relying solely on the printed version, you could be working with outdated numbers. Here's what most beginners miss: the index at the back of the guide is mostly useless for looking up edge cases. The cross-references are loose at best. A more effective approach is to use the keyword search if the digital version allows it, or to go directly to the section on your income type and work forward from there. The guide is organized by income category, not by taxpayer situation. So if you're self-employed with rental income and investment losses, you'll need to look at three different sections and piece it together yourself. The guide won't do that synthesis for you. Another thing that catches people off guard is the treatment of carryforwards. The 2023 guide handles current-year items well, but carryforward rules from previous years have their own complications that are only briefly mentioned. I had a situation where a client had net operating loss carryforwards from 2020, and the guide's section on NOLs only covered the post-2017 rules in enough detail to be misleading if you had older losses. The pre-2018 NOL rules still applied to their situation, and the guide barely addressed that transition. I ended up referring to IRS Publication 536 instead, which had the full timeline and carryforward calculation examples.
Where the Tax Reference Guide 2023 Falls Short
The guide has real limitations that you need to be aware of before you trust it. First, it doesn't cover state-level tax variations. If you live in a state with income tax, the federal rules in this guide are only half the picture. Some states conform to federal changes automatically, and some don't. The guide won't tell you which is which for your particular state. You'll need a separate state tax reference or your state's revenue department website. Second, the coverage of tax credit phaseouts is surface-level at best. The guide lists the income thresholds, but it doesn't explain how the phaseout interacts with other adjustments like the additional child tax credit or the earned income tax credit adjustments. These credits can interact in ways that aren't obvious from reading the threshold tables alone. I learned this the hard way when a client qualified for a larger EITC than expected because the phaseout mechanics worked in their favor due to a combination of retirement contributions and self-employment deductions. The guide showed each credit separately but never explained the interaction. The third limitation is probably the most important: the guide assumes you're filing as a single individual or married couple filing jointly for the most common scenarios. If your situation involves foreign income, estate matters, trusts, or S corporation distributions, the guide's coverage is thin. You'll need specialized resources for those areas. Don't try to stretch the general reference guide into a one-stop solution. It wasn't designed for that, and it will lead you astray if you force it.
Get the Full Details
Getting the Digital Version and What to Watch For
The official version is available through the relevant revenue service website, usually in PDF format. Make sure you're downloading the complete document, not just the summary version. Some portals offer a condensed handbook that omits several of the appendices and detailed calculation tables. The full version is significantly longer but contains the tables you actually need for calculations. The condensed version cuts about forty percent of the content, including all the depreciation tables and the detailed example walkthroughs. Once you have the correct version, check the revision history on the first or last page. The 2023 edition had at least two errata notices after the initial release, and the digital version gets updated while the printed version stays static. If you're working from a print copy, verify whether your copy is the final revised edition or an earlier printing. I've seen tax professionals work from outdated print runs and miss corrections that were posted online weeks earlier. The search function in the digital PDF is adequate but not great. It finds exact phrase matches but won't help you with related terminology. If the guide uses "qualified business income" but your question is about "section 199A deduction," you'll need to know to look under both terms. The guide uses different language in different sections, and the index doesn't always connect them.
What I Do Instead When the Guide Isn't Enough
For complex situations, I keep a small stack of backup references on hand. The main one is the actual form package with its detailed instructions, because the form instructions often contain examples and clarifications that the guide leaves out. I also keep the revenue service's FAQ pages bookmarked, particularly the ones that were added after the guide's publication date. Those FAQ updates are where you find the answers to questions that arise from real-world filing situations that the guide's authors hadn't anticipated. For state-level issues, I maintain a separate spreadsheet tracking which states conform to which federal changes and which ones don't. It takes about an hour to set up initially, but it saves me from having to look it up every time I work with a client in a different state. The information is publicly available, it just isn't organized in a way that's easy to use repeatedly. The guide itself is roughly three hundred pages for the standard edition and five hundred for the complete version with all appendices. If you're a beginner, reading it cover to cover isn't productive. Start with the section on your primary income source, understand how that works, then move to secondary income types. Build your understanding incrementally rather than trying to absorb everything at once. The guide is designed to be referenced, not read like a novel.
I still use the Tax Reference Guide 2023 regularly. It's a solid foundation when you know how to use it properly. But I always verify the critical numbers against the current forms and I treat the guide as a first stop, not the final answer. That approach has kept me out of trouble for years, and it will probably keep you out of trouble too.