Building a Tax Revenue Calculator That Actually Works
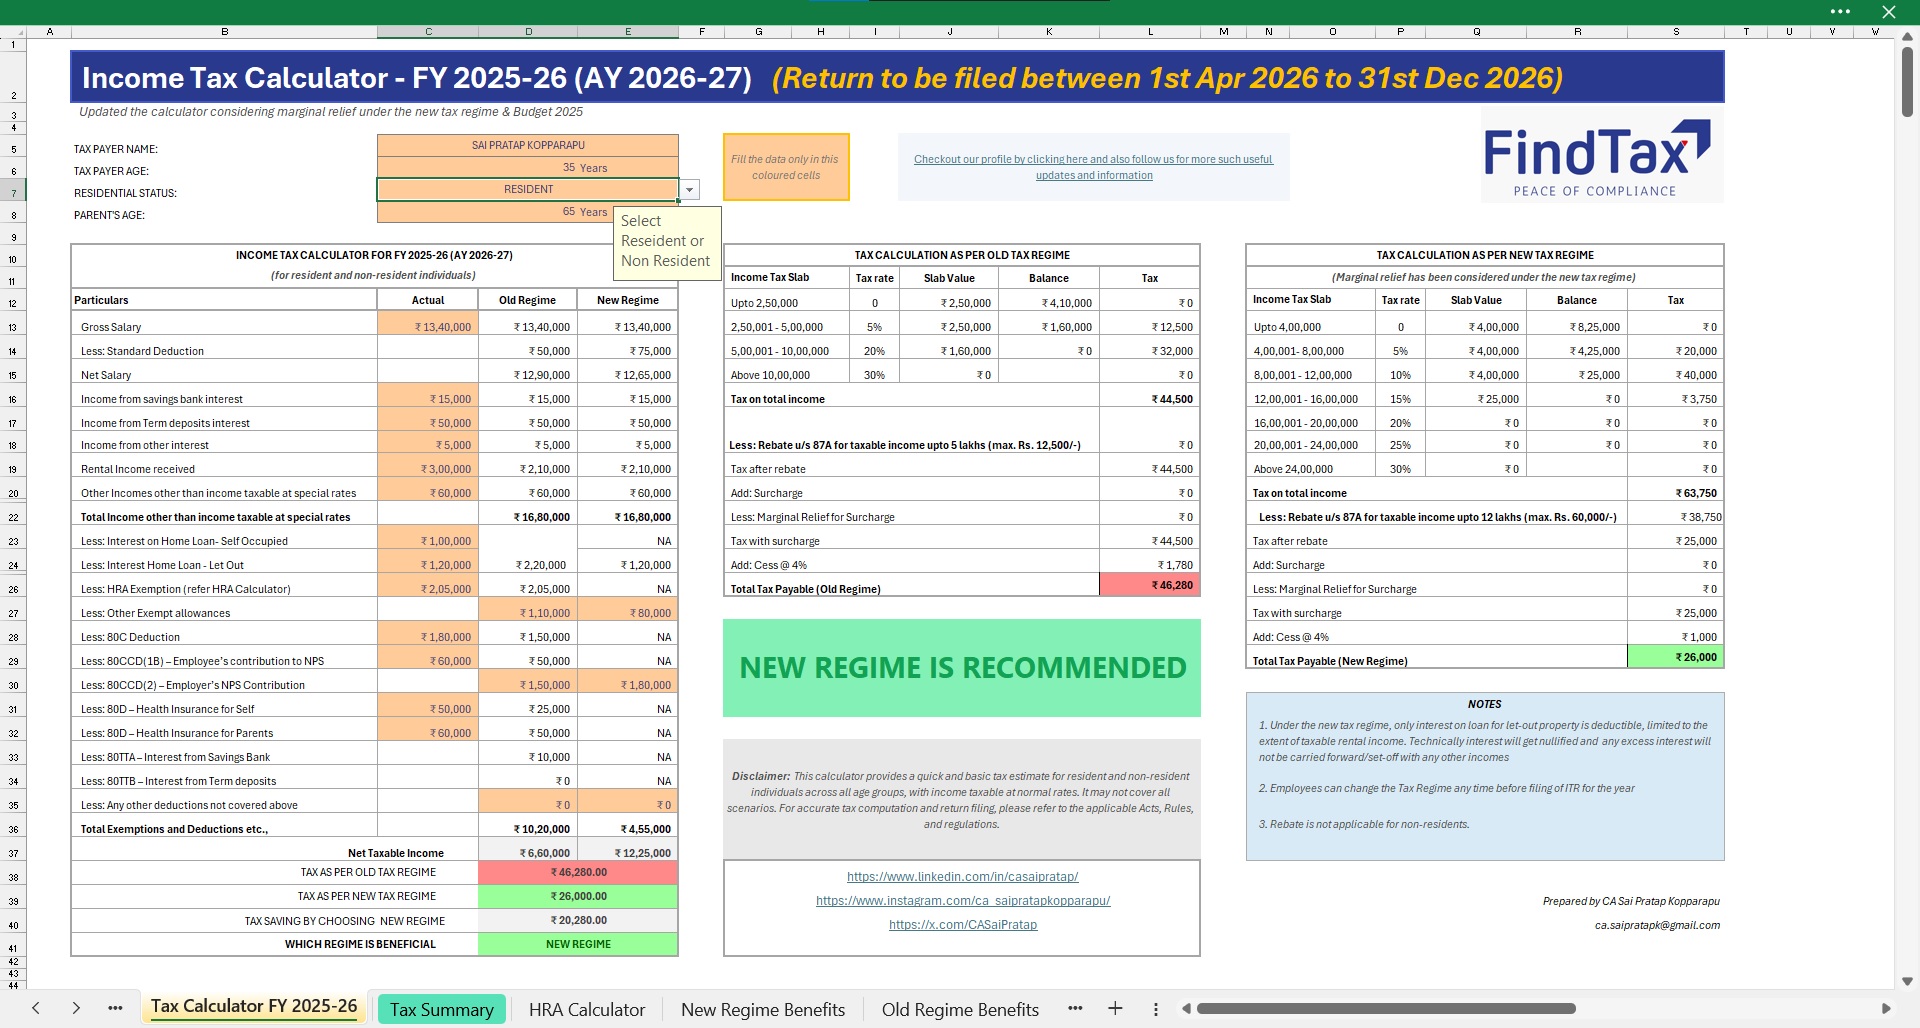
Most people build tax revenue calculators and immediately hit a wall because they treat taxation as linear. It isn't. The moment you introduce progressive brackets, phase-outs, or standard deductions that vary by filing status, the math changes shape entirely. I spent about three weeks debugging a spreadsheet model last year where the revenue projections were off by roughly fourteen percent compared to Treasury estimates. The culprit was a carryback provision that most templates ignore completely. At its core, the calculator multiplies taxable income distributions by applicable marginal rates across bracket thresholds. You start with a taxpayer population segmented into income bands, apply each band's tax rate schedule, then sum the totals. The basic formula looks like this: total revenue equals the sum of (taxable income in bracket i times the marginal rate for bracket i) across all brackets. Simple on paper. Where people mess up is assuming the brackets stay static. They don't. Most jurisdictions index brackets for inflation annually, and if your calculator doesn't account for that indexing drift, your projections will degrade within two or three years. I learned this the hard way when a client's five-year forecast was being used in a legislative hearing and the staff didn't catch that the bracket thresholds hadn't been updated since 2021.
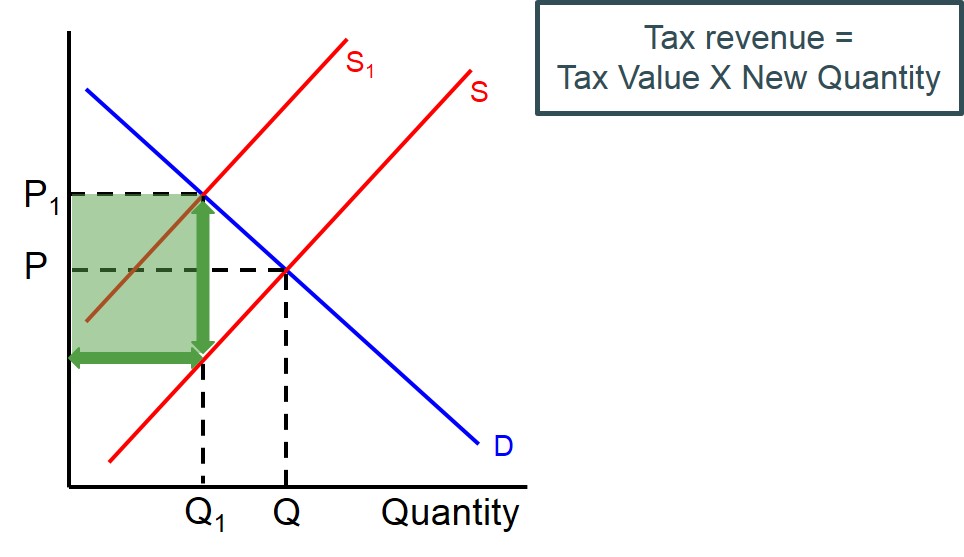
The second thing nobody explains well is the difference between statutory rates and effective rates. Your calculator should output both. A taxpayer in the 24 percent bracket might actually pay closer to 18 percent effective after credits and deductions. If you're building a Tax Revenue Calculator Economics tool, you need to model the phase-out of itemized deductions or personal exemptions that create what economists call the "bubble" effect where marginal rates temporarily spike.
A Real Problem I Ran Into
When modeling state-level corporate income tax alongside federal provisions, I encountered a stacking issue where credits claimed at the state level reduced federal taxable income, which then cascaded back through the revenue calculation. Most calculators don't handle this feedback loop. They run federal first then state as a separate exercise. The correct approach is iterative: calculate federal liability, adjust state taxable income, recalculate federal with the adjusted figure, and loop until the numbers converge. It usually takes two or three iterations to stabilize. Without iteration, you're off by somewhere between five and twelve percent depending on credit magnitude. The workaround I ended up using was a convergence algorithm with a tolerance threshold set at one cent per dollar of revenue. Once the change between iterations dropped below that threshold, the model stopped looping. It ran in about forty seconds for a full five-year projection on a standard laptop.
Get the Full Details

What Beginners Miss
Elasticity is the hidden variable. When you raise a tax rate in your model, revenue doesn't increase one-to-one because behavioral responses exist. Higher earners shift income, corporations restructure, and deduction claims increase. A decent calculator should allow you to input an elasticity coefficient and see how revenue shifts. Without it, your model overstates revenue from any rate increase. The typical range for labor income elasticity is between negative 0.1 and negative 0.5, meaning a ten percent rate hike might only produce six or seven percent more revenue, not ten. Another thing: transfer payments. Tax revenue isn't just collected, it's redistributed. Your model needs a column for refundable credits because those reduce net revenue. The Earned Income Tax Credit, the Child Tax Credit, the American Opportunity Credit — each one flows through the same system and needs to be subtracted from gross collections. I've seen models that calculated gross revenue beautifully and then presented it as net without any deduction for refundable programs.
Limitations You Should Know About
This approach assumes people file correctly and on time. It doesn't account for compliance gaps, which can range from three to eight percent of owed revenue depending on the jurisdiction and income segment. Low-wage workers and gig economy participants underreport significantly more than W-2 employees. If you need accuracy within two percent, you have to factor in a compliance adjustment layer, usually derived from IRS audit studies or state-level mismatch data. The model also can't predict legislative changes. If a jurisdiction eliminates a deduction or changes bracket thresholds mid-cycle, your entire projection resets. I recommend building the calculator so that bracket schedules and credit amounts are stored as external parameters rather than hardcoded values. That way when the law changes, you update a single cell and the whole model recalculates. If you need something faster than building from scratch, open-source Python packages like taxcalc and pytaxpolicy exist, but they have steep learning curves and documentation that assumes you already know what you're doing. For most practical purposes, a well-structured spreadsheet with clearly labeled parameter cells will get you there faster and let non-technical stakeholders follow the logic.

.jpg "Income Tax Calculator: Estimate Your Refund in Seconds for Free")