How I Figure Out What Chunk Of Social Security Actually Gets Taxed
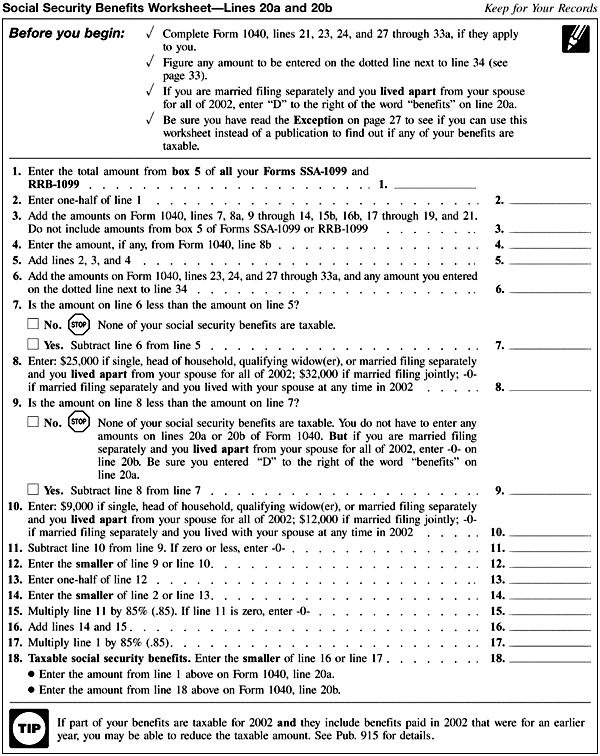
Most people have no idea the IRS can tax up to 85 percent of their Social Security benefits, and the calculation itself is buried in IRS Publication 915. I've been preparing taxes for individual filers for over a decade, and honestly, this section is one of those places where the instructions feel like they were written by someone who enjoys making your life difficult. The worksheet isn't intuitive. It repeats lines from your Form 1040 in ways that seem redundant until you actually follow it, at which point it makes a grudging sort of sense. The basic mechanism is simpler than the worksheet makes it look. You take your modified adjusted gross income, add half of your Social Security benefits, and see whether that total crosses a threshold. For single filers, the threshold is $25,000. For married filing jointly, it's $32,000. Below that, nothing gets taxed. Above it, somewhere between zero and 85 percent of your benefits enters your taxable income, depending on how far over the line you are. The worksheet is just the mechanical way of converting that principle into actual dollar amounts you report on Line 20b of Form 1040.Using the Taxable Amount Of Social Security Benefits Worksheet Correctly
I'll walk through the actual steps instead of making you go dig through Publication 915 right now. Grab your 2024 Form SSA-1099 first. Line 3 on that form is the total benefits you received during the year. That's your starting point for everything.Step one: enter one-half of the amount from SSA-1099 Line 3. If you received $20,000 in benefits, you're entering $10,000 here. Don't skip this. I've seen people accidentally use the full amount and then wonder why their taxable income spiked unexpectedly. Step two: take your modified AGI. This is your AGI from Form 1040 Line 11, plus any tax-exempt interest from Schedule B Line 8a, plus any foreign earned income or housing exclusion if you claimed that. It's not just your regular AGI. The modification matters, especially if you have municipal bond interest or lived abroad at any point during the year. Step three: add the result from step one to your modified AGI from step two. This sum is what the worksheet calls your combined income. It's the number that determines whether you even enter the taxable zone.
Step four: compare that combined income to the thresholds. If you're single and under $25,000, you're done. Zero taxable benefits. If you're married filing jointly and under $32,000, same thing. Move on with your life. If you're above the threshold, the worksheet splits into two calculation tracks depending on how far above you are. Between the base threshold and an upper limit, you tax up to 50 percent of your benefits. Past the upper limit, you tax up to 85 percent. The upper limit for single filers is $34,000. For married filing jointly, it's $44,000. These numbers are fixed by statute and haven't changed in years, which means inflation has effectively lowered the real threshold over time.
Here's where it gets weird and where most people mess up. The worksheet has you calculate two separate amounts and then take the lesser of the two. Amount A is 50 percent of the excess over the base threshold, but capped at 50 percent of your total benefits. Amount B is 85 percent of your combined income minus the upper threshold, again capped at 85 percent of total benefits, minus a rebate that accounts for the first bracket. You pick whichever is smaller. This mechanics-of-the-lesser-of approach is what trips people up because it feels arbitrary until you realize Congress designed it that way to phase in the taxation gradually rather than hit everyone at the top rate immediately. I remember working with a client in 2019 who had a small pension, some rental income, and Social Security. His combined income landed him just above the $34,000 single threshold, around $34,800. He expected almost nothing to be taxed because he was so close to the line. Instead, the worksheet pushed about $680 of his $18,000 annual benefits into taxable income. The marginal impact wasn't catastrophic, but it was 3.8 percent of his benefits getting taxed at his ordinary rate, which pushed him into a slightly higher effective bracket than he'd planned for. The lesson here is that being close to the threshold doesn't mean you escape taxation entirely. The phase-in starts immediately once you cross it.A couple of things the worksheet won't tell you directly: Roth conversions in the same year you start taking Social Security can push you into the taxable zone even if you thought you'd stay under. Traditional IRA distributions, pension payments, and capital gains all feed into modified AGI, which feeds into the worksheet. One year of deliberate income management can shift your entire benefit taxation picture. Claiming benefits before full retirement age doesn't change the worksheet mechanics, but it does affect your total benefits because the reduction applies to the gross amount. Someone taking benefits at 62 instead of 67 might actually have a lower combined income and stay under the threshold, which means zero taxation. That's a genuine trade-off that the worksheet itself won't highlight, but it's worth considering when you're deciding when to file. State taxation is a separate question entirely. Some states fully exempt Social Security. Some tax it without any of the federal adjustments. If you live in a state like Kansas or Pennsylvania that recently changed its rules, you might find yourself doing a second parallel worksheet for state purposes. Check your state's instructions before you assume the federal calculation maps directly onto your state return.
Get the Full Details

Where the Worksheet Falls Apart
I need to be straight about the limitations here. The worksheet only tells you the taxable portion of your benefits. It doesn't tell you your actual tax liability. You still need to run that through your marginal brackets, the net investment income tax if you have one, and the possible additional Medicare tax if your wages exceed $200,000 for single filers. Social Security benefits themselves don't count as net investment income, but they do count toward the Medicare surtax threshold indirectly by raising your MAGI.The worksheet also assumes you have straightforward income. If you have business losses, rental losses with active participation, or carried-over losses from previous years, those interact with modified AGI in ways that the worksheet doesn't explicitly address. You need to reconcile those line items on your actual Form 1040 before feeding numbers into the worksheet, or you'll be plugging in the wrong base. Another limitation: the worksheet gives you a taxable dollar amount, but it doesn't account for state-level phaseouts or credits that might offset the extra tax. In some states, the additional taxable income from Social Security could push you out of a low-income credit or into a different tax bracket that changes your overall liability in a non-linear way. Running a full tax simulation afterward is usually worth the 20 minutes it takes.
If you find yourself consistently near the thresholds and doing this calculation every year, tax preparation software handles the worksheet internally and saves you from manual errors. I still recommend pulling up the actual worksheet in Pub 915 at least once to verify the software got it right, because I've seen cases where the software misread a foreign exclusion or missed a tax-exempt interest line and produced an incorrect taxable benefits figure. The software isn't wrong often, but when it is wrong, it's wrong in exactly the way that catches people off guard.When to Pull the Actual Form 1040 Schedule or Worksheet
IRS Publication 915 contains the official worksheet. You can download it directly from irs.gov by searching for "Publication 915 worksheet." Some people prefer the paper version because it's laid out linearly and you can write intermediate numbers in the margins. Others use the digital form because you can copy-paste from your tax preparer's output. Neither approach is objectively better. Pick the one that reduces transcription errors for you.The bottom line is that the worksheet is mechanical but unforgiving of input errors. Get your modified AGI right. Combine your SSA-1099 forms if you have more than one. Compare your combined income against the correct threshold for your filing status. Take the lesser of the two calculated amounts. Report it on Line 20b of Form 1040. That's it. The complexity isn't in the steps. It's in getting the inputs correct and understanding that the phase-in structure means being close to the threshold still carries a real tax cost.