Getting past the basics
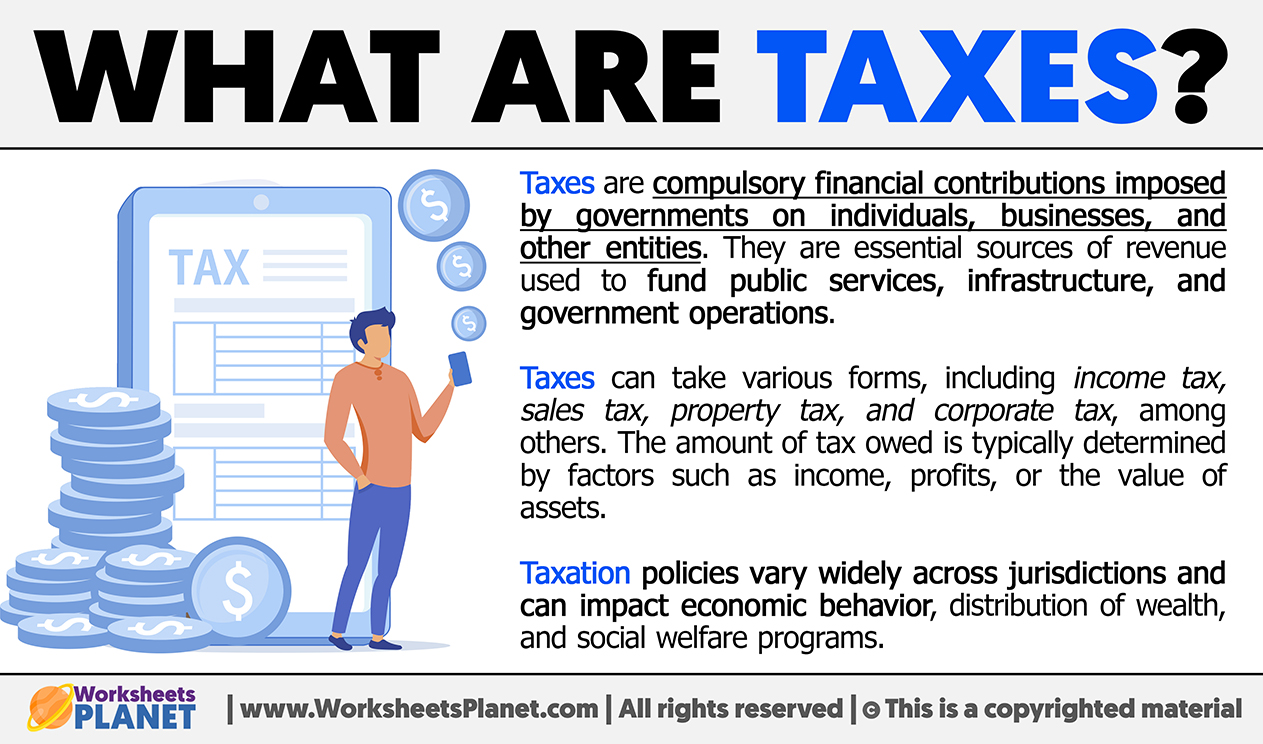
Most people think taxation is just governments taking money. It is that, but the economics framework is far more specific and, frankly, more useful than the political definition. Taxation Definition In Economics refers to the compulsory, unrequited transfer of resources from private to public sectors, analyzed primarily through the lens of efficiency, equity, and incentive effects. The reason that matters is because every tax creates a wedge between what buyers pay and what sellers receive. That wedge is where all the interesting analysis lives. The wedge generates deadweight loss, shifts behavior, and redistributes income in ways that are rarely obvious from looking at the statutory language alone.
Taxation Definition In Economics
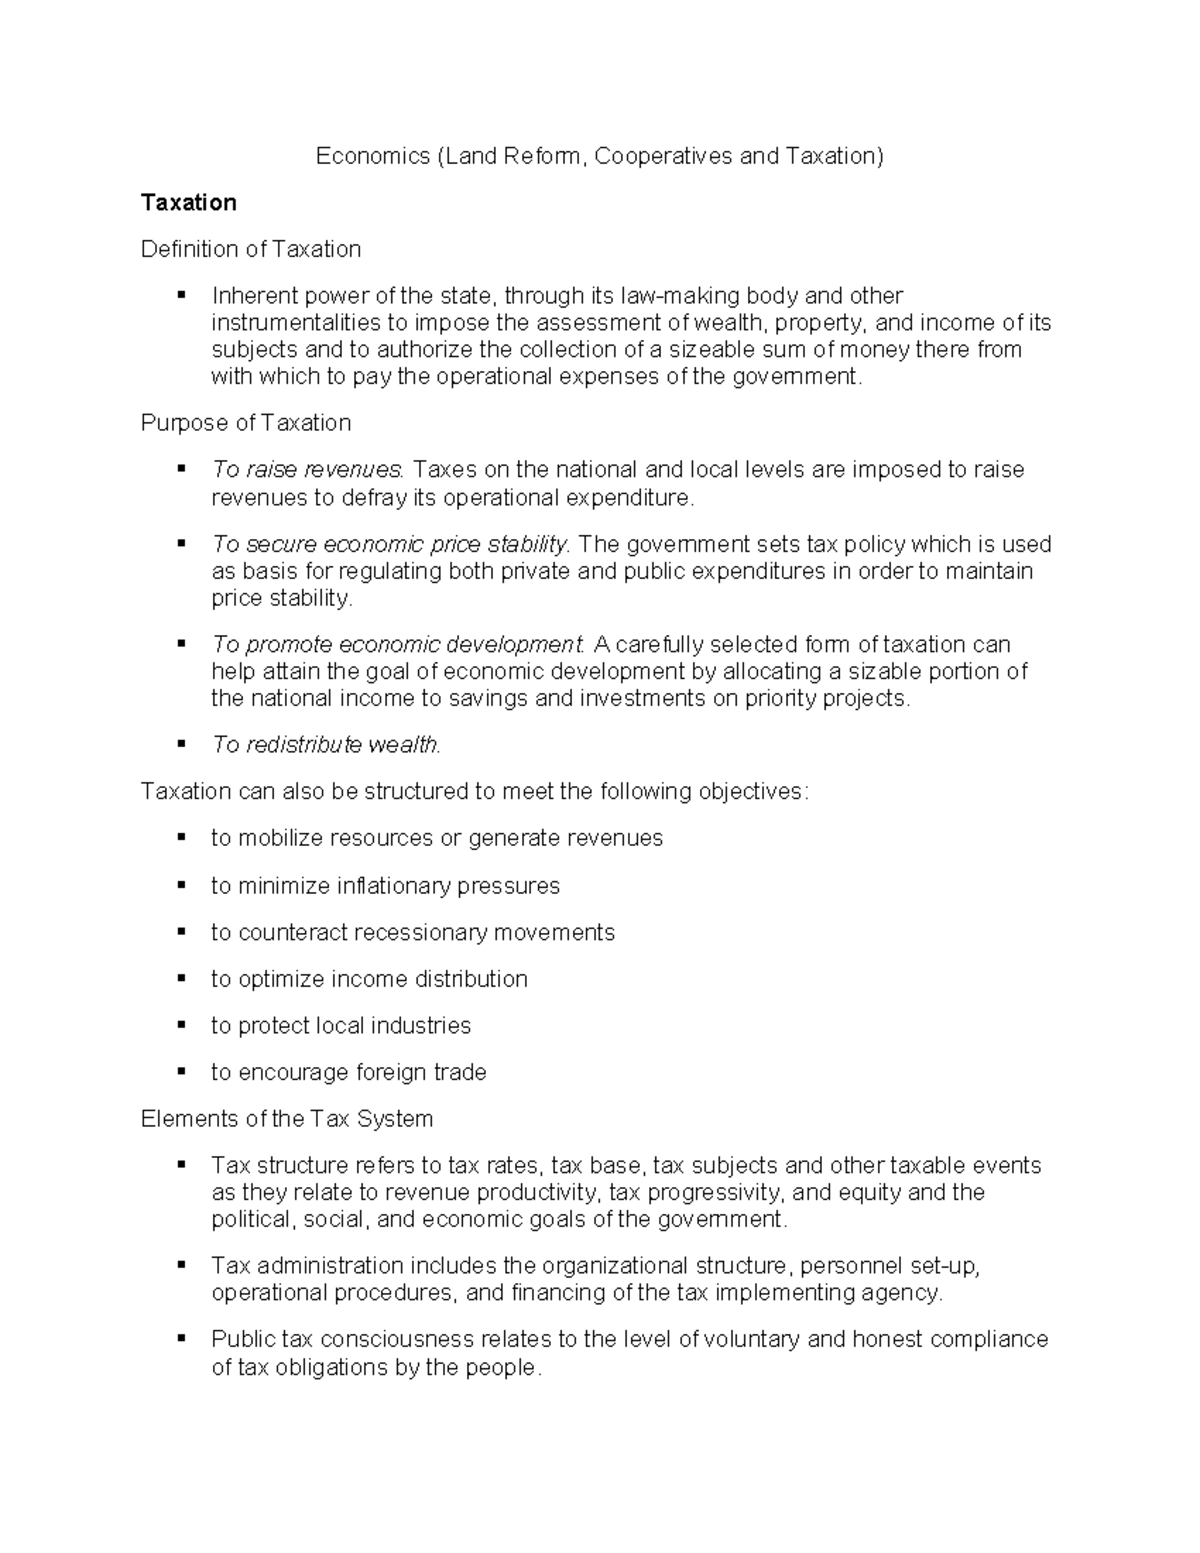
The academic framework splits this into two branches, positive and normative analysis. Positive analysis describes how taxpayers actually respond to tax changes. Normative analysis argues what the tax system should look like given a particular social welfare function. These are frequently conflated in policy debates, and getting them straight is the first skill that separates competent analysis from noise. Three concepts are essential and consistently misunderstood. First, tax incidence is about who bears the economic burden, not who physically writes the check. A tax levied on employers can shift entirely to employees if labor supply is sufficiently inelastic. Second, the Laffer Curve is not a law of nature. It is a theoretical proposition that beyond a certain tax rate, revenue falls because the taxable base contracts. The exact peak is empirically uncertain and varies by tax type. Third, tax neutrality is a benchmark, not a realistic outcome. Any tax distorts relative prices and alters behavior. The question is always how large that distortion is relative to the revenue gained. I ran into a specific problem with corporate tax inversion and the associated transfer pricing adjustments. A mid-sized manufacturing client attempted to restructure its holding company through Ireland after the 2017 US tax reform. The IRS challenged the arm's length pricing on intercompany royalties, claiming the intellectual property valuation was artificially depressed. My workaround was to commission a full comparability analysis using OECD guidelines, build a defensive position around the functional analysis of where value creation actually occurred, and negotiate a corrected transfer pricing methodology that reduced the adjustment by roughly sixty percent without triggering a full audit. I still do not consider that a clean win. The legal fees exceeded what we would have paid in additional tax under the original structure.
The limitation here is important. Transfer pricing documentation is only as strong as the underlying economic substance. When the substance is thin, no amount of paperwork will protect you. In those situations, the safer path is often restructuring the actual business operations before filing, not documenting a problematic arrangement after the fact. On the macro side, a commonly held belief is that tax competition between jurisdictions drives rates down to levels that eliminate public revenue. The evidence is mixed. Capital is mobile, but labor is not. Property taxes, sales taxes, and payroll taxes are largely immune to race-to-the-bottom dynamics because their bases cannot cross borders. The jurisdictions that face real competitive pressure are those relying heavily on corporate income tax, and most of them have shifted their revenue mix accordingly over the past two decades. Another counter-intuitive point is that broad-based taxes with low rates often raise more revenue and create less distortion than narrow taxes with high rates. This is why value-added taxes exist in over one hundred countries. The VAT collects at every stage of production but allows credits for taxes paid upstream, which eliminates the cascade effect that made early consumption taxes politically toxic. The drawback is regressivity. VAT hits lower-income households harder as a share of income, which is why most OECD countries pair it with targeted refund mechanisms.
Get the Full Details
How to approach this practically
If you are analyzing a tax policy proposal, start by identifying the statutory incidence. Who is legally responsible for remitting the tax? Then map the economic incidence by considering the elasticities of supply and demand in the affected market. This two-step process catches most errors people make when they confuse the legal framework with the economic outcome. For personal taxation, the marginal tax rate is more important than the statutory bracket. If you are near a threshold where additional income pushes you into a higher bracket, calculate the effective marginal rate including benefit phaseouts and withholding adjustments. That number determines whether an additional hour of work or a bonus is worth taking. The headline bracket rate is irrelevant to that decision. The one area where the textbook model consistently breaks down is in developing economies with large informal sectors. Tax definitions assume formal registration, record-keeping, and enforcement capacity that simply do not exist in many contexts. The practical solution in those environments is often to tax consumption rather than income, because consumption is harder to hide than earnings. But that approach requires administrative strength at the point of collection, which is a separate problem.
The mathematics behind optimal taxation, particularly the Ramsey rule and Mirrlees framework, are technically demanding and rely on assumptions that rarely hold in practice. Sufficient statistics approaches have simplified the application, but they still require data that most governments do not have. If you need a working model for a policy analysis, start with partial equilibrium estimates rather than general equilibrium simulations. They are less impressive and considerably more reliable. The takeaway is straightforward. The definition is simple. The implications are not. Understanding where the model works and where it fails is what separates people who talk about taxation from people who understand it.