The Reality of Tax Compliance for Alternative Investment Managers
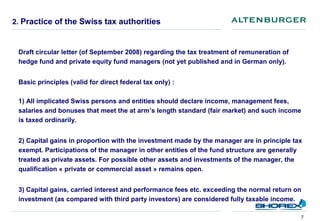
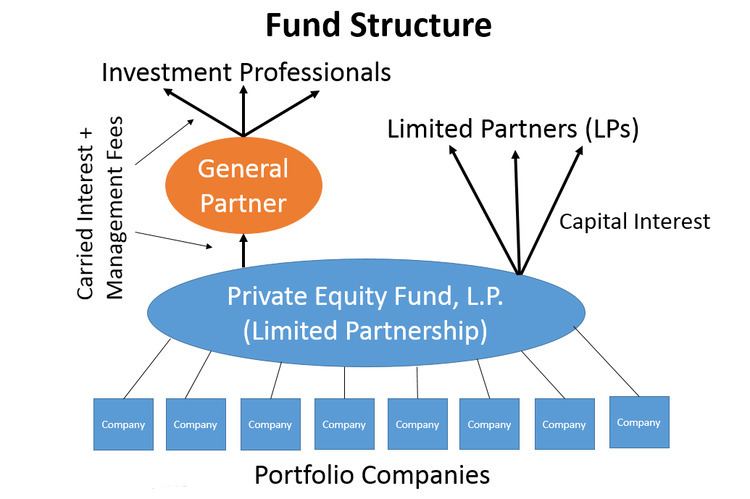
The tax code relevant to fund managers isn't one document. It is a patchwork of federal rules, state-level regulations, and international obligations that shift depending on where your investors are, where your management company is organized, and how your performance fee structure is written. I have spent years watching funds get tripped up not by ignorance of the big concepts but by details most people gloss over. At the core, the mechanics are straightforward enough. Both hedge funds and private equity funds typically operate as pass-through entities, meaning the fund itself does not pay income tax. Instead, profits and losses flow through to the individual partners or limited partners, who report them on their own returns. That is the textbook version. The actual day-to-day work is a lot less clean. The real complexity shows up in how carried interest and management fees are treated, and here is where a lot of people run into trouble. Carried interest—the performance allocation that goes to the general partner or investment manager—has been a contentious topic in tax policy for years. Currently under the current rules, it is generally taxed at capital gains rates provided certain holding period requirements are met. That changes if the IRS or Congress decides otherwise, which is why you will see a lot of fund structures designed with some degree of defensive planning.
Management fees are ordinary income. They are straightforward but they create their own headache because they are collected throughout the year and then allocated across multiple funds, multiple vintages, and sometimes multiple jurisdictions. One thing I learned the hard way involves a fund I worked with that had parallel funds across three states. Each state had a different definition of how management fees should be allocated when the same fee agreement covered multiple vehicles. We ended up reworking the fee allocation memo to explicitly reference each jurisdiction, and that single document became the thing every auditor asked for first.
How The Key Components Actually Work
K-1s are probably the single biggest operational pain point in this space. Each partner in a partnership fund receives a Schedule K-1 at year end, and those forms need to capture not just ordinary income but also capital gains, deductions, credits, and separately stated items. When a fund has institutional investors, foreign partners, and individual high net worth investors all mixed together, the K-1 process becomes a coordination problem across multiple accounting systems and transfer agents. I remember dealing with a situation where one of our fund administrators was using a different fiscal year cutoff than our legal counsel. The K-1s came out three days late because the administrator had not yet closed a reconciliation that legal had assumed was already finalized. That happened because nobody on the finance side had explicitly confirmed the year-end closing date with the legal team in writing. Now I make sure that date is locked down on a shared calendar and communicated at least six weeks before year end. Section 106 and Section 704 of the Internal Revenue Code govern partnership taxation, but the subtleties live in the regulations around substantial economic effect. When you allocate income and losses among partners, those allocations need to reflect the actual economic arrangement or the IRS can disregard them and reallocate based on the partners' overall ownership interests. This matters especially when you have preferred return waterfalls in private equity funds or hurdle rate structures in hedge funds.
Get the Full Details
Another detail that people often overlook is the treatment of catch-up provisions. In a typical private equity carry structure, the general partner receives a 20 percent carry after the limited partners have achieved a preferred return. But there is usually a catch-up mechanism where the GP gets 100 percent of subsequent distributions until the carry percentage is achieved. These catch-up provisions create timing differences between when income is recognized and when cash is actually distributed, and they need to be carefully documented in the partnership agreement to support the tax positions you take.
State And International Complications
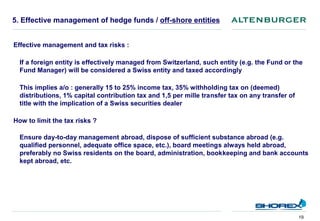
State taxation adds another layer that many managers underestimate. A fund organized in Delaware but managed out of New York, California, or Connecticut may owe state-level taxes or filing requirements in multiple jurisdictions. Some states follow federal partnership rules closely. Others have their own definitions of what constitutes partnership income and how it should be apportioned. Foreign investors introduce additional complexity. A U.S. fund with non-resident alien limited partners needs to handle FATCA reporting, Chapter 3 withholding obligations, and possibly form 4224 or form 1042-S filings depending on the nature of the income. I once worked on a hedge fund that had a Luxembourg-domiciled subfund investing through a Irish feeder structure. The tax positions taken on that structure required coordination between U.S. counsel, Irish tax advisors, and Luxembourg compliance. One misalignment between the Irish and Luxembourg interpretations of the treaty provisions would have created a double taxation exposure of several million dollars annually. If your fund has any foreign component, you should engage advisors who specialize in that jurisdiction rather than relying on your U.S. counsel to handle everything. The cost of specialist advice is small relative to the risk of getting cross-border structures wrong.
Common Pitfalls And Where Structuring Falls Apart
One of the most frequent mistakes I see is insufficient documentation of the economic substance behind the tax positions. The IRS has been increasingly aggressive with partnership audits under the centralized partnership audit regime introduced by the Bipartisan Budget Act of 2015. Under this framework, the partnership itself is the entity that pays any tax deficiency, which means the general partner or management company can be on the hook for penalties and taxes that theoretically belong to former partners who are no longer identifiable or reachable. This changed how many funds approach their tax compliance. Rather than relying on informal understandings or loosely drafted partnership agreements, funds now need robust documentation that supports every allocation and every tax position. It is not about being aggressive. It is about being defensible. Another area where things go wrong is with the timing of basis adjustments. When a partner contributes property to a partnership or receives a distribution, the basis calculations need to be accurate. Getting them wrong creates mismatched gain or loss recognition that can cascade through multiple tax years. I have seen funds spend months untangling basis errors that originated from a single incorrect assumption about the fair market value of contributed assets at the time of contribution.
There is also the issue of disguised sales under Section 707. If a partner exchanges property with the partnership in a manner that is effectively a sale rather than a contribution, the transaction may be recharacterized as a sale, triggering immediate gain recognition. This comes up more often than you might expect when a partner contributes a promissory note or other non-cash asset to a fund.
Practical Steps For Managing The Process
Start with a clear calendar. The partnership tax filing timeline is tight. Form 1065 is due March 15 for calendar-year funds, with extensions available through September 15. K-1s need to be delivered to partners by the same deadline as the return or within the extension period. If you are working with a third-party administrator, build in at least three weeks of buffer before the actual deadline for all reconciliations, closing entries, and draft K-1s to be ready for review. Maintain a single source of truth for your partnership agreement and all amendments. Every time you modify the allocation provisions, the waterfall structure, or the fee arrangement, the tax implications change. I keep a version-controlled document where each amendment references the specific sections of the agreement it modifies and includes a brief tax impact memo. It takes extra time upfront but saves hours of investigation when an auditor asks why a particular allocation works the way it does. Conduct periodic reviews of your state tax positions, especially if you have investors in multiple jurisdictions. A strategy that worked three years ago may not still be optimal if a state has changed its interpretation of partnership income sourcing or if your investor base has shifted geographically.
Finally, do not treat tax compliance as something your accountant handles in isolation. The people managing the fund's investments, negotiating with investors, and drafting partnership documents are the ones who create the transactions that generate the tax complexity. If they operate without awareness of the tax consequences, you will spend the rest of the year cleaning up the mess.