Building a P&L That Actually Works
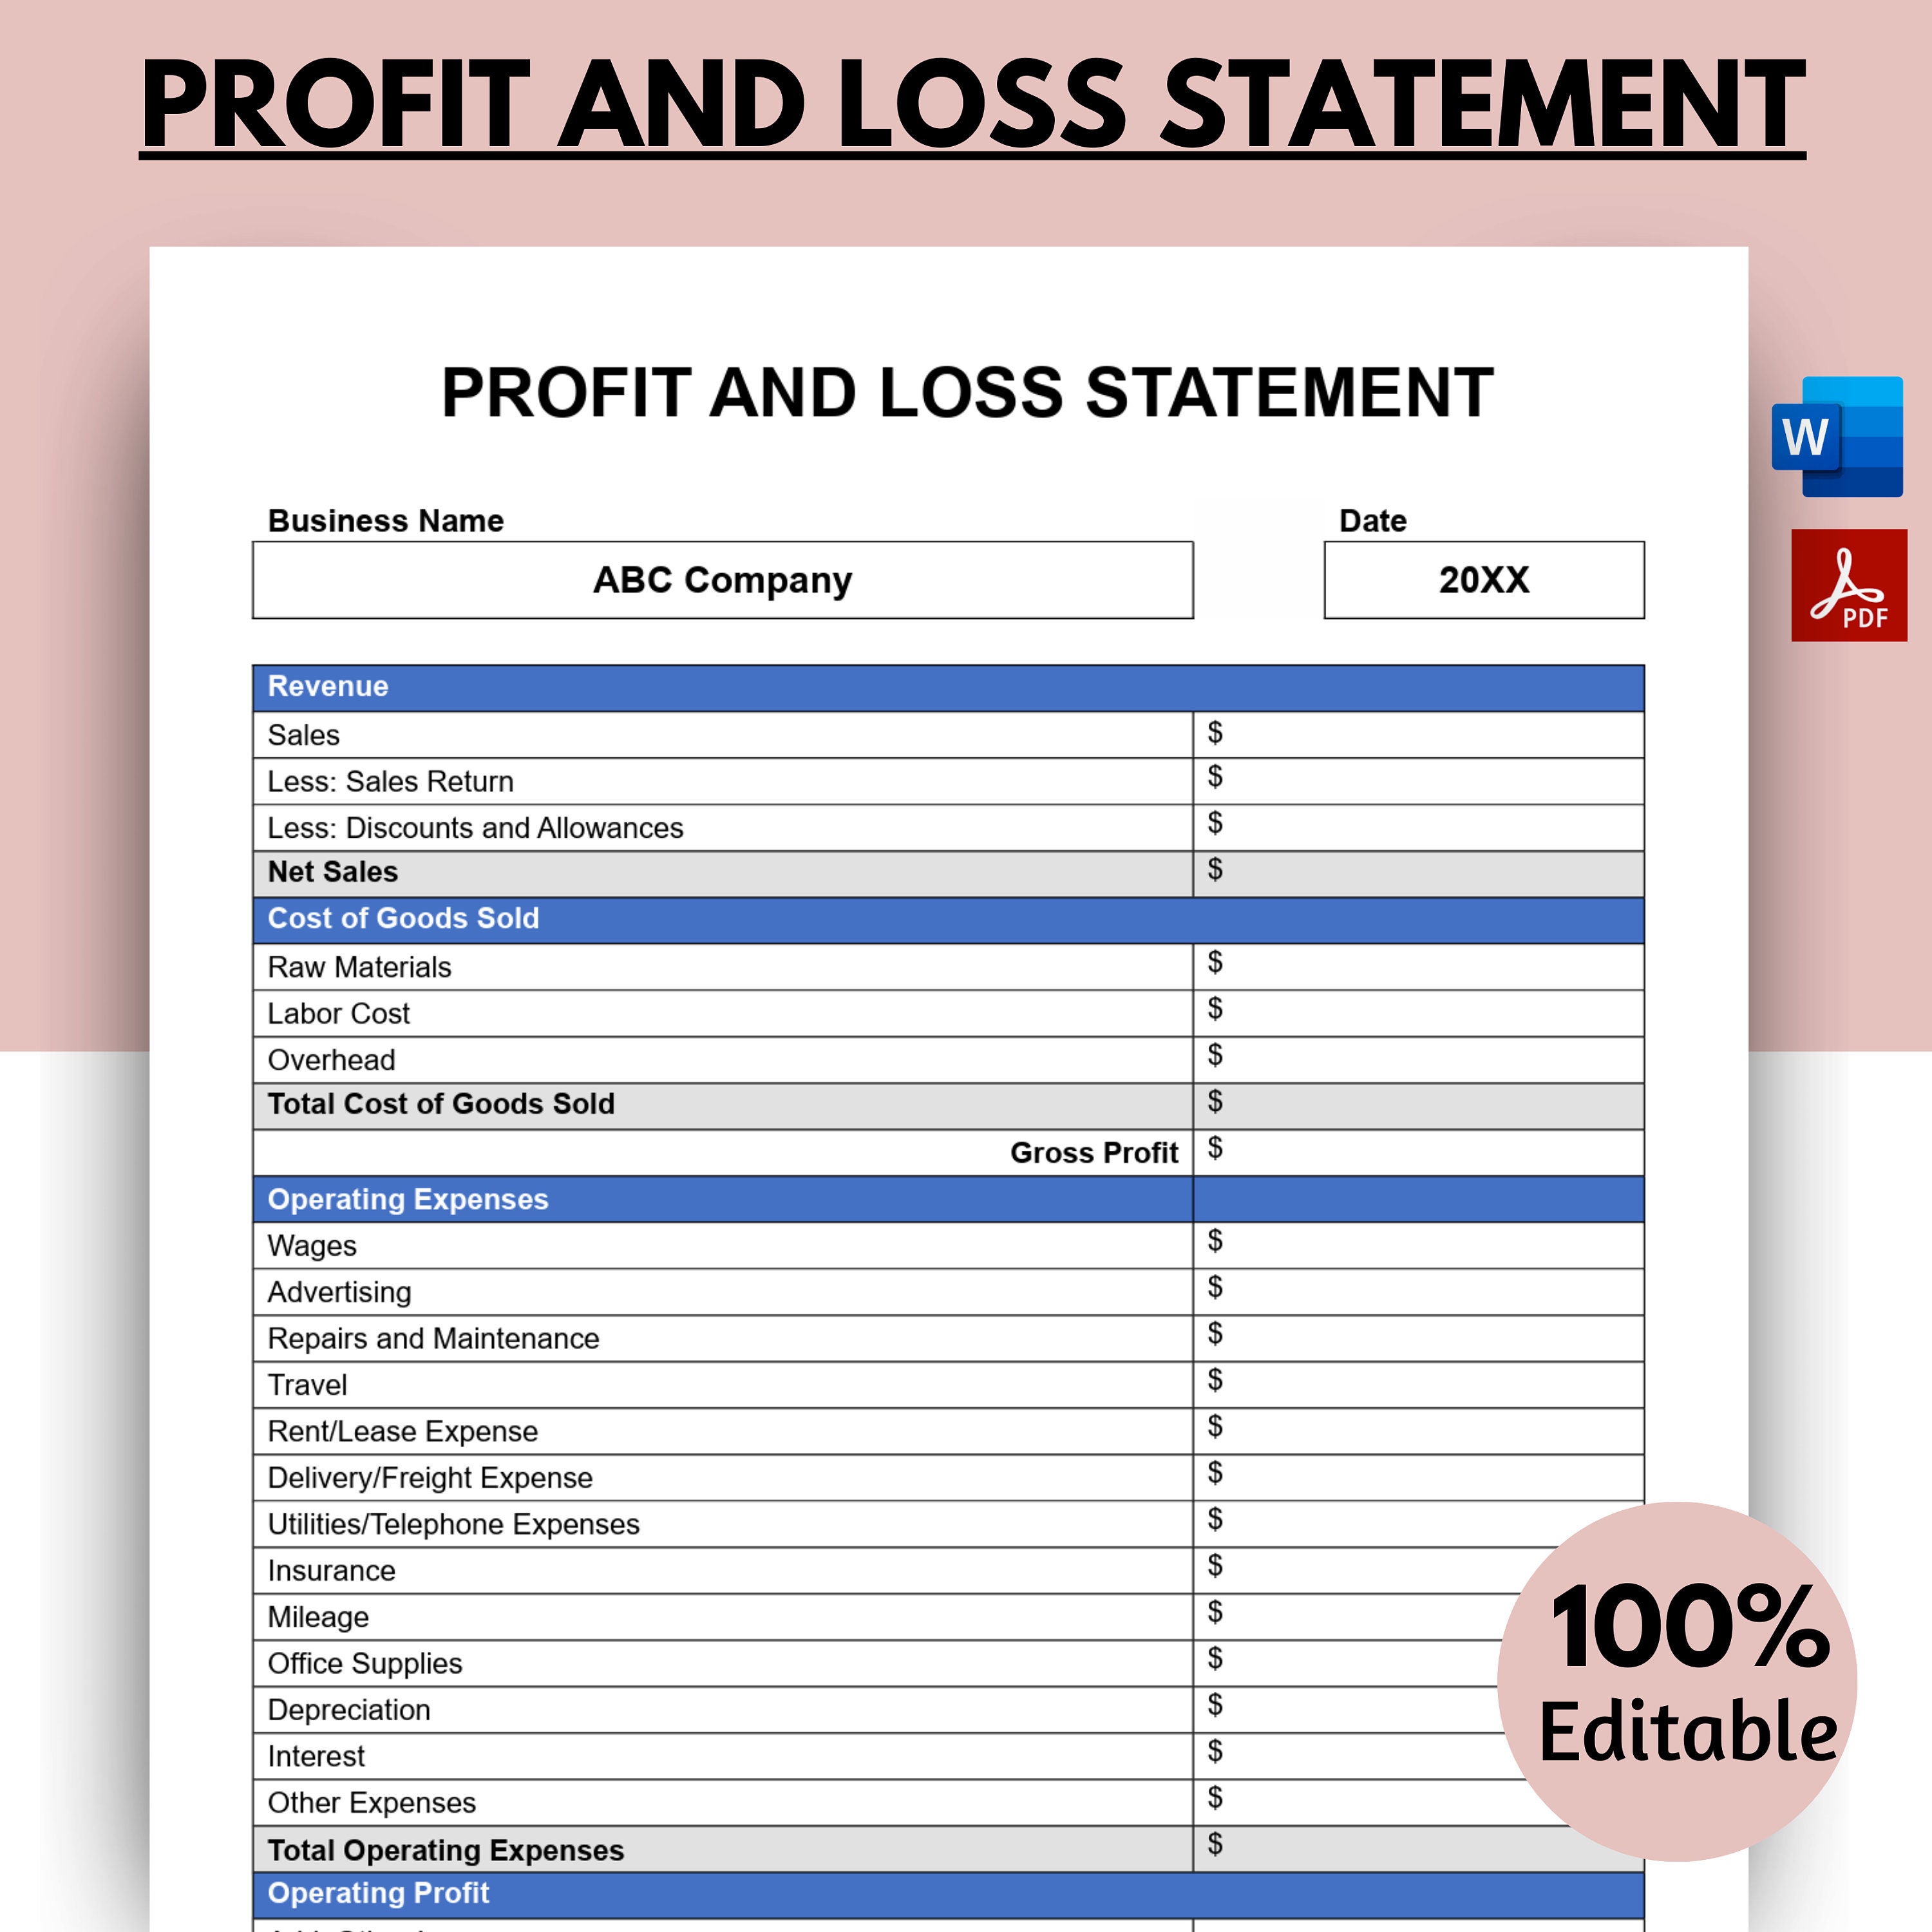
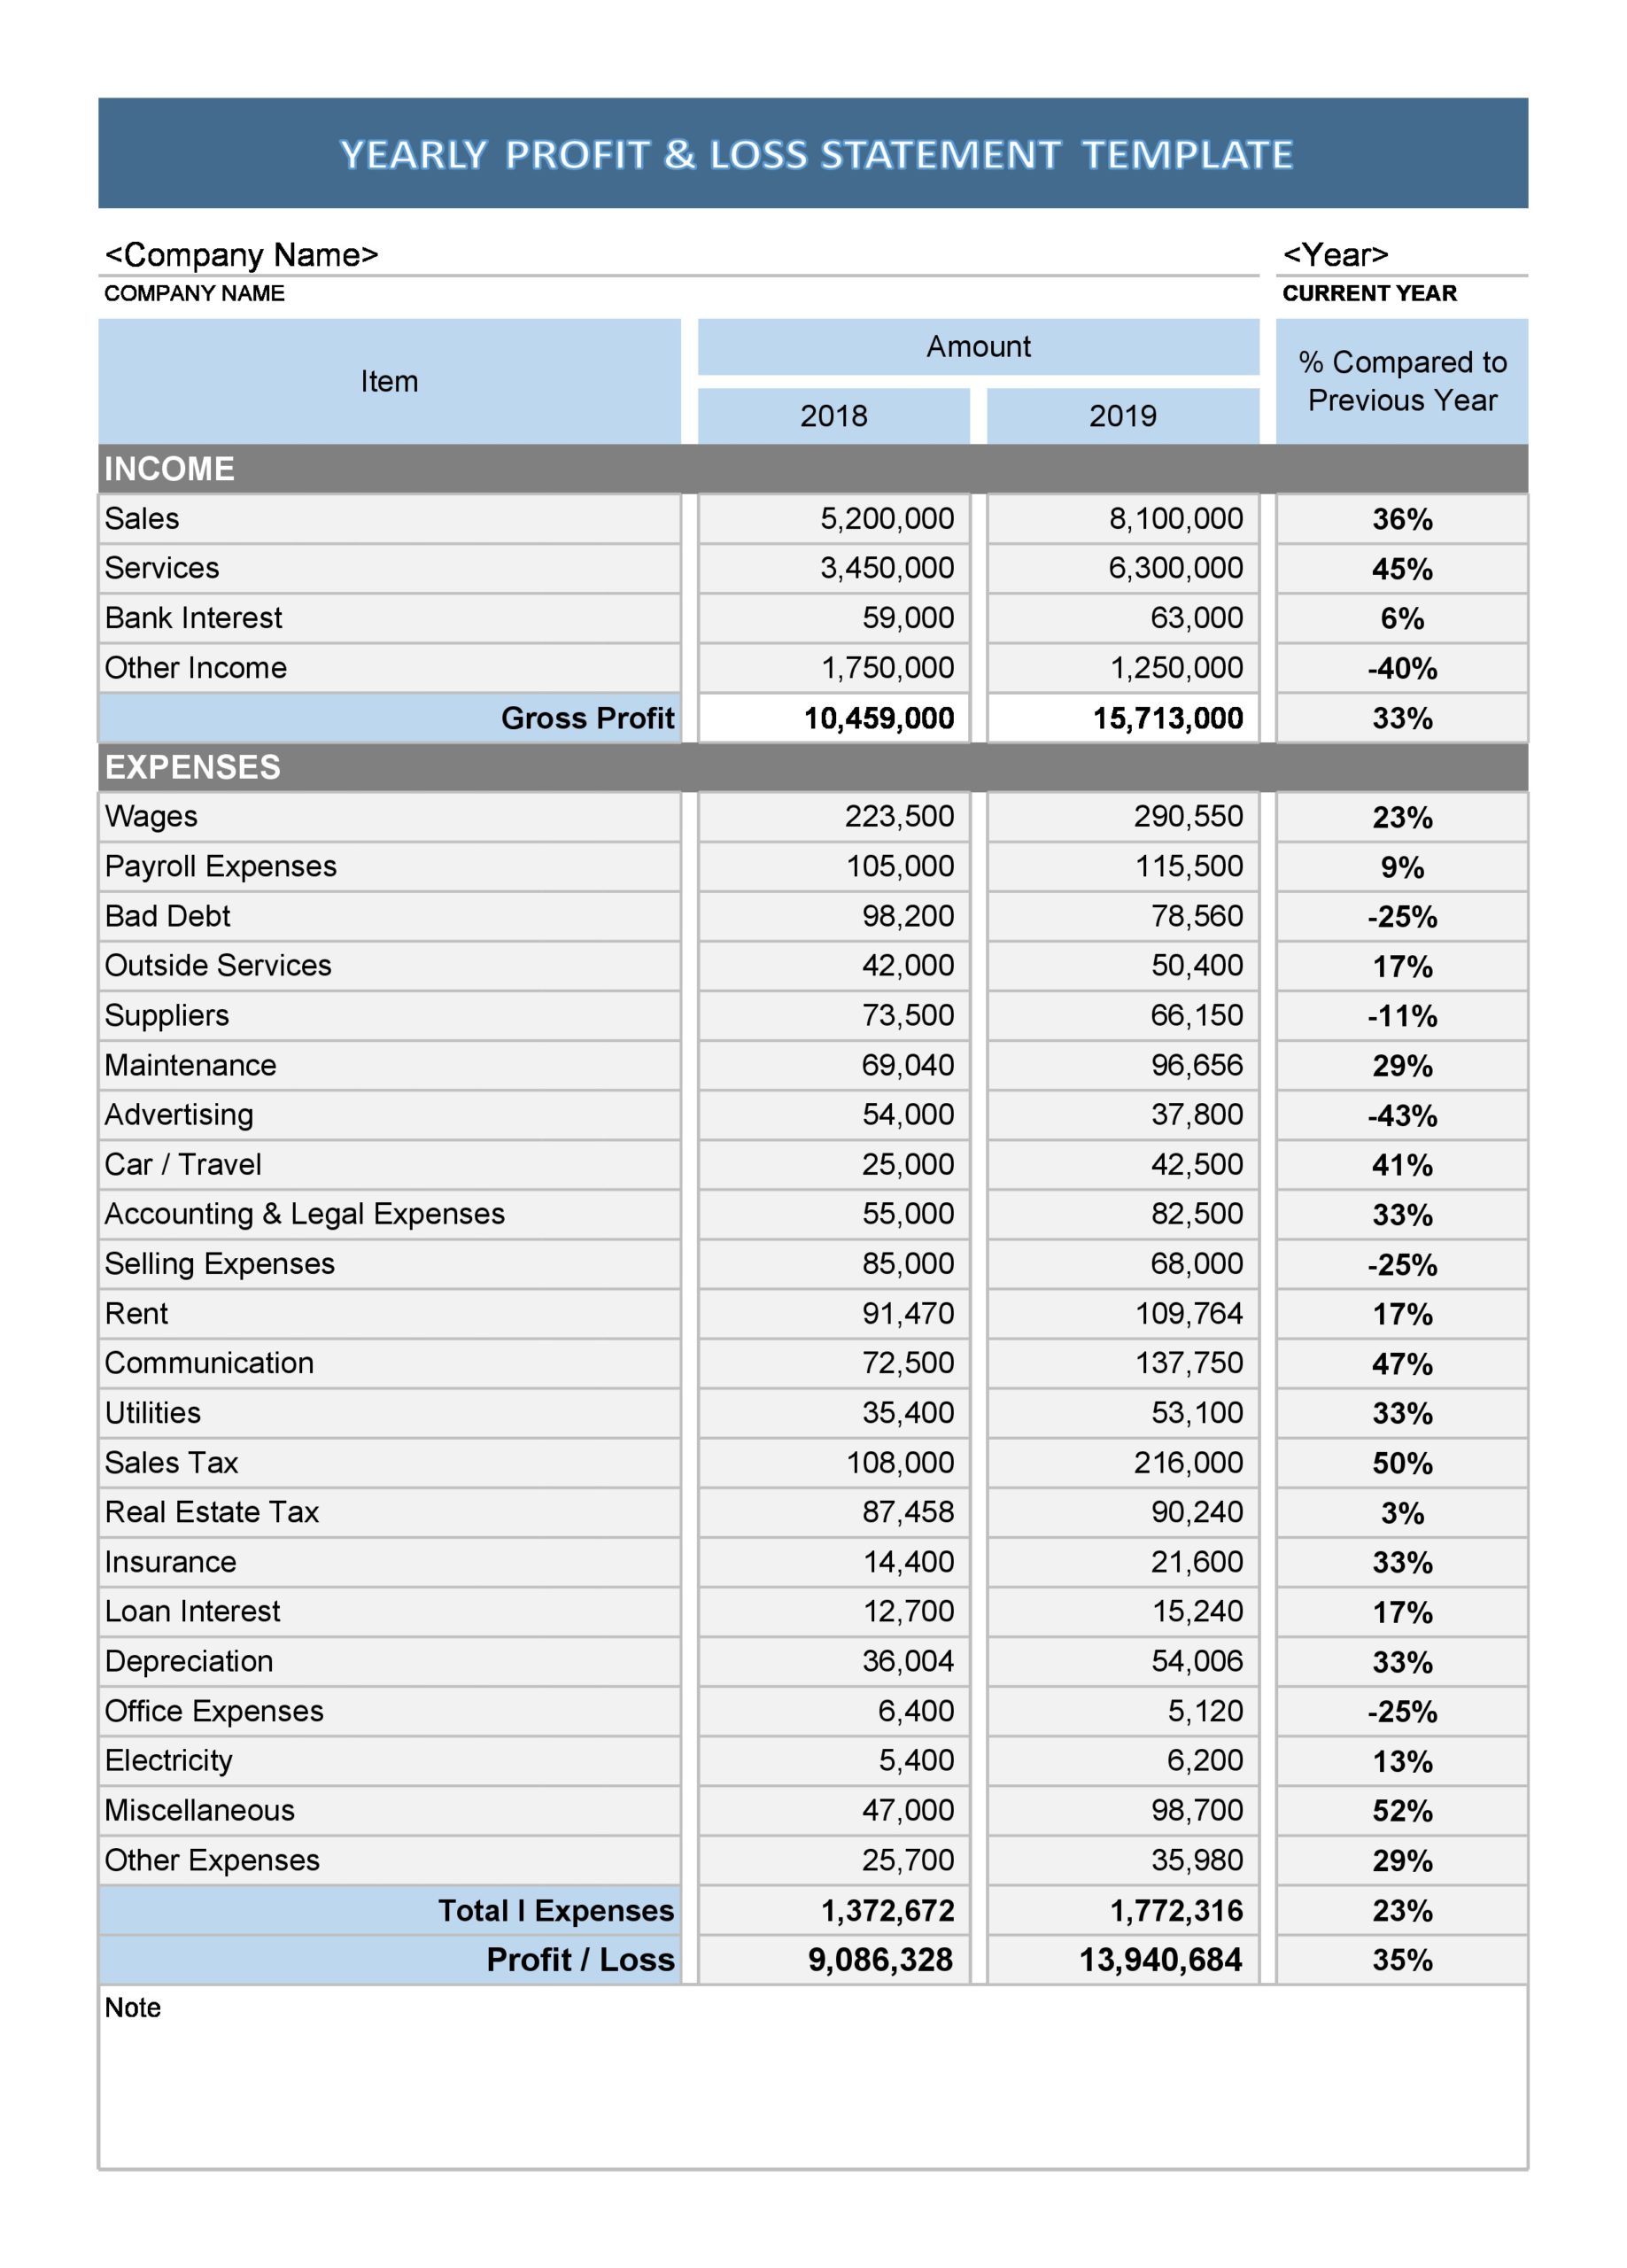
Most people build their profit and loss templates wrong and then wonder why the numbers look suspicious at tax time. The problem is rarely the math. It is the categorization and the assumption that last year's template will work this year without adjustments. I have seen consultants charge three thousand dollars to rebuild these from scratch when the fix was usually three lines and a better chart of accounts. The core structure is straightforward, but getting it right requires attention to how your business actually books revenue and expenses. Let me walk through the practical version, not the textbook version.Template For A Profit And Loss Statement
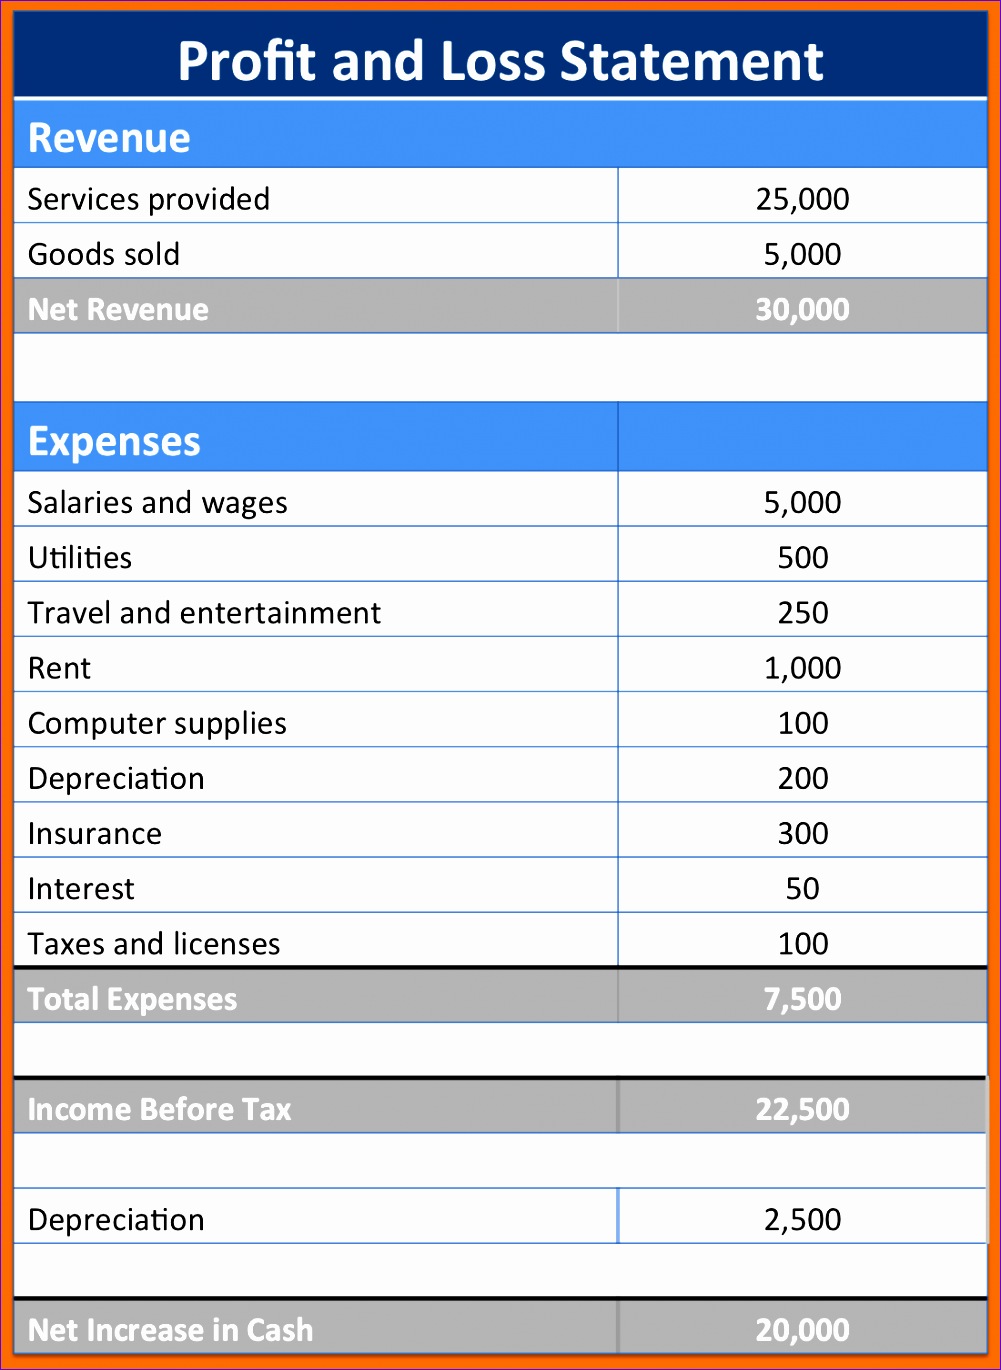
Revenue Section Start with gross revenue. This is all money coming in before any deductions. List it by source if you have multiple streams. Subscription income, service fees, product sales. Do not net these against refunds at the top. Pull refunds separately below as a contra-revenue line so you can actually see what your return rate is. Cost of Goods Sold (COGS)
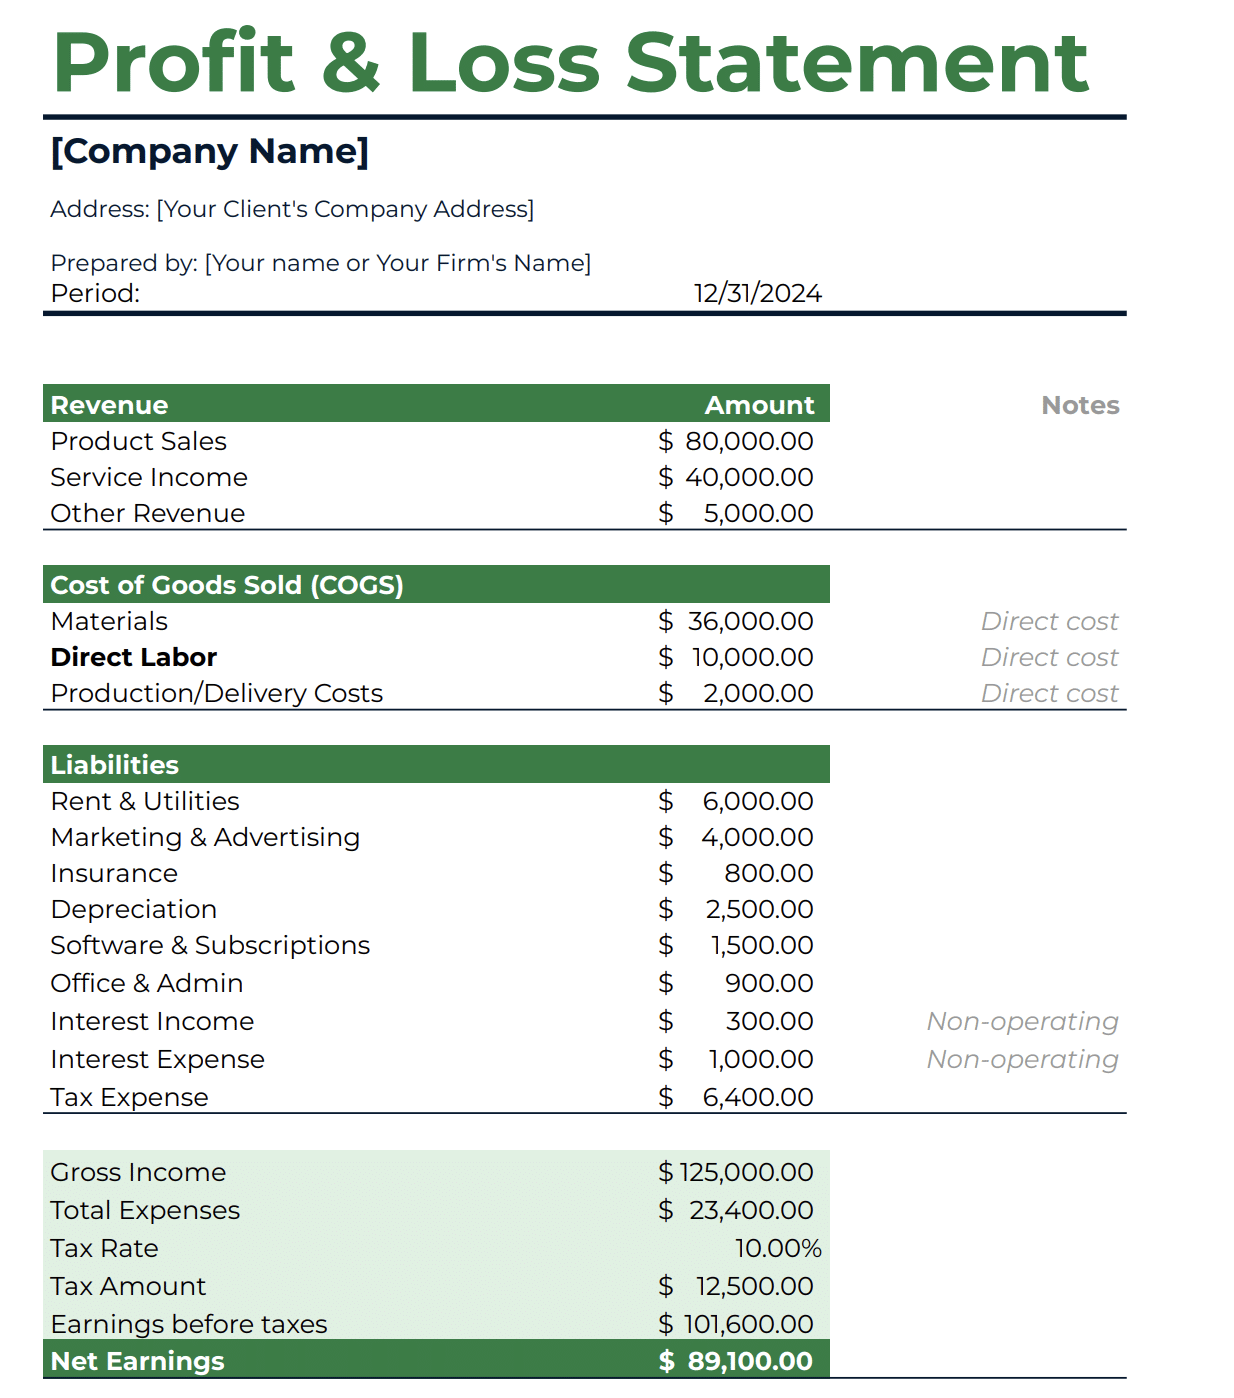
This is the direct cost of producing whatever you sold. Materials, direct labor, manufacturing overhead allocated per unit. If you run a service business, COGS might be contractor payments or software licenses tied directly to client delivery. Get this wrong and your gross margin means nothing. I once worked with a client who classified their cloud hosting costs under operating expenses instead of COGS because they did not realize those servers were directly tied to client work. Their gross margin looked like 80 percent. It was actually 42 percent. That one reclassification changed the entire picture for their lending application. Gross Profit Revenue minus COGS. This is your first real number. It tells you whether the core business is viable before you factor in rent, salaries, and everything else. If gross profit is thin, no amount of expense cutting will save the model.
Operating Expenses Group these logically. Payroll (excluding direct labor already in COGS), rent, utilities, marketing, insurance, professional fees, depreciation, and amortization. Keep payroll separate from everything else. Payroll is usually the single largest expense and investors want to see it on its own line. EBITDA
Get the Full Details
Earnings before interest, taxes, depreciation, and amortization. This is the number most people actually care about when evaluating profitability. You get here by subtracting total operating expenses from gross profit. Some templates skip straight to net income. Do not do that. EBITDA is a standard benchmark. Lenders, buyers, and partners will ask for it regardless of whether your template includes it. Net Income Take EBITDA, subtract interest and taxes, and you have your bottom line. This is what actually hits your bank account over a period. Not the whole story, but the final story.
Where Templates Break Down in Practice
The biggest issue I encounter is period alignment. Revenue recognized in one month might not match the expenses tied to generating that revenue. Accrual accounting solves this, but most small business templates default to cash basis. If you are using cash basis and your revenue is lumpy, your P&L will swing wildly month to month and make it impossible to spot real trends. Switch to accrual if you can. It adds maybe twenty minutes of work per month but eliminates most of the confusion. Another common problem is one-time items buried in operating expenses. A legal settlement, an equipment purchase written off, insurance claim proceeds. These distort your normalized profitability. Create a separate section below EBITDA for non-recurring items so anyone reading the statement can see what the underlying business actually earns. I add a "Other Income and Expense" line right after operating expenses and put anything unusual there. It takes five seconds and saves hours of explanation later. Depreciation and amortization deserve a dedicated schedule linked to the P&L. Do not just throw a single number into operating expenses. Track the asset, the method, the useful life. When someone asks where that nine thousand dollar figure came from, you should be able to produce a sub-schedule in thirty seconds. I keep this in a separate tab and use a simple lookup formula to pull the monthly amount into the main statement.
What Most People Miss
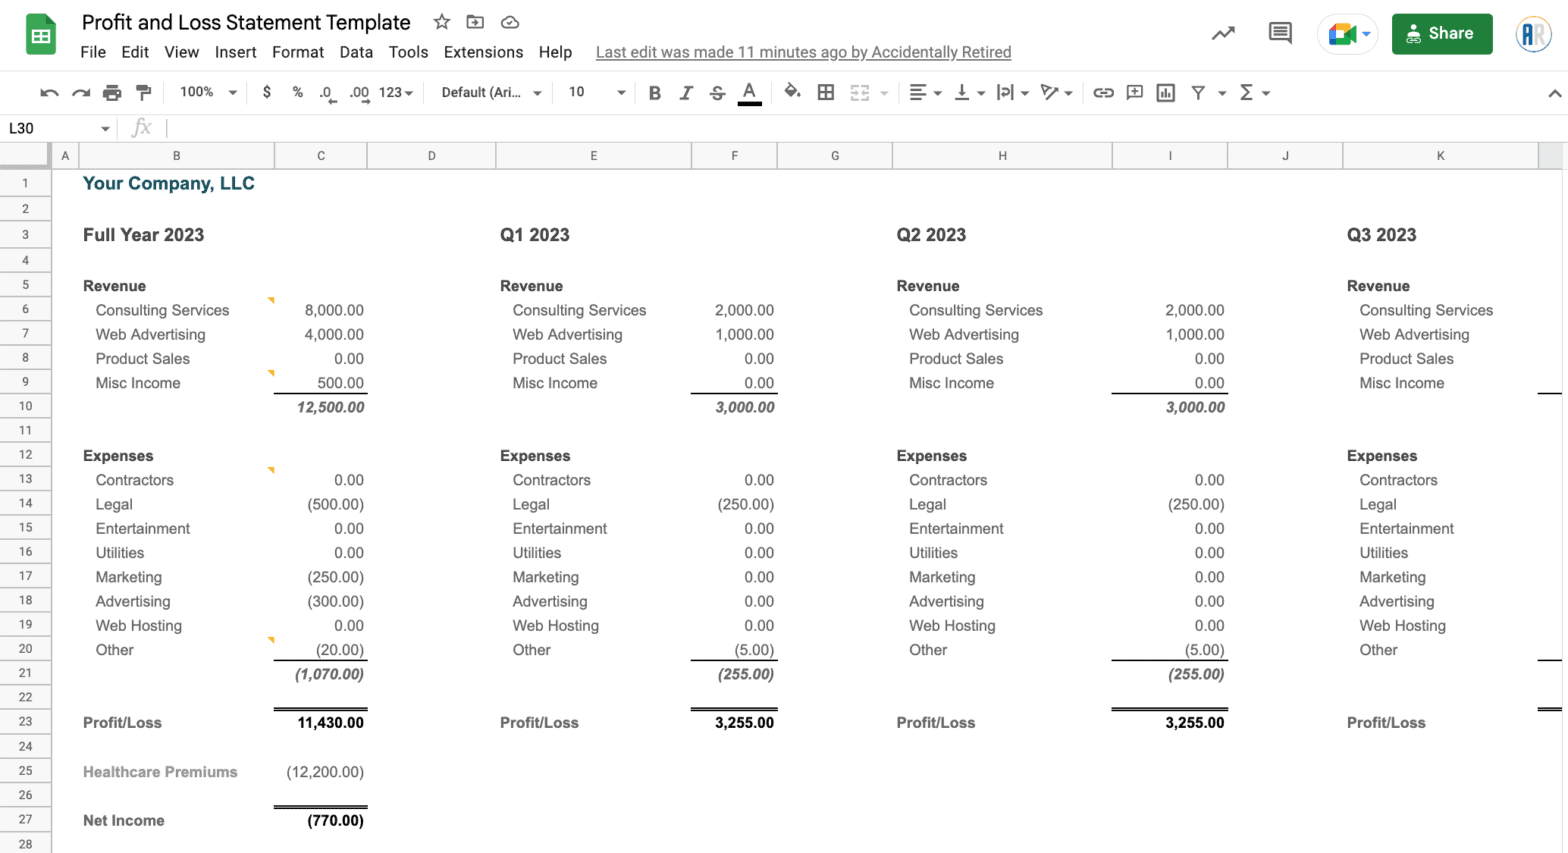
Comparing against budget or prior periods is not optional. A P&L without variance analysis is just a list of numbers. Add columns for budget versus actual and year-over-year comparison. If you are not tracking these, you are flying blind. The variance columns usually take ten minutes to set up and then pay for themselves every time you need to explain a number to someone. Also, include a notes section or supporting schedule link at the bottom. Tax auditors and due diligence reviewers do not trust clean sheets. They want to see where the numbers live. Even a simple reference to which tab contains your payroll detail or your revenue breakdown goes a long way toward credibility.
 (1).png)
Limits of This Approach
A template will not fix a broken chart of accounts. If you are booking everything under generic categories like "miscellaneous expenses" or "other income," no template structure will save you. Clean up the accounts first. The template is a container. Garbage in, garbage out applies here more than anywhere else in accounting. Multi-location or multi-entity businesses will find these single-statement templates inadequate. You will need consolidated views with intercompany eliminations baked in. The basic structure still applies, but the mechanics get significantly more complex. At that point, dedicated accounting software like QuickBooks Enterprise or NetSuite is worth the licensing cost rather than trying to force a spreadsheet to do something it was not designed for. Cash basis templates will always lag reality for growing businesses. If you send invoices in March and get paid in May, your March P&L shows nothing and your May P&L looks inflated. This is not a template problem. It is an accounting method problem. Choose accrual before you choose format.
Implementation Steps
Set up your chart of accounts with clear hierarchy. Revenue at the top, COGS next, operating expenses broken into logical subcategories, then the derived lines for gross profit, EBITDA, and net income. Build variance columns immediately, not as an afterthought. Link depreciation schedules to the main statement. Add non-recurring adjustments below EBITDA. Review the completed statement against last year's actuals to catch categorization drift. If a line item moved categories, document why. Everything else is just maintenance. The template itself lives in a spreadsheet or your accounting software, depending on your volume. For under two hundred transactions per month, a well-structured spreadsheet handles it fine. Beyond that, move to software with automated reporting. The effort to maintain a custom spreadsheet at that scale usually exceeds the benefit.