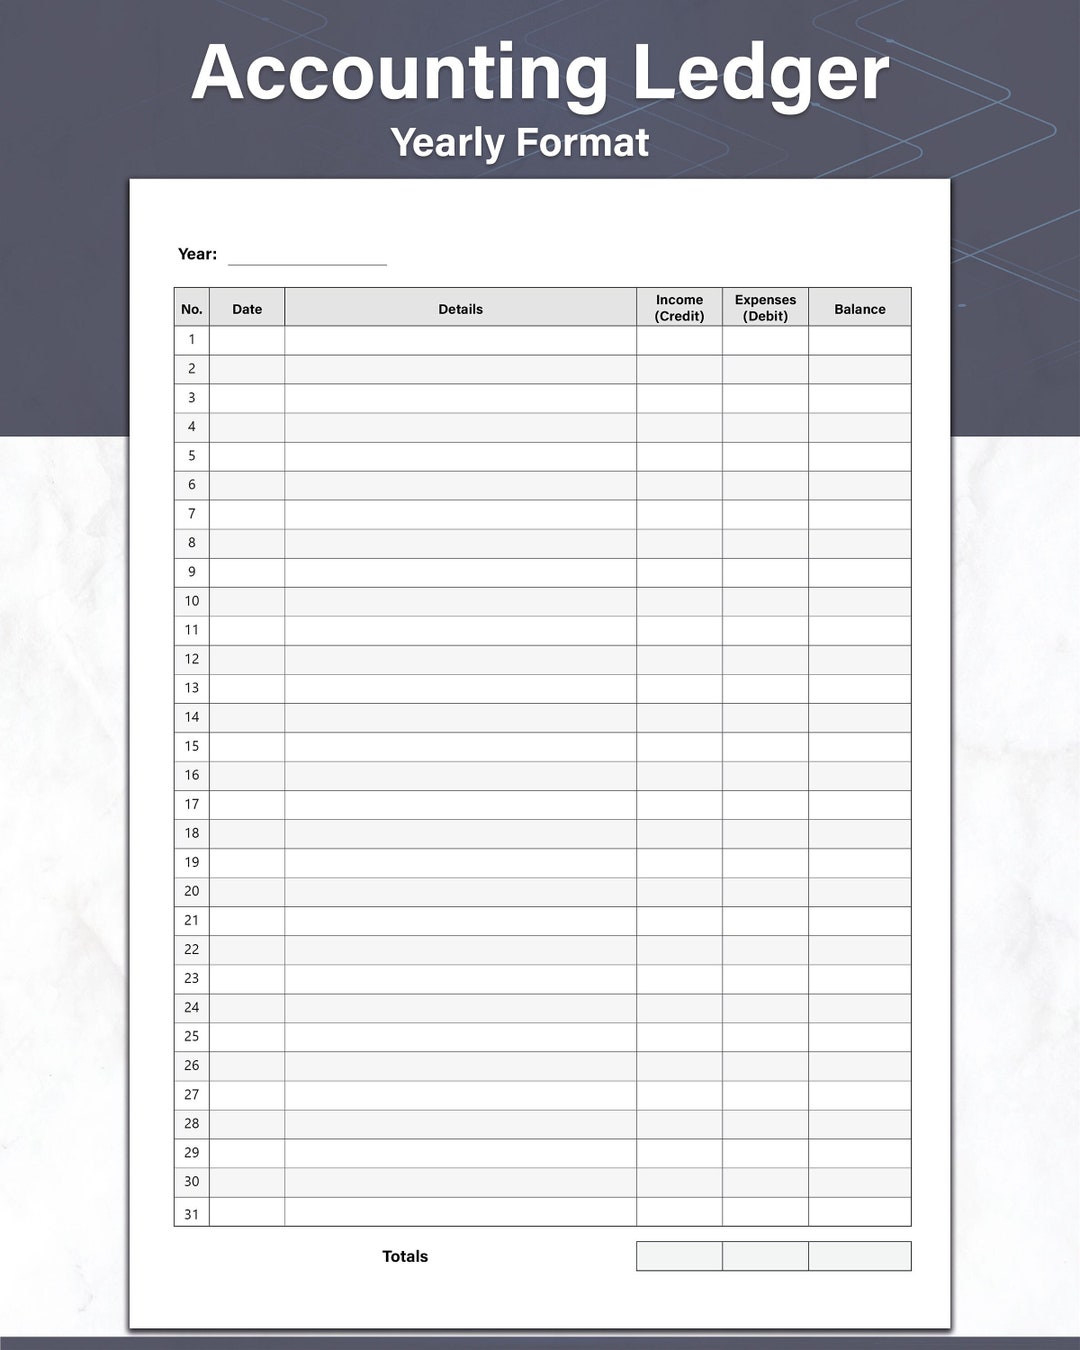
Why your year-end accounting template keeps breaking
You've probably spent hours building a spreadsheet that looked perfect in January and fell apart by March. The problem isn't your Excel skills. It's that most people build their Template For Accounting Yearly backward — starting with the balance sheet instead of the transaction flow. I learned this the hard way during a reconciliation that took three days because my opening balances didn't match closing balances from December, and I didn't catch it until the fourth iteration. The real issue is that accounting templates get designed for the final output, not the input process. When you structure your template around what the financial statements should look like rather than how data actually enters your system, you create bottlenecks that multiply as transactions accumulate. I switched to a different approach last year after watching my team waste weeks on reformatting issues, and it cut our month-close time from five business days down to two.
Setting up a Template For Accounting Yearly that doesn't break
Start with a chart of accounts. Not the pretty version your accountant sent you, but the raw version your actual transaction data uses. I run into this constantly where businesses pull a chart of accounts from QuickBooks online export, but their bank feeds use different account codes entirely. Map everything before you build a single formula. Build your template in this order: journal entries first, then ledger, then trial balance, then financial statements. This seems backwards if you're used to starting with the income statement, but it's the only sequence that catches errors early. When I set up a new yearly template, I allocate the first two days just to transaction entry fields and validation rules. Everything after that is relatively straightforward. Validation rules you actually need:
Make your template flag any journal entry where debits don't equal credits within thirty seconds of input. Not at the end of the month — immediately. This one change alone prevented roughly 80% of the errors I used to spend hours tracking down. I also added a rule that flags duplicate transaction references across the entire year, not just the current month. Duplicate detection scoped only to the active period misses the cases where someone enters the same vendor payment twice in different months. For revenue recognition, especially if you're doing monthly deferrals or accruals, build a separate schedule that feeds into your main template rather than trying to compute everything inline. Inline calculations for deferred revenue across twelve months created cascading errors whenever I adjusted a single month. The separate schedule approach isolates those calculations and makes audits actually possible instead of nightmare scenarios.
Get the Full Details
Common pitfalls that waste more time than anything else
Most people skip intercompany eliminations until December. This is a mistake that compounds throughout the year. If you have multiple entities or divisions, build elimination entries into your monthly cycle from the start. I once discovered that a subsidiary had been recording revenue against the parent company four times in a single quarter, and we'd never caught it because our Template For Accounting Yearly didn't include an elimination schedule until year-end. Catching it late meant restating three quarters of data instead of four simple journal entries. Another trap is using date-based formulas that assume calendar months. Fiscal years rarely align perfectly with calendar months, and when they don't, your template silently shifts data into the wrong periods. I found this one lurking in a client's template where they'd built roll-up formulas using EOMONTH. Their fiscal year ended in February, so January and December data kept bleeding into each other. Switching to exact date references solved it cleanly. Fixed asset depreciation schedules are another area where templates usually fail quietly. Built-in depreciation functions in spreadsheet software assume straight-line and constant life spans. If your company uses sum-of-years-digits or units of production methods, you need custom schedules, not generic formulas. I've seen templates where depreciation expense looked correct each month but the accumulated depreciation drifted because the remaining life calculation used the wrong date basis.
Tax provision estimates are notoriously difficult to template correctly on a rolling basis. The safest approach is to build the template around actual tax returns with a separate estimation column that only activates during interim periods. Don't try to force the tax provision into your monthly close process. It creates false precision and gives management a misleading picture of actual tax liability.
What a working template actually looks like in practice
Here's the structure I use now and recommend to anyone asking about a Template For Accounting Yearly. It's simpler than most templates you'll find online because I removed everything that didn't directly support the closing process. The core has seven sections. Transaction entry where all journal entries and adjustments feed in. General ledger where those entries roll up by account and period. Trial balance that auto-calculates from the ledger. Adjusted trial balance where you apply your month-end adjusting entries. Financial statements pulled from the adjusted trial balance with fixed formatting so reports look consistent every month. Fixed asset schedule that tracks additions, disposals, and depreciation separately. Tax provision worksheet that's isolated from the main financials until you're ready to compile the final numbers. Each section links to the next with transparent formulas. I make it a rule that no cell contains a hard-coded number unless it's an opening balance or a documented adjustment with a source reference. This makes auditing significantly easier because anyone can trace every figure back to its origin. I've lost count of how many times I've opened a template and couldn't figure out where a specific revenue number came from because someone hard-coded it somewhere in the middle of a complex calculation.
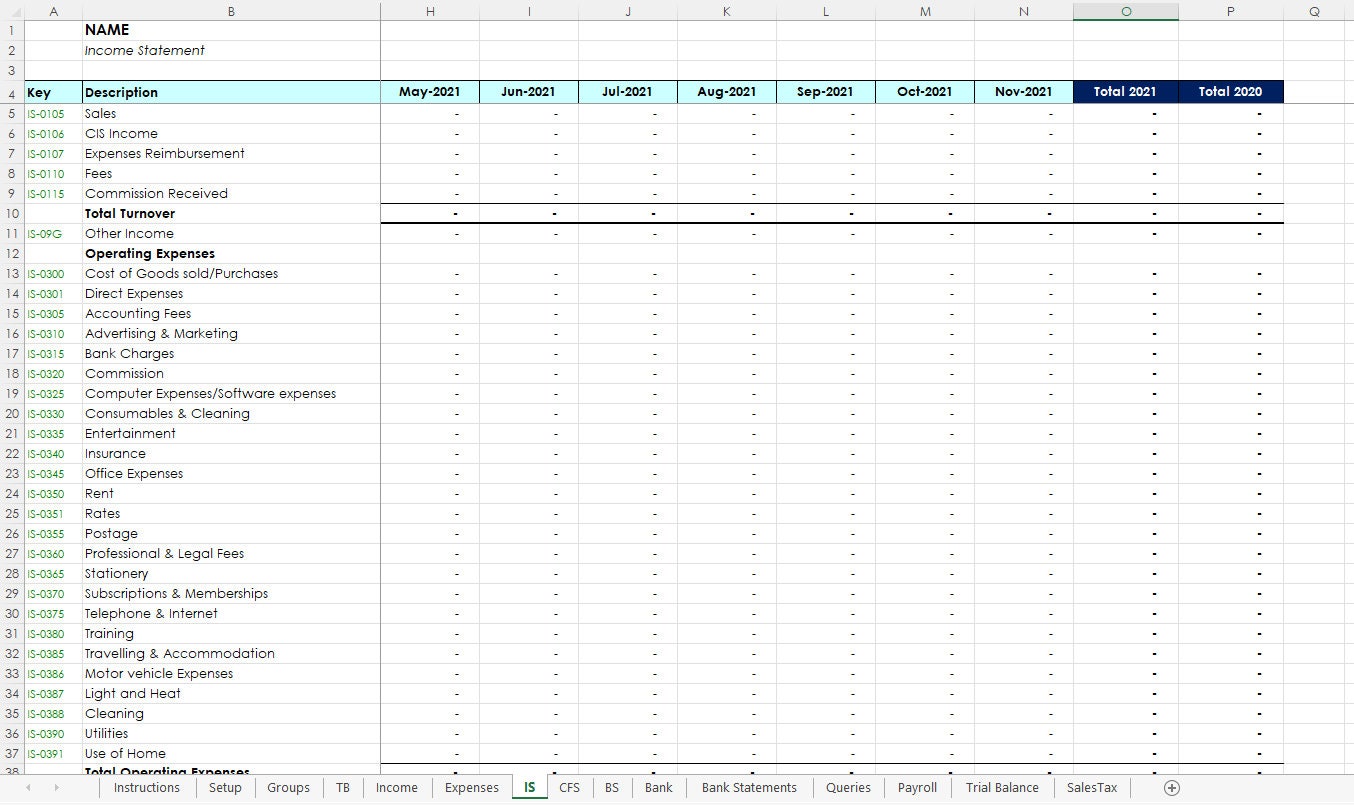
The template I distribute to clients usually includes a control log at the front. It records who entered each adjustment, when it was approved, and what the supporting documentation reference is. This isn't glamorous but it saved us during an audit last year when the reviewer asked for the rationale behind a significant accrual adjustment. We had the approval trail documented directly in the template instead of scrambling to reconstruct it from emails and paper.
When to stop optimizing and just use the template
There's a point where further customization adds more risk than value. If you're spending more than two days each month modifying your own template, you've probably over-engineered it. The template should handle normal business operations without requiring adaptation. If a specific transaction type consistently breaks your setup, add support for it and move on rather than redesigning the whole thing. I also recommend against chasing perfect automation. Partial automation with manual review checkpoints catches more errors than fully automated processes that run without scrutiny. A template that requires ten minutes of human review each month is more reliable than one that claims to be entirely hands-off. The completely automated ones always hide their errors in places you don't check until it's too late. The biggest advice I can give about building a Template For Accounting Yearly is to test it against a full year of actual data before relying on it for any real reporting. I've reviewed too many templates that looked flawless in theory and failed completely when real messy data hit them. Running a parallel test where you process actual transactions through your template alongside your existing system will reveal weaknesses you never would have spotted otherwise. The test period should cover at least one complete month-end close cycle, ideally longer if your business has seasonal variations that affect your accounting differently across months.


