Working With the Ten Principles Of Economics
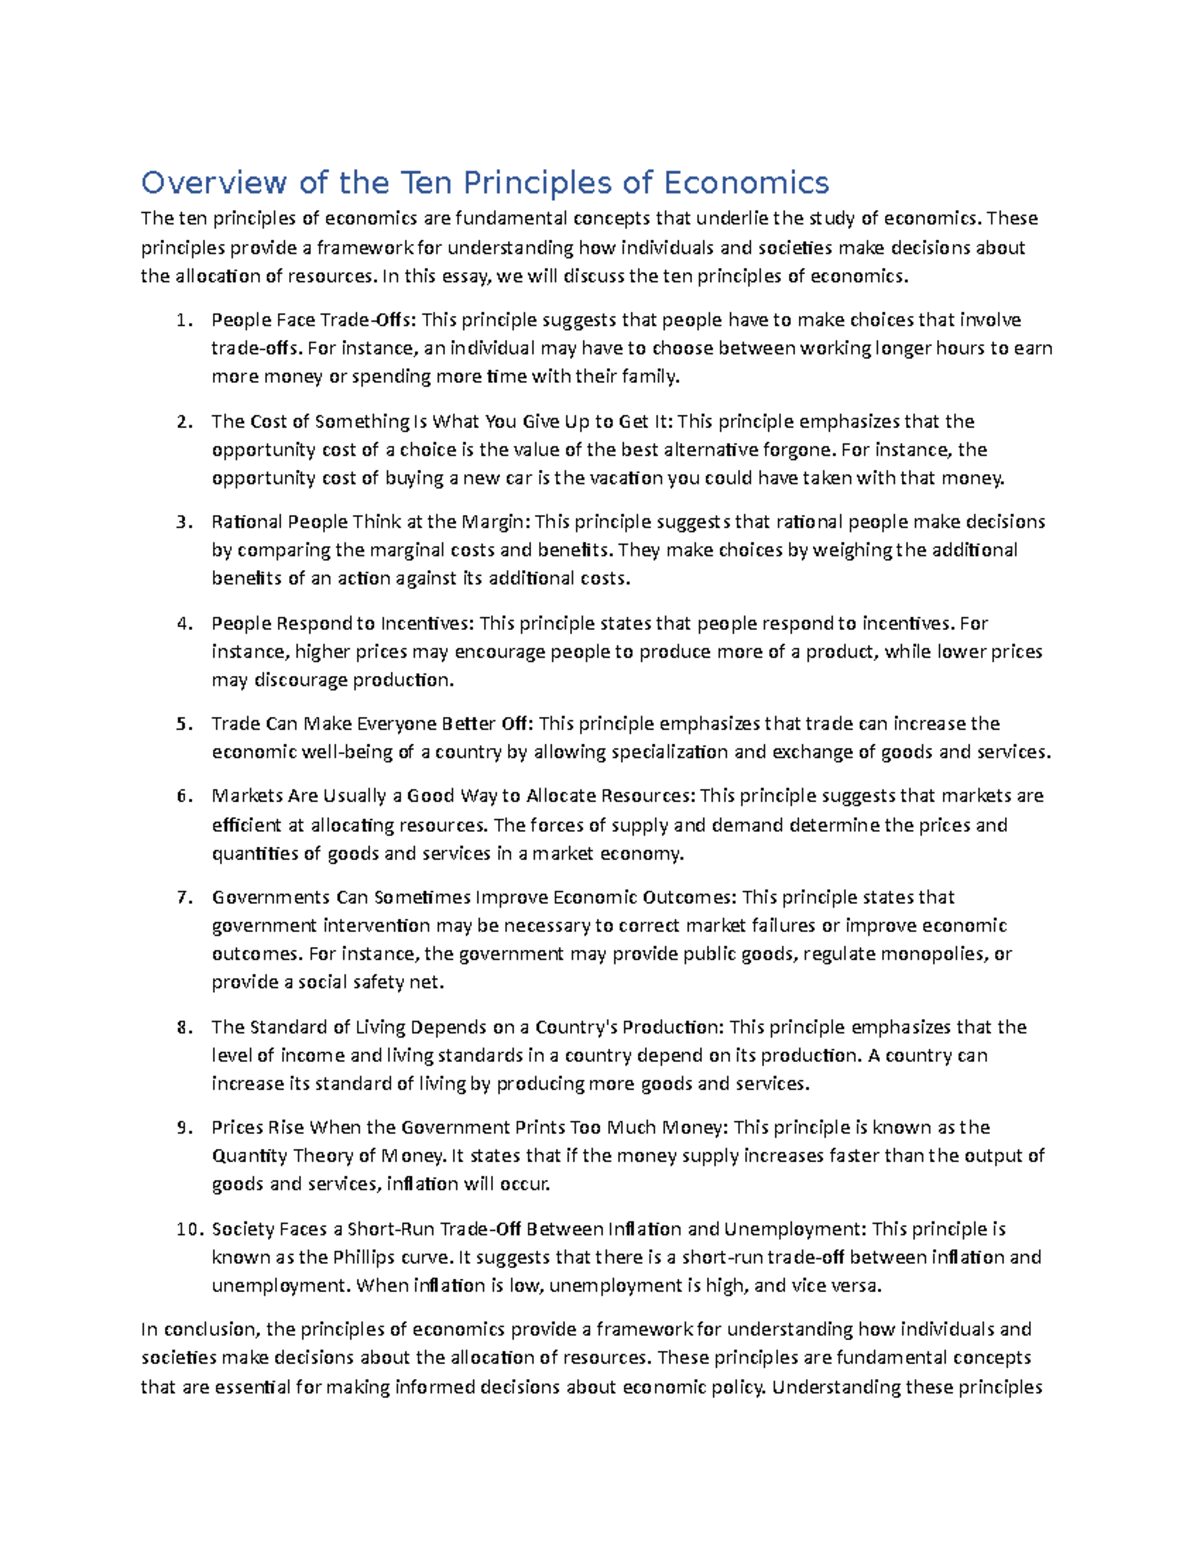
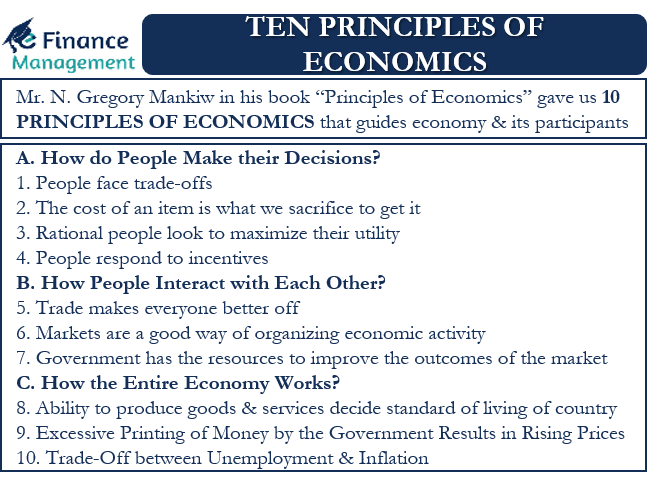
I keep seeing people treat these principles like they're laws of physics. They're not. They're patterns that hold up most of the time, under most conditions, until they don't. The first time I tried to apply opportunity cost to a real business decision where the costs weren't obvious in dollars, I sat there for two days trying to quantify something that really couldn't be quantified cleanly. What I ended up doing was just writing down every alternative I was giving up, ranking them by how much I cared about each one, and then noticing which option had the gap between what I gained and my second-best alternative. That was it. No spreadsheet. Just listing it out. The principles themselves are straightforward if you read them right. Here's how they actually land in practice, not how they look on a flashcard. Principle 1: People Face Tradeoffs. This is the boring one everyone skips. Every decision is a choice between competing goods. The trap people fall into is pretending some choices are free. They aren't. If you're building a product and decide to add a feature, that's time pulled from somewhere else. If you're running a country and decide to subsidize energy, that money comes from somewhere. I once worked with a team that claimed they could "just hire more people" to fix a bottleneck. They couldn't. Every hire changes the cost structure, the communication overhead, the management load. Tradeoffs don't care how much revenue you think you'll bring in.
Principle 2: The Cost of Something Is What You Give Up to Get It. Opportunity cost. Most people hear this and nod. Then they price things using only explicit costs. I've watched engineers build models that ignored the value of their own time because it wasn't on an invoice. That's not accounting, that's blind spot. When I was consulting on a supply chain problem, the obvious answer was to buy a new warehouse. The opportunity cost analysis showed we were tying up capital that could have been deployed elsewhere at a higher return. We didn't buy the warehouse. We renegotiated the contract with our existing third-party logistics provider and saved 40 percent over two years. Principle 3: Rational People Think at the Margin. This is the one that separates people who understand economics from people who memorized it. Rational people don't ask "should I do this or not." They ask "should I do a little bit more or a little bit less." Marginal analysis is about the next unit, not the average. When I was doing procurement work, everyone kept looking at average unit cost across a huge order. The marginal cost of the last 500 units was actually higher than making them in-house because of expedited shipping and quality checks. Ordering more seemed cheaper on paper. It wasn't cheaper at the margin. Principle 4: People Respond to Incentives. Write this on a wall somewhere. Incentives drive behavior more than stated goals ever will. I've seen compliance programs fail because the incentives rewarded speed over accuracy. You can train people all day about data integrity and it won't matter if their bonus depends on closing cases fast. I once designed a pricing model where the incentive structure accidentally encouraged customers to over-order. They got a bulk discount that kicked in at a threshold, so people ordered just enough to hit it even when they didn't need it. We lost margin on every transaction and gained nothing in volume. The fix was a tiered structure with softer breakpoints and volume rebates paid quarterly instead of upfront.
Principle 5: Trade Can Make Everyone Better Off. Not just countries. Individuals, teams, companies. Specialization based on comparative advantage isn't theory, it's just arithmetic. When I ran a small content team, one person was faster at writing but mediocre at editing. Another was slower at writing but exceptional at polishing. Putting them both on everything was wasteful. I assigned them roles based on where each had the bigger gap relative to their other skill. Output went up 30 percent in three months. The same logic applies to countries trading goods they produce relatively efficiently versus goods they'd have to pay more to produce domestically. Principle 6: Markets Are Usually a Good Way to Organize Economic Activity. This doesn't mean markets are perfect. It means they're usually better than the alternatives most people consider, which is often nothing at all or government action that hasn't been stress-tested. The invisible hand works until information asymmetry, externalities, or monopoly power show up. I've seen market solutions fail in local healthcare markets where one hospital dominated and had no competitive pressure. Prices went up, quality went flat. That's not an argument for replacing markets entirely. It's an argument for understanding when they break and what to do about it. Principle 7: Governments Can Sometimes Improve Market Outcomes. Antitrust enforcement, pollution regulation, public goods provision. These are legitimate interventions when markets fail. But the principle is easy to twist into an argument for intervention everywhere. It isn't. Government failure is real and often more persistent than market failure because the feedback loops are slower. I worked on a project where a well-intentioned price ceiling on rental units reduced supply more than it helped tenants. The landlords couldn't maintain the properties profitably. Some units went vacant. The people who needed housing the most ended up worse off. The principle doesn't say government should never act. It says act only where you have a clear case of market failure and a mechanism that won't make things worse.
Get the Full Details
Principle 8: A Country's Standard of Living Depends on Its Ability to Produce Goods and Services. Productivity. That's the word. Not resources. Not population. Productivity per worker. When I was analyzing regional economic data, the obvious correlation was between education spending and GDP. But the real driver was how efficiently that education translated into output. Places with decent schools but bad infrastructure, weak property rights, or high corruption had lower productivity than you'd expect. The principle is simple in isolation. In practice it's a mess of confounding variables. Principle 9: Prices Rise When the Government Prints Too Much Money. Inflation. The classic example is Zimbabwe or Weimar Germany, but the principle shows up in subtler forms too. I watched a local municipality print its way through a revenue shortfall by issuing bonds that the central bank essentially bought. Inflation wasn't obvious immediately. It showed up six months later as supply chain disruptions and rising input costs. The mechanism is straightforward: more money chasing the same goods. The timing and magnitude are harder to predict because velocity of money changes and other factors intervene. Principle 10: Society Faces a Short-Run Tradeoff Between Inflation and Unemployment. The Phillips curve. It's not a law. It's an observed relationship that held for a while and then broke down. Stagflation in the 1970s showed that tradeoff isn't stable. Expectations shift. Supply shocks matter. When I was studying labor market data, the inverse relationship between unemployment and inflation looked solid in some decades and nonexistent in others. The short-run tradeoff exists, but it's unreliable as a policy tool. Relying on it without understanding the underlying expectations dynamics will get you in trouble.
What People Miss
The Ten Principles Of Economics are taught as a list. They're meant to be read together. Each one modifies the others. Ceteris paribus assumptions hide in almost every statement. When you take them out of context and apply them to messy real-world situations, you need to know which assumptions are actually holding and which ones aren't. That's where most people trip up. Not in understanding the principles themselves but in knowing when the world has diverged enough from the conditions where those principles apply cleanly.