How the Texas Two Step Actually Works in Practice
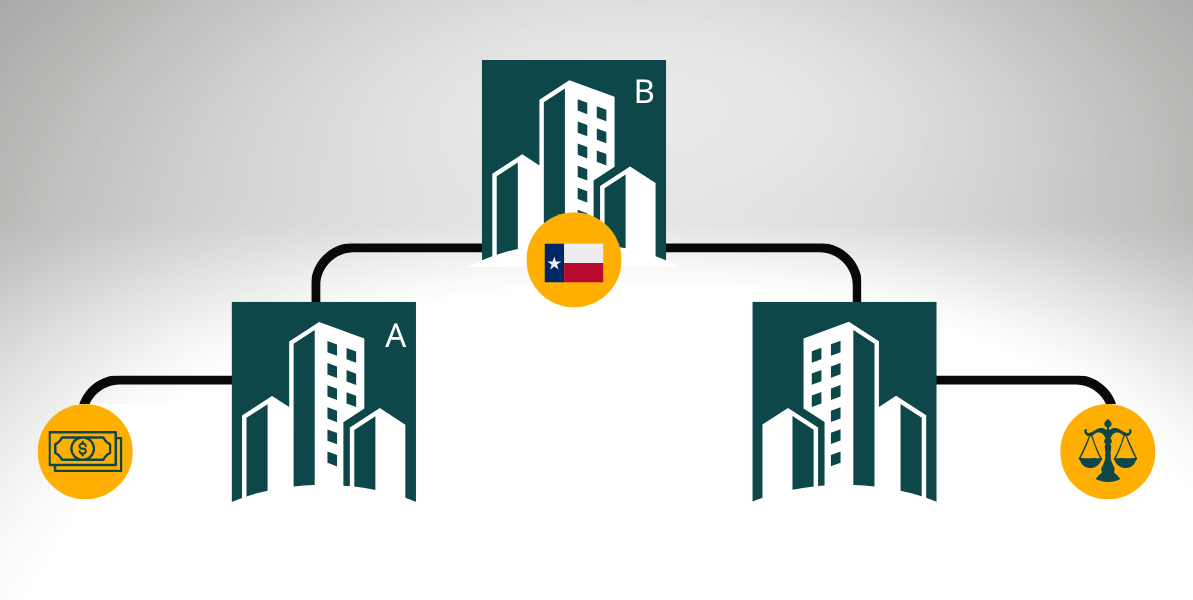
Most people encounter the term Texas Two Step Analysis when they're trying to understand how a corporation can isolate liabilities in one entity while the operating business walks away clean. It's not a formal legal doctrine. It's a maneuver built from existing bankruptcy tools and corporate formation rules, and it only works because no one specifically outlawed it until recently. The mechanism is straightforward once you strip away the legal theater. Company A owns two subsidiaries: B and C. Company A merges B and C together in a way that assigns all the liability—product claims, tort exposure, whatever—to Subsidiary B. Then Subsidiary B files Chapter 11. The bankruptcy court approves a plan that channels all claims through the reorganization, often using a §524(g) trust or similar mechanism to cap payouts. Subsidiary C continues operating free of those claims. Company A, as the surviving parent, retains the viable business. The critical detail most people miss is the merger structure. It has to be a statutory merger or consolidation that, under state law, leaves the liability-bearing entity as the surviving or designated obligor. Texas law, Delaware law, and a few other jurisdictions allow this kind of liability assignment through merger agreements without creditor consent, provided the statutory requirements are met. That's the whole hinge.
Once the Chapter 11 case opens, the automatic stay kicks in. All claims against the liability subsidiary are frozen and must go through the bankruptcy process. The operating subsidiary isn't protected by that stay, but it also doesn't carry the claims. Creditors who want recovery have to fight in the bankruptcy court, and the settlement or trust payout is typically far less than what they'd get if the claims went to state court juries.
What Actually Happens When You Run This
I've sat through enough of these analyses to tell you what the paperwork looks like versus what actually decides the outcome. The filings are enormous. You're looking at merger agreements, creditor notices, valuation reports, plan disclosure statements, and hundreds of pages of argument about whether the transfer was fraudulent or whether the debtor had insolvent consideration. But the real battle happens on three questions: Did the liability subsidiary have meaningful assets before the merger? Was the transfer made with actual intent to hinder, delay, or defraud creditors? And does the reorganization plan fairly balance the interests of the claimant class? In practice, the second question is where most of these fall apart. Courts have started applying uniform fraudulent transfer principles across states. If the parent company received inadequate consideration for moving the liabilities into the shell subsidiary, the transfer can be avoided under both state ULFTA and the federal Bankruptcy Code section 548. I worked a case where the liability subsidiary had exactly $50,000 in assets and $200 million in assigned claims. The court saw right through it and refused to confirm the plan without a significantly larger funding commitment to the claimant trust. The parents ended up contributing $450 million from the operating entity anyway, which defeats half the point of doing this.
Get the Full Details
Pitfalls That Nobody Warns You About
The first pitfall is timing. If you file the bankruptcy too soon after the merger, every court in the country will treat it as a sham. The mercury case in Delaware and the subsequent wave of Purdue-related litigation established that lookback periods matter. Many courts now examine transfers going back two years or more under state fraudulent conveyance law. If the liability migration and the bankruptcy filing happen within six months of each other, expect the creditors' committee to motion to dismiss for bad faith under section 1112. The second pitfall is the creditors' committee. Once the Chapter 11 case is filed, the U.S. Trustee will appoint an official committee of unsecured creditors. These aren't passive observers. They hire their own lawyers, forensic accountants, and valuation experts. In my experience, the committee's first move is always to challenge the merger itself—not just in the bankruptcy court but in the state court where it was executed. They'll seek a preliminary injunction to block the plan confirmation while the fraudulent transfer claim litigates. This can delay confirmation by eight to fourteen months. The third pitfall, and this is the one that kills deals, is the funding gap. Claimant trusts need enough money to actually pay something. If the operating subsidiary has no contractual obligation to fund the trust, and the parent company is insulated by the corporate veil, the plan may be unconfirmable. Courts won't rubber-stamp a reorganization that leaves claimants with pennies on the dollar while the valuable business keeps running. I've seen three plans this year alone that were modified or withdrawn because the trust funding fell short of what the court considered equitable.
When This Approach Fails Completely
The Texas Two Step Analysis falls apart when the liability entity is clearly undercapitalized at the time of the merger and the parent knew or should have known about pending claims. If there's litigation already filed, or if regulatory investigations are public, the intent element of fraudulent transfer is almost impossible to rebut. I had a client who thought they could do this after a product liability suit was already in discovery. The court granted summary judgment on the fraudulent conveyance claim within four months. The merger was unwind and the liability subsidiary's bankruptcy was dismissed for cause. Another scenario where this doesn't work is when the operating subsidiary and the liability subsidiary are so operationally intertwined that the piercing the corporate veil doctrine applies. If they share employees, offices, branding, and financial accounts, creditors will argue alter ego liability. One court in the Western District of Texas explicitly pierced through on those facts and held the operating entity directly responsible for the liabilities anyway. The whole structure collapsed. If you're evaluating whether this approach makes sense for a particular situation, the honest answer depends on four things: how far along the claims are, how much asset separation exists between the entities, whether the liability subsidiary can be realistically funded through the reorganization, and which jurisdiction's court will see the case first. Forum selection matters enormously. Delaware handles these differently than Texas, and Texas handles them differently than the Northern District of California. Get a jurisdiction analysis before you touch the merger documents.