What This Workbook Actually Does
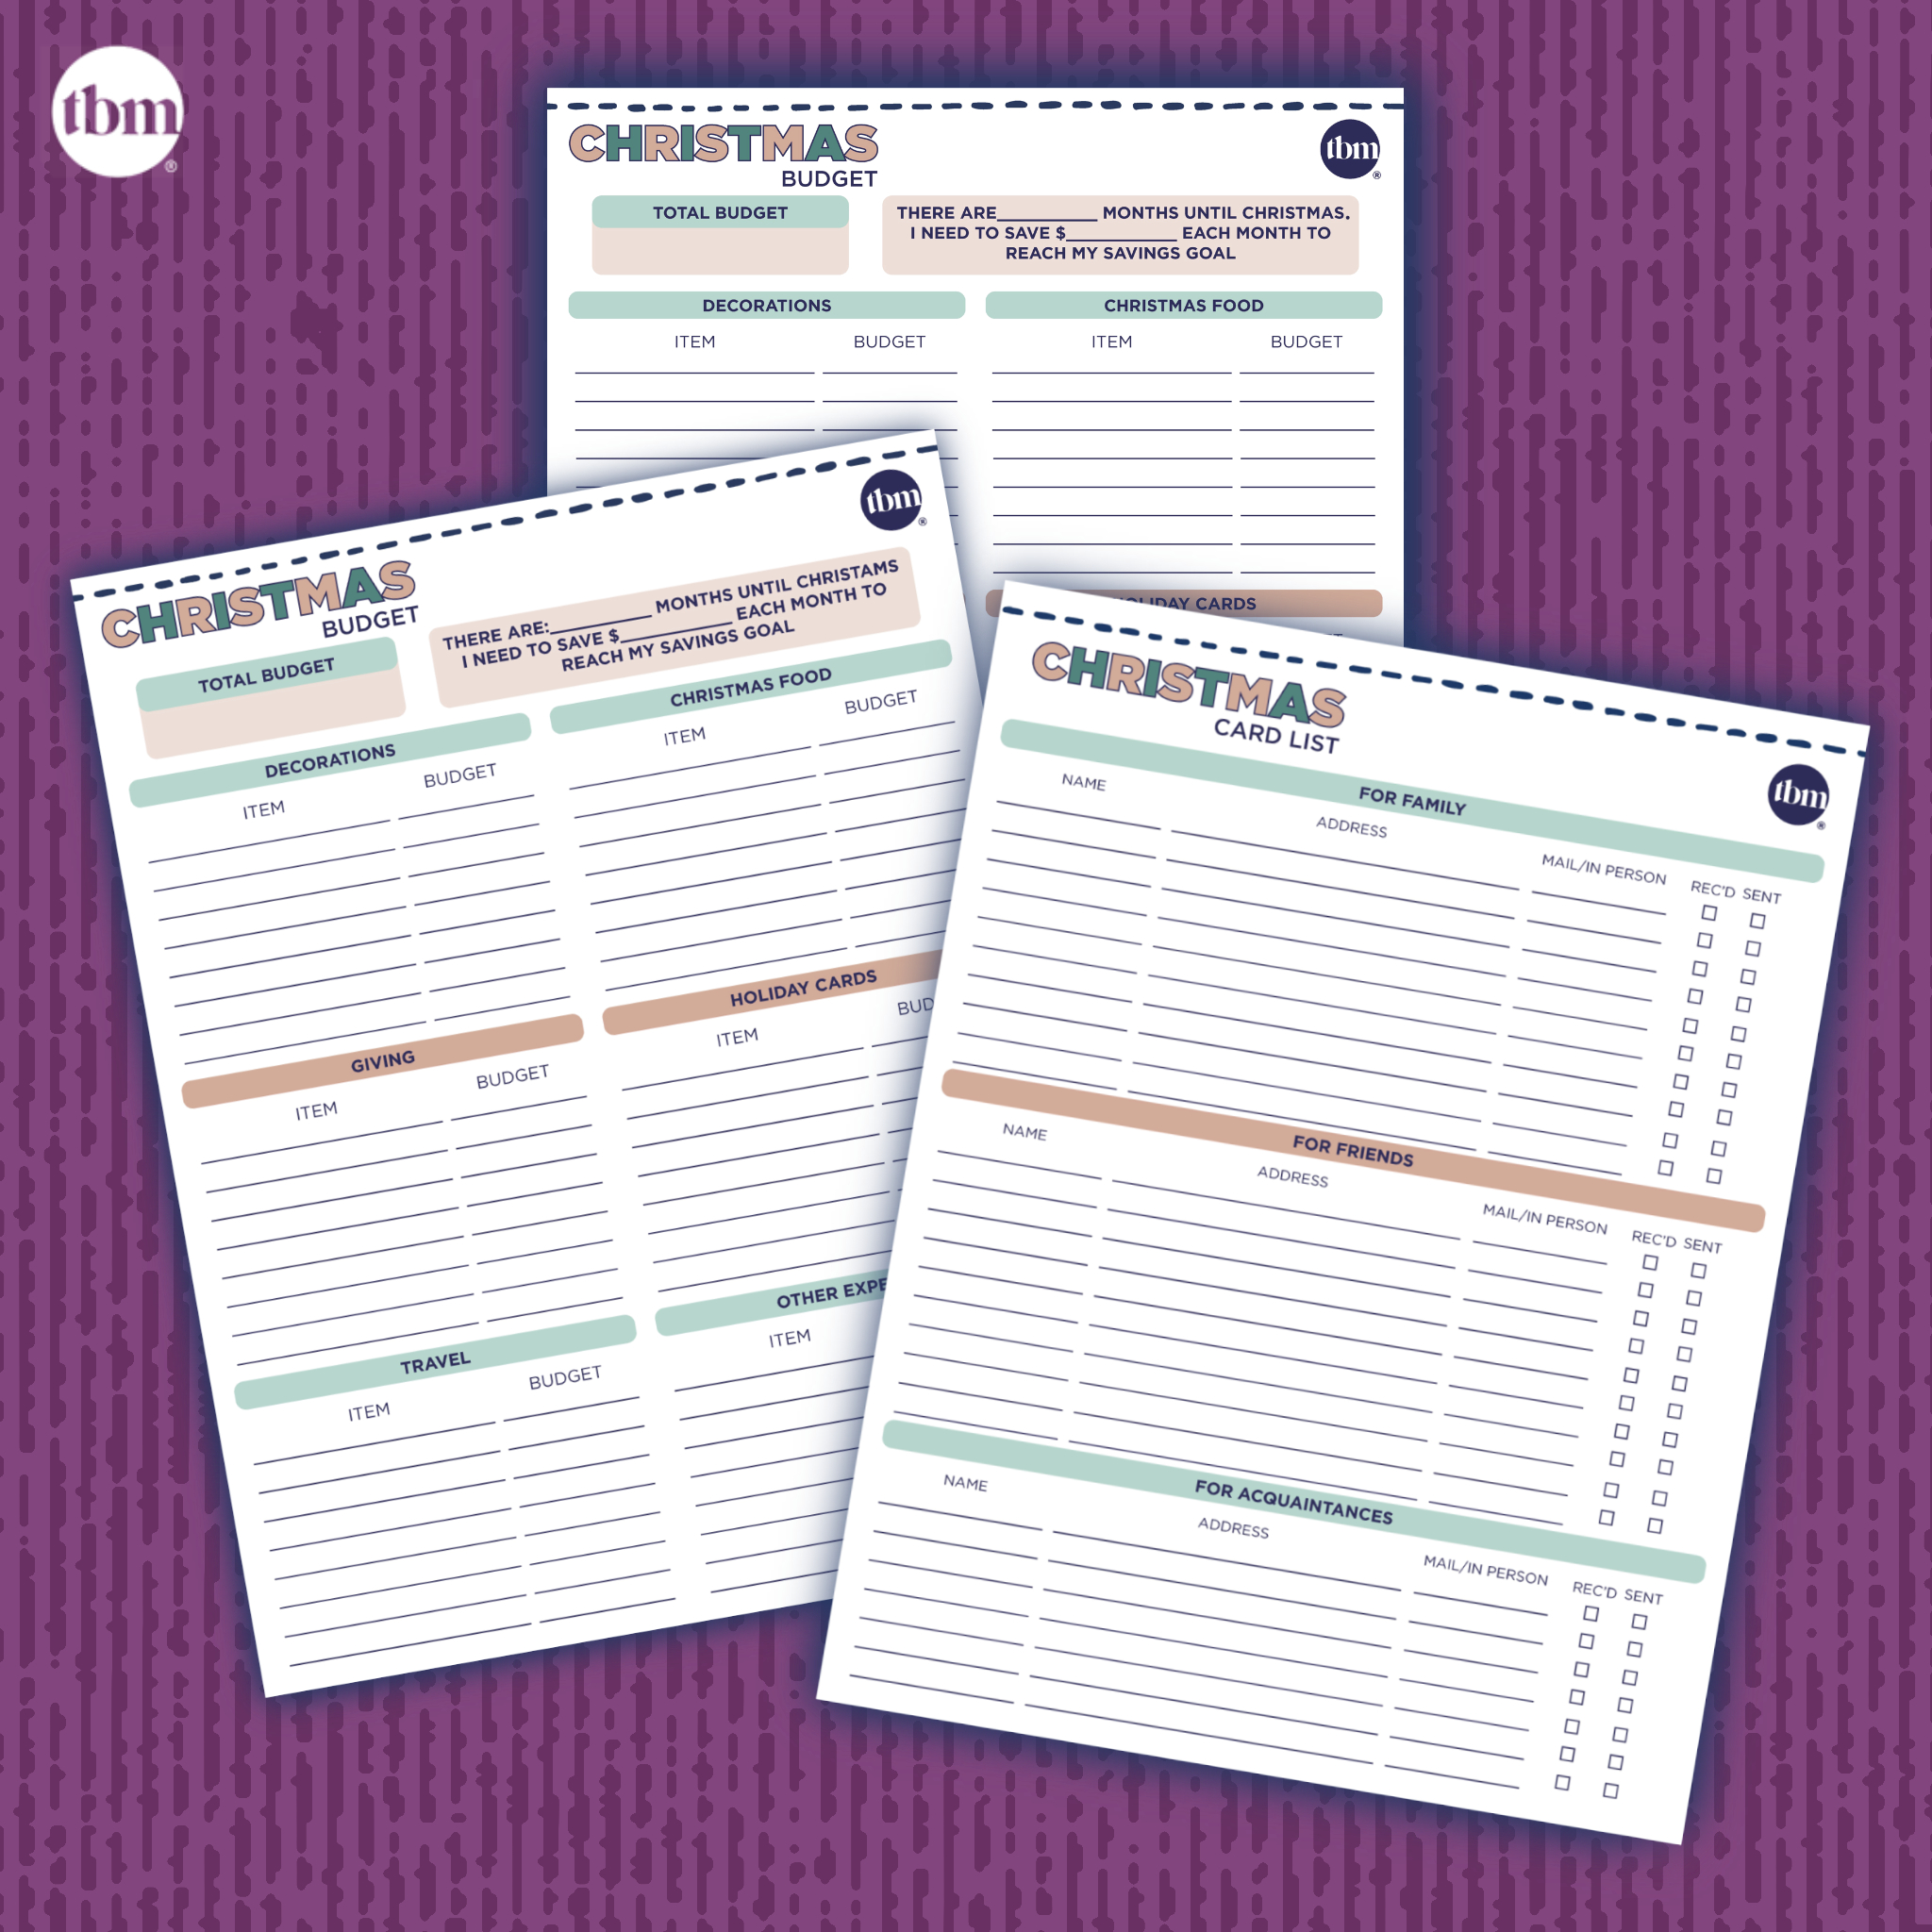
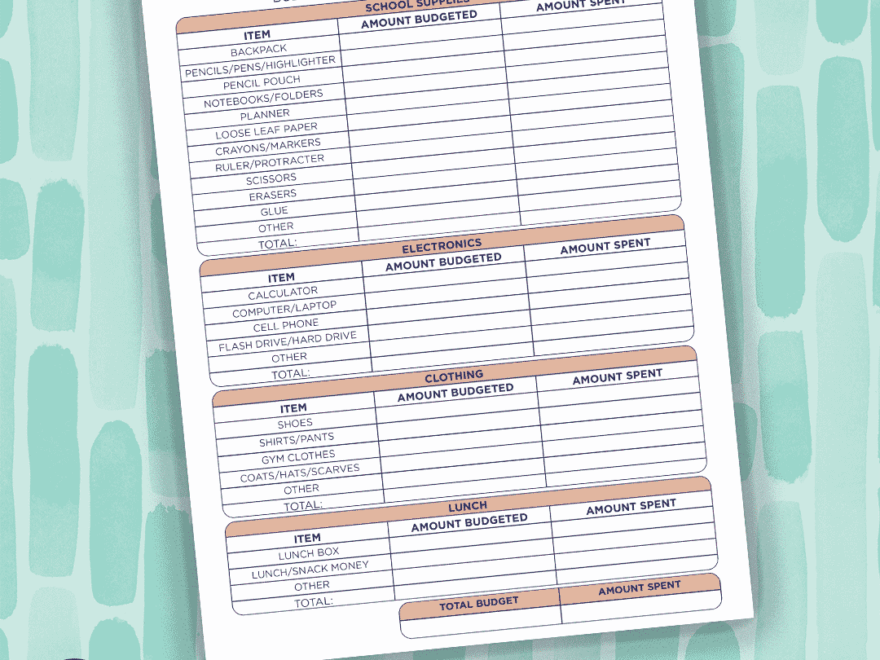
The Budget Mom Workbook Free is a downloadable Excel template that walks you through zero-based budgeting month by month. You assign every dollar a job before the month starts, then track what actually happens against what you planned. It's been around for years and is widely shared across personal finance forums. Amy created it, and she offers the free version with limited features compared to the paid version. The free tier covers monthly budgeting, savings goals, debt payoff tracking, and a couple of annual summary sheets. I've used versions of this workbook since 2019, and honestly it does exactly what it claims to do. The file layout is clean, the formulas are straightforward, and you won't need a finance degree to figure it out. You type in your income, you type in your expenses, and the sheet tells you how much is left over. That's it. The main thing people get wrong is they treat it like a set-it-and-forget-it tool. It's not. You have to open it every few weeks and update your actual spending, or the whole thing goes stale within a month. One edge case that tripped me up for a long time: the workbook has a built-in "savings goal" tracker that assumes you're saving one lump sum per category. When I started trying to track multiple goals at once, like a vacation fund and a car repair fund on the same sheet, the formulas started double-counting the totals. The workaround was simple but took me a while to find. You can copy the savings goal row, paste it below the original, and rename it. The macro references auto-update, and you just fill in your second goal. It's not documented anywhere in the help section, which is annoying.
How to Actually Use It Without Losing Your Mind
Start by downloading the file from the official Budget Mom website. Don't grab it from third-party sharing sites because the formulas can get corrupted during repackaging. Once you have the clean copy, open it in Excel, not Google Sheets. The macros don't run properly in Google Sheets, and a lot of the auto-calculation features will silently break. You'll notice things aren't adding up and spend two hours wondering why before you realize it's the platform. Here's the practical sequence I follow. First, put your household income into the income tab. If you and your partner both work, enter each paycheck separately. The sheet will aggregate them automatically. Second, go through your expense categories. The workbook groups them into standard buckets: housing, utilities, groceries, transportation, insurance, debt payments, entertainment, and miscellaneous. If your spending doesn't fit neatly into one of those, create a custom category in the notes section and reference it throughout the month. Third, set your savings targets. Enter the amount you want to save per month and the deadline. The workbook calculates the monthly contribution you need to hit that goal. The thing most people skip is the tracking tab. That's where the whole system falls apart if you ignore it. Every time you spend money, log it there. Not at the end of the month. Not when you remember. Immediately. I used to batch-enter my expenses on Sundays, and my numbers were always wrong because I'd forget small purchases. Cash transactions especially get lost. Now I keep a running note on my phone and copy it into the tracking tab Wednesday and Sunday. Takes about five minutes and keeps the data accurate.
Where the Workbook Falls Short
It doesn't sync with your bank. You have to enter everything manually. That's the biggest bottleneck, and it's the reason some people abandon it after three weeks. If you have fifteen credit card transactions a day and three checking accounts, manual entry is tedious. There's no Plaid integration, no import feature, nothing. You're on your own for data entry. The free version also lacks rolling yearly summaries. The paid upgrade adds a yearly overview that aggregates all your monthly data into one place. If you're the type who likes to look back and see trends across the year, you'll hit that wall quickly. The free workbook only shows individual months. You can work around it by printing each month and keeping a physical folder, but it's clumsy. Another limitation: the debt payoff section uses the avalanche method by default, which prioritizes high-interest debt first. If you're a snowball person and want to pay smallest balances first, the sheet doesn't have a toggle for that. I ended up calculating my snowball order in a separate spreadsheet and then copying the payment amounts into the workbook each month. It works, but it's extra steps the workbook should handle natively.
Get the Full Details

If your situation involves irregular income, like freelance work or commission-based pay, this workbook struggles. The income section assumes predictable monthly deposits. When your income varies by thirty percent from month to month, you'll spend half your budgeting time recalculating averages and adjusting categories. In that case, a spreadsheet with flexible income handling, maybe something like EveryDollar or a custom Google Sheet, would serve you better. The Budget Mom Workbook Free works best for households with stable, salaried income.
What You Should Know Before Downloading
The file is an Excel macro-enabled workbook. If your IT department blocks macros, it won't function fully. You may need to enable content when you open it, and some corporate computers will block that entirely. Keep that in mind if you're doing this on a work device. The design assumes you're budgeting as a household unit. Single-person budgets work fine, but if you're sharing finances with a partner who handles their own accounts separately, the sheet gets crowded quickly. I've seen couples divide the workbook into two halves, one per person, and merge the totals manually at month-end. It's not ideal but it's doable. One thing the workbook does well and people overlook: the envelope system mode. You can switch the tracking from account-based to envelope-based, meaning you allocate cash into physical envelopes and track against those instead of bank accounts. For households that prefer cash management, this is actually useful. I had a client who ran a small food truck and used the envelope mode exclusively for nine months. It kept her from overspending because she could physically see the cash running low.
Where to Get It
The Budget Mom Workbook Free is available on theofficial Budget Mom website. There's a direct download link on the free resources page. It's completely free, no email gate required for the basic file. The upgraded version costs around twenty dollars and adds the yearly summary, bank sync previews, and more detailed debt payoff calculations. For most people starting out, the free version is enough to build the habit. I'd recommend using it for at least sixty days before deciding whether the paid upgrade is worth it. A lot of people realize they don't need the extra features once they're comfortable with the system. One final note: save your own copy immediately after downloading. Rename it with the month and year, like "Budget_July_2025.xlsx." The original file has no version history, and if you accidentally overwrite a cell with a formula instead of a value, you'll lose that calculation permanently. I learned that the hard way in 2021 when a stray keystroke erased three months of savings data. A quick duplicate saved me from starting over.