Understanding the Building Blocks Of Accounting
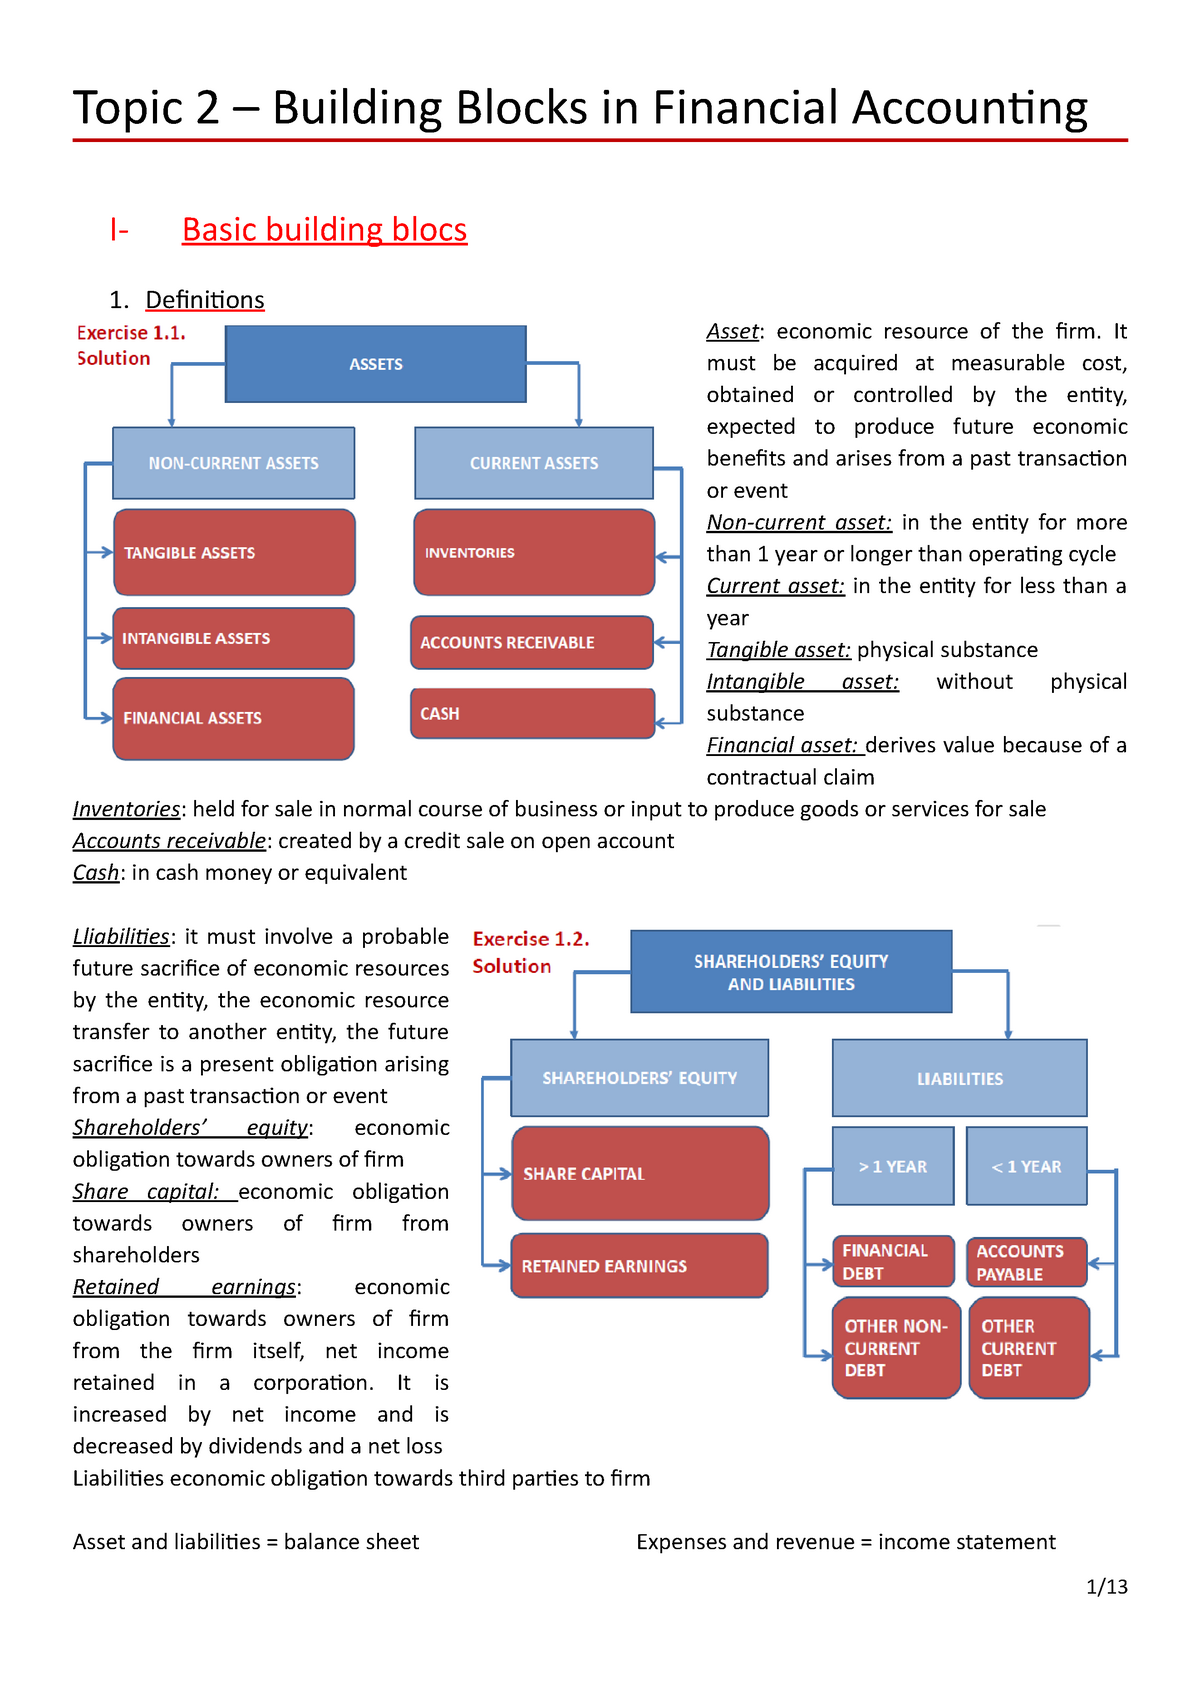
The Building Blocks Of Accounting sound simple when you first learn them, but they are where most small business owners and junior accountants make costly mistakes. I learned this the hard way around 2014 when I was reconciling a client's books and realized that a single misclassified expense had cascaded through three months of financial statements. The foundation of any accounting system rests on five core elements: assets, liabilities, equity, revenue, and expenses. That is the standard textbook answer, but here is what nobody tells you about how these actually behave in the real world. Assets are resources you own or control that have measurable economic value. Cash, accounts receivable, inventory, equipment, buildings. The tricky part is that not everything tangible qualifies as an asset under accounting rules. You cannot capitalize something just because it matters to your operations. If you pay rent for a warehouse, the building is not your asset. The right to use it for a period is what shows up on your balance sheet, and even then only under specific conditions. Most people conflate usefulness with ownership, and that mistake distorts every ratio you calculate afterward. Liabilities are obligations you owe to outside parties. Loans, accounts payable, accrued expenses, deferred revenue. The common pitfall here is timing. Accrued expenses exist whether anyone bothered to record them or not. A business might receive electricity service throughout March but not get the bill until April. The expense belongs in March. The liability belongs in March. Failing to accrue it inflates March profit and understates March obligations. I dealt with a manufacturing client who skipped quarterly accruals for their utility bills. Over two years, this created a phantom profit position of roughly forty thousand dollars that masked a real cash flow problem. When we caught it, the correction took three full days of backtracking through subsidiary ledgers.
Equity is the residual interest in assets after deducting liabilities. It represents what owners would theoretically walk away with if the company liquidated everything and paid every debt. Contributed capital and retained earnings make up the bulk of most equity sections. Equity does not move independently. It shifts whenever revenues, expenses, distributions, or capital transactions occur. This interdependency is where beginners lose track. A revenue increase boosts equity. A dividend payment reduces it. These are not separate events in the equity account. They are the mechanism by which equity changes. Revenue is income recognized when performance obligations are satisfied, not necessarily when cash arrives. The difference between cash basis and accrual basis accounting lives entirely in how you treat revenue recognition. Under GAAP, you recognize revenue when you have earned it and the amount is measurable and collectible. A consulting firm billing a client monthly for ongoing services recognizes revenue as the work is performed, regardless of invoice timing. This distinction matters enormously for financial analysis. Revenue tracked to delivery dates rather than payment dates produces a much more accurate picture of operational performance, especially for businesses with long cash collection cycles. Expenses are the costs incurred to generate revenue during a period. Matching principle means expenses follow revenue, not the other way around. If you sell a product in January, the cost of that product belongs in January expenses even if you ordered the inventory in November and will pay the supplier in February. The matching principle exists to prevent profit manipulation through timing. It sounds straightforward until you apply it to things like depreciation, prepaid insurance, or amortization of intangible assets. Those require estimates and judgment calls that vary between companies, and that variation is exactly why comparing financial statements across different organizations can be misleading.
The Building Blocks Of Accounting in Practice
Here is a specific edge case I encountered last year that illustrates how rigid textbook definitions break down. A client runs a SaaS business with annual subscription contracts billed upfront. They prepay twelve months of service. Revenue recognition over twelve months is straightforward in theory, but their payment processing fee structure charges a flat setup fee plus a percentage of each transaction. The setup fee relates to the contract as a whole, not to any single month of service delivery. I initially allocated that fee evenly across all twelve months as a reduction of revenue. The tax advisor pushed back and said it should be treated as a contract acquisition cost, amortized separately from revenue recognition. The difference mattered because it affected gross margin presentation and triggered different tax treatment. We ended up amortizing the setup fee over the contract term as an operating expense rather than a revenue contra-item. That changed reported gross margin by approximately seven percentage points annually. Neither approach was wrong, but the convention choice had real downstream effects on how investors read the financials. The double-entry system is the mechanical framework that keeps these five elements in balance. Every transaction affects at least two accounts. A debit always equals a credit. This rule is non-negotiable and it is what makes the accounting equation — assets equal liabilities plus equity — hold true after every single entry. What most people miss is that double-entry is not just a tracking tool. It is an error detection system. If your debits do not equal your credits, something is wrong. But the reverse is also true and important: balanced debits and credits do not guarantee correctness. You can make a perfectly balanced entry that records the wrong account, the wrong amount, or the wrong period. I have seen this repeatedly in quickbooks imports where a vendor payment got posted to the wrong expense category with both sides correct. The trial balance looked clean for months. The actual expense breakdown was completely wrong until a detailed GL review caught it. Chart of accounts design determines how usable your accounting system will be going forward. A poorly structured chart creates friction for every downstream process. Payroll reporting, tax filing, management reporting, audit preparation. I once inherited a system with over two thousand accounts because someone had created new accounts for every minor variation instead of using subcategories or descriptive naming conventions. Cleaning it up to approximately four hundred meaningful accounts reduced monthly close time from eleven days to three. That is not a theoretical improvement. That is a measurable operational change with real labor cost savings.
Get the Full Details
The most counter-intuitive thing about accounting fundamentals is that compliance and usefulness often pull in opposite directions. Financial statements prepared strictly for external reporting purposes tend to emphasize standardization and comparability. Internal management reporting needs relevance and timeliness. These goals conflict. Standard GAAP revenue recognition might smooth earnings across periods in ways that hide operational reality from a manager trying to make decisions. Similarly, historical cost accounting for fixed assets presents them at original purchase price minus accumulated depreciation, which can make equipment worth a fraction of its current replacement cost on paper while still showing full depreciation expense against current revenue. The resulting mismatch between book values and economic reality is by design, not oversight. Another nuance beginners consistently overlook is that the accounting equation itself is static at any given moment, but the transactions flowing through it are dynamic. Think of it like a balance scale that gets constantly rearranged. The scale must always level out, but what sits on each side changes continuously. This is why real-time bookkeeping is harder than periodic bookkeeping. A snapshot taken at month-end can be made to balance through adjusting entries. A snapshot taken mid-transaction might not reflect completed events yet. Most small business owners do not understand this distinction, which is why end-of-month reconciliations often reveal problems that were invisible during the reporting period. If you want to learn this material properly, there is no shortcut around the journal entry mechanism. Spreadsheets work fine for simple scenarios. Once you have intercompany transactions, multi-currency operations, lease accounting under ASC 842, or revenue recognition under ASC 606, spreadsheets stop being viable. QuickBooks handles basic small business needs adequately. Xero is comparable. For anything involving multiple revenue streams with different recognition patterns, you need either a dedicated subscription management tool integrated with your general ledger or a proper ERP module. NetSuite, SAP Business One, and similar platforms automate the harder parts but require significant implementation time and ongoing maintenance overhead.
The practical workflow for maintaining accurate books starts with daily transaction recording, weekly reconciliation of bank and credit card accounts, monthly closing procedures with adjustment entries, and quarterly review of financial statement accuracy against prior periods and budgets. Any deviation from this rhythm compounds. A missed week of reconciliation becomes a month of chasing receipts. A missed month of closing adjustments becomes a quarter of restating comparative figures. I advise businesses to treat reconciliation as the highest priority activity in the monthly cycle, not an afterthought. The other steps depend on it being complete first.
Summary
The five building blocks — assets, liabilities, equity, revenue, and expenses — form a system where every element constrains the others through double-entry mechanics. Understanding them at a definitional level is necessary but not sufficient. You need to understand how they interact during actual business transactions, how judgment calls affect their measurement, and how structural choices in your accounting system propagate through reporting. The work is tedious, the consequences of errors are real, and the gap between textbook clarity and practical messiness is significant. That gap is where experience matters.