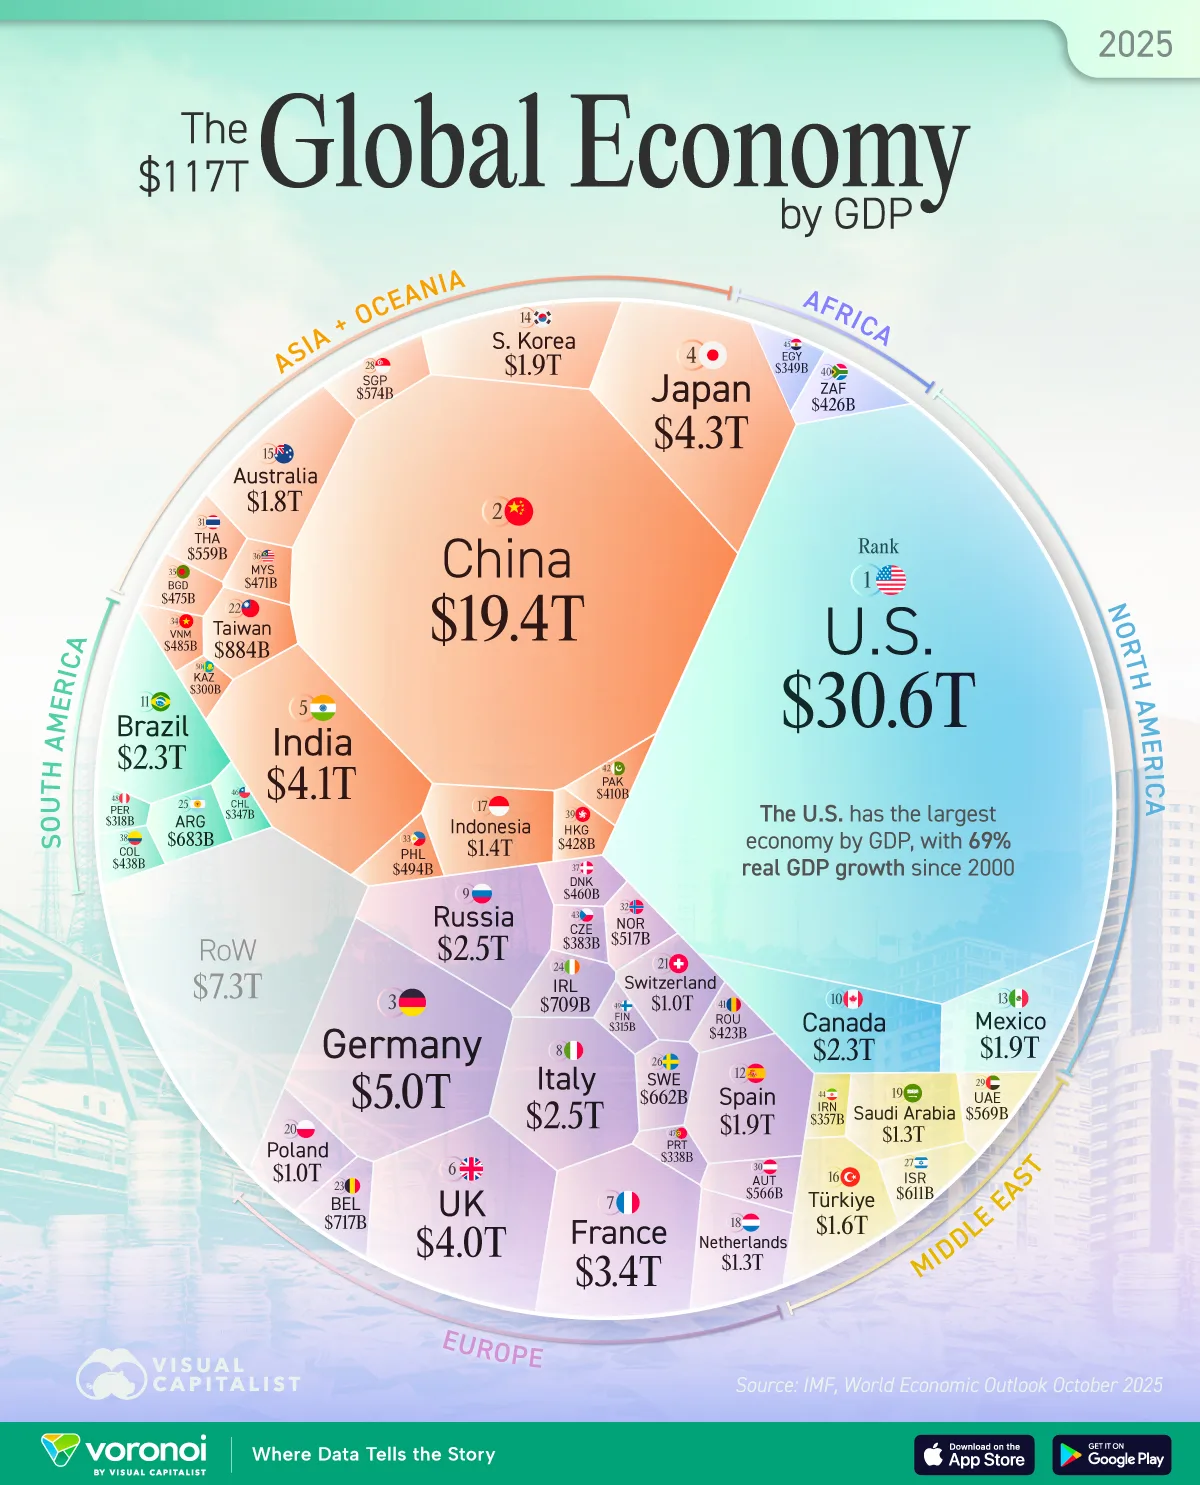
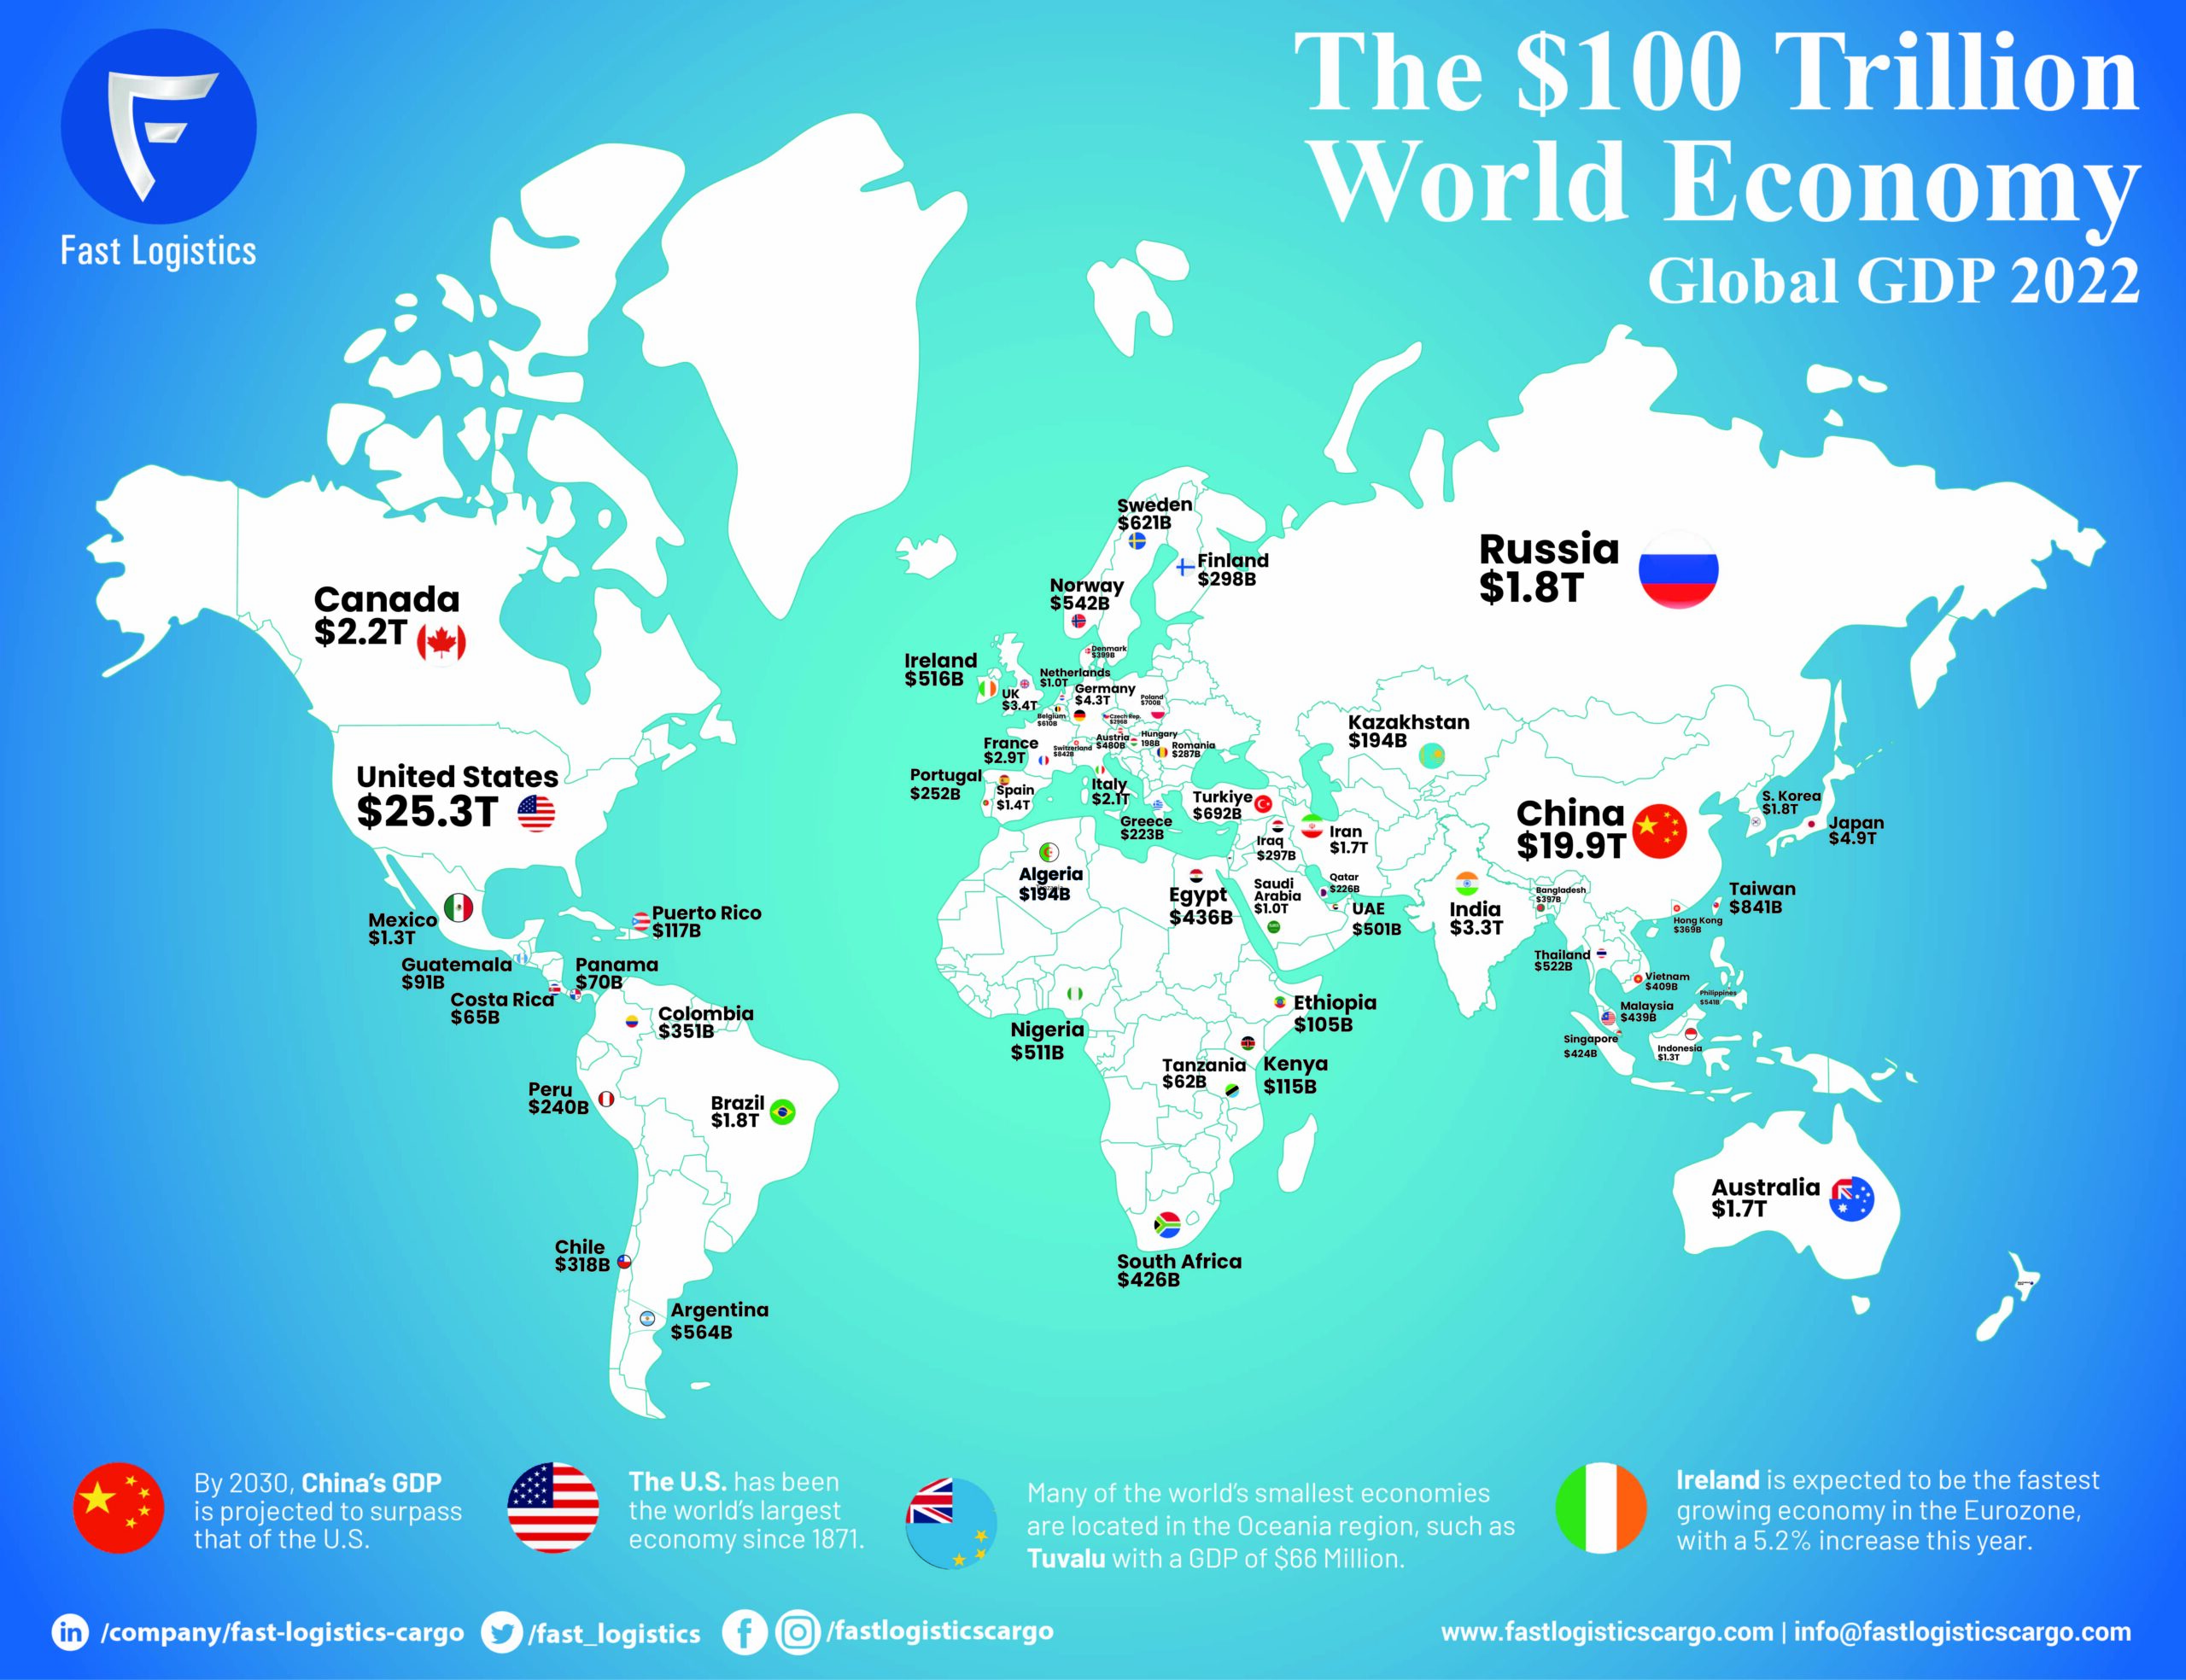
What Actually Drives Where Economic Activity Ends Up
The Geography Of The World Economy is not a single theory you can point at and say "here it is." It is a field that pulls from spatial economics, trade theory, economic geography, and development studies. The basic question is simple: why do factories cluster in Shenzhen, why does finance stay concentrated in London and New York, and why do entire regions stay poor despite everything they try. The answers involve agglomeration, transport costs, institutional quality, and path dependency. None of those are glamorous. They work that way. If you want to actually use this framework instead of treating it like a textbook concept, start with the Krugman-style new economic geography and work outward. Paul Krugman's 1991 paper on increasing returns and economic geography is still the foundational piece, even though he won a Nobel and everyone treats it like common knowledge now. The core mechanism is straightforward. When firms cluster together, they share input markets, specialized labor pools, and knowledge spillovers. That lowers costs. Lower costs attract more firms. The cycle compounds until some external factor breaks it. The problem most people miss is that agglomeration is not just about being near other firms. It is about being near the right firms, and only being near the right firms if your industry actually benefits from that proximity. A software startup in rural Kentucky gains almost nothing from being near other software startups compared to being in a city where you can hire experienced engineers without offering relocation bonuses. The geography of high-tech clusters exists because talent migration is sticky. People do not move on a dime. The same logic applies to almost every other sector, but the strength of the effect varies enormously.
The mechanics of economic geography in practice
Let me walk through how I actually use this when analyzing where industries end up. I start with transport costs, not because they are the only thing that matters, but because they set the baseline. Everything else layers on top. If you are moving bulk commodities like iron ore or grain, distance is everything. A mine in Western Australia supplies Asia because shipping that ore to Europe makes zero financial sense. Simple. If you are moving designer clothing or software code, distance matters far less, but other factors take over. Intellectual property protection, regulatory environments, and the thickness of the local talent pool become the binding constraints. The second layer is institutional quality. This is where most analyses fall apart. You will see papers claim that China became the factory of the world because of low labor costs. That is true, but incomplete. The real reason is that China built industrial zones with functional infrastructure, reliable electricity, customs clearance that actually worked, and supply chains so dense that a component manufactured in one province could reach an assembly line in another province in under a day. Vietnam is trying to replicate this model now. They are halfway there on labor costs. They are nowhere near the supply chain density. It takes decades to build, not years. I had a specific problem last year where a client wanted me to map out why a particular European manufacturing sector was collapsing despite high productivity. The standard models pointed to Chinese competition on price. That was part of it. The real cause turned out to be something far more boring and much harder to fix. The local logistics network had degraded because port automation projects were delayed by three years, labor disputes at regional terminals made trucking unpredictable, and the regional government kept changing subsidy programs so frequently that firms stopped planning beyond the next fiscal year. Productivity means nothing if you cannot ship goods reliably. I recommended a supply chain routing overhaul through Belgium and Northern Germany instead of the traditional routes. It cut lead times by roughly forty percent. The margin improvement from that was larger than any productivity gain they could have chased locally.
Counter-intuitive things nobody tells you about economic geography
The first counter-intuitive point is that remote locations sometimes outperform cities. I know that sounds wrong. But it is true for certain industries. Data centers, for example. They need cheap electricity, cool climates for natural cooling, and physical security. Those requirements often push them away from urban centers entirely. Iceland, Norway, and parts of Canada have become significant data center hubs precisely because they are inconvenient for everyone else. The same dynamic applies to certain types of mining and resource extraction. You go where the resource is, not where the people are. The second point is that economic geography has a memory problem. Regions that were once dominant do not stay dominant simply because they were dominant. But regions that develop thick ecosystems of suppliers, skills, and infrastructure do tend to persist in those roles even when conditions change. The American South stayed industrial even after the textile boom faded because the capital equipment, the trained workforce, and the supporting services were already embedded there. The Midwest auto industry persisted for decades after it lost its cost advantage because the entire supplier ecosystem was locked into that geography. That persistence is not always efficient. It is just inertia with a payroll. Here is another one that trips people up constantly. Free trade zones do not automatically create geographic economic convergence. They often do the opposite. When you establish a special economic zone in one location, you pull investment away from surrounding areas because firms prefer to concentrate rather than spread out. The zone becomes a magnet, not a starting point for regional development. Shenzhen was an exception, not the rule. Most special economic zones end up as isolated enclaves with weak connections to the broader economy. They create wealth in a small area and little else.
Get the Full Details
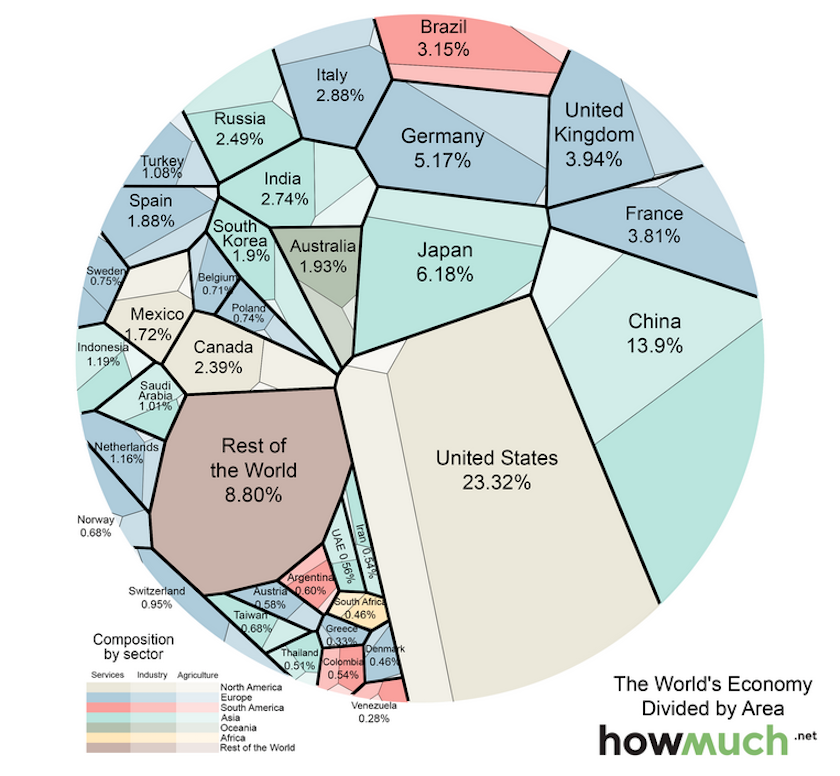
How to actually apply spatial economic analysis to a real problem
I run through a specific process when clients want to know where to locate operations or why their current location is failing them. The first step is always mapping the relevant input and output flows. Not just raw materials. Labor flows, capital flows, information flows, and waste flows all count. A food processing plant needs different geographic considerations than a semiconductor fab, and both need different ones than a call center. If you treat them the same, you will make costly mistakes. The second step is identifying binding constraints. In most cases, there is one constraint that dominates. For an agricultural exporter, it is usually cold chain logistics. For a tech company, it is talent availability. For a heavy manufacturer, it is often energy costs and transport access. Pinpoint the binding constraint before you do anything else. Everything else is secondary optimization. I spend about eighty percent of my analysis time just identifying which constraint is actually binding. The rest of the work is relatively mechanical once you have that right. The third step is scenario testing. Build three or four location scenarios and run them through cost models that include everything: land, labor, taxes, logistics, regulatory risk, currency exposure, and political stability. The numbers will tell you something, but the assumptions behind the numbers will tell you more. If your model says a location is cheaper but relies on optimistic exchange rate assumptions or incomplete infrastructure timelines, it is not actually cheaper. Adjust the assumptions to reflect reality. Then run the model again.
One thing worth noting explicitly is that this approach has real limitations. It works well for greenfield investments where you have time to evaluate options. It works less well when you are dealing with legacy operations, inherited supply chains, or political situations where the optimal geographic decision is impossible to implement. I have sat in meetings where the analysis clearly pointed to a different location, but the existing workforce, union contracts, or government relationships made relocation impractical. The model is a tool, not an oracle. It gives you directional guidance, not absolute answers.
Recommended resources for building actual competence in this area
The Geography Of The World Economy is broad enough that no single book covers it adequately. Krugman's work on new economic geography is essential reading, but it is dense. Paul Krugman himself wrote The World Today Is Not So Neoliberal as a more accessible entry point. For the trade side, Kevin O'Rourke's work on the global economy's history gives you the long arc that most modern analysts ignore. Alan Yates' Principles of Location Theory is useful if you want the technical underpinnings without getting lost in mathematical formalism. Data sources matter as much as theory. The World Bank's World Development Indicators, UNCTAD's trade databases, and the OECD's regional statistics are the baseline. The CEPII gravity database is probably the most useful tool for trade flow analysis if you can work with French academic databases. For sector-specific geographic data, the UN Industrial Development Organization publishes detailed breakdowns of manufacturing location that most people overlook. The practical takeaway is that understanding the Geography Of The World Economy requires treating it as a set of mechanisms rather than a set of facts. Agglomeration, institutional quality, transport costs, and path dependency interact in ways that resist simple formulas. The people who get it right are the ones who spend time understanding which mechanism is actually driving the outcome in any given situation. The rest of the time is spent checking their assumptions against what is actually happening on the ground.