Why Your LRAS Model Keeps Breaking in Real Policy Work
The Long Run Aggregate Supply Analysis Assumes That
The long-run aggregate supply framework assumes that all nominal variables—wages, prices, and input costs—adjust fully to any change in the money supply or aggregate demand. Output settles at the economy's potential, determined by technology, capital stock, and the natural rate of unemployment. Nothing else matters for the position of that vertical curve. I learned this the hard way. Around 2012, I was building a projection model for a regional economic development board. The standard textbook LRAS setup assumed capital accumulation and labor force growth would carry potential output along a clean trend line. We plugged in the numbers and ran three scenarios. Everything looked fine on paper until someone asked what happens if the natural rate of unemployment shifts. Turns out the Great Recession had changed it structurally for that region—construction sector collapse, mismatch skills, people dropping out of the labor force entirely. Our LRAS wasn't at the old potential anymore. We had to recalibrate the NAIRU estimate using state-level CPS data rather than relying on the national figure, which took about two weeks and completely shifted our baseline projections. The output gap we'd been forecasting was wrong by roughly 4 percent of state GDP. The assumptions are straightforward, but the application trips people up constantly. Here's what it actually assumes, and where the friction shows up.
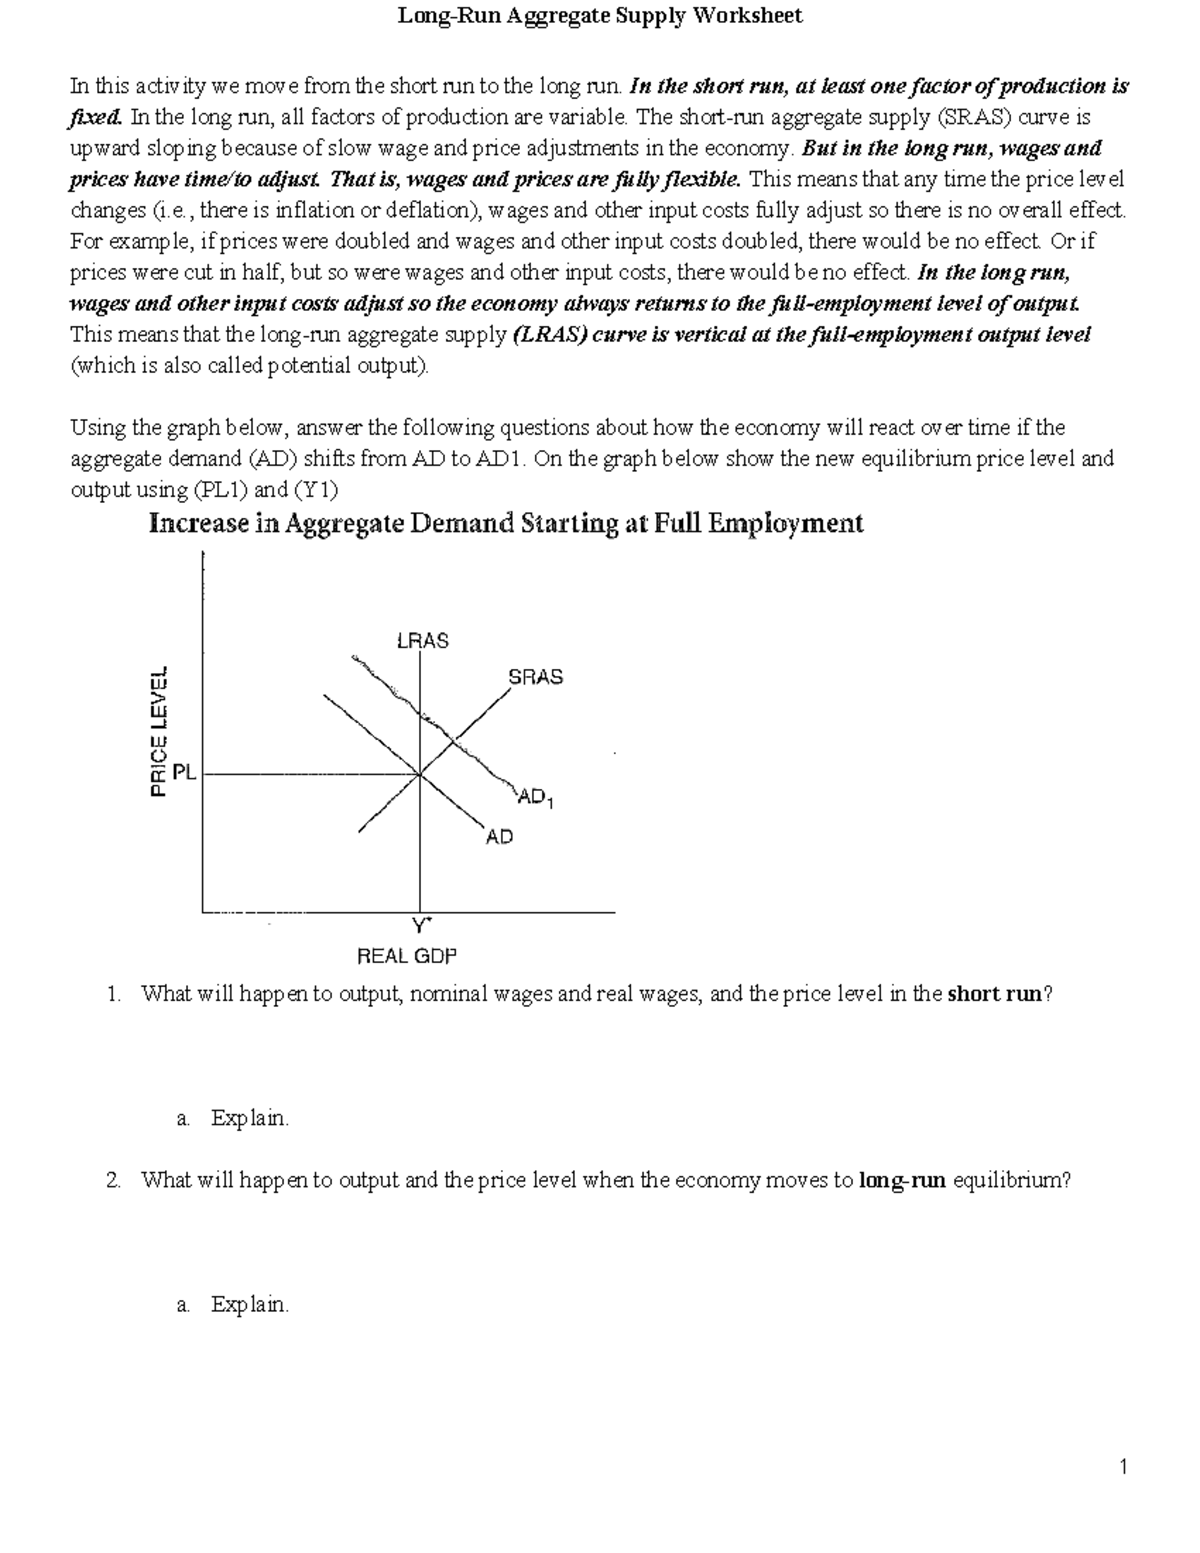
First, the model assumes full flexibility of prices and wages. This doesn't mean they adjust instantly—that's not realistic even in the long run. It means there are no binding nominal rigidities keeping the economy away from its potential over a multi-year horizon. If demand falls, wages and prices eventually drop enough to restore full employment. You don't need to believe this happens smoothly. You just need it to be true in the limit. Second, it assumes expected inflation equals actual inflation. This is the expectation-augmented Phillips curve side of the equation. Workers and firms have fully adjusted their expectations, so there's no surprise inflation driving temporary output deviations. Every contract, every wage negotiation, every pricing decision already prices in the current inflation environment. The economy isn't being fooled anymore. Third, it assumes the economy operates at potential GDP. This is output produced when all resources are employed at their natural rates. Capital is utilized at its normal capacity rate. Labor includes everyone who wants to work at the prevailing wage except the frictionally and structurally unemployed. It's not full employment in the sense of zero unemployment. It's the unemployment rate consistent with stable inflation—the NAIRU. This number moves. It's not a constant you look up once and never touch again.
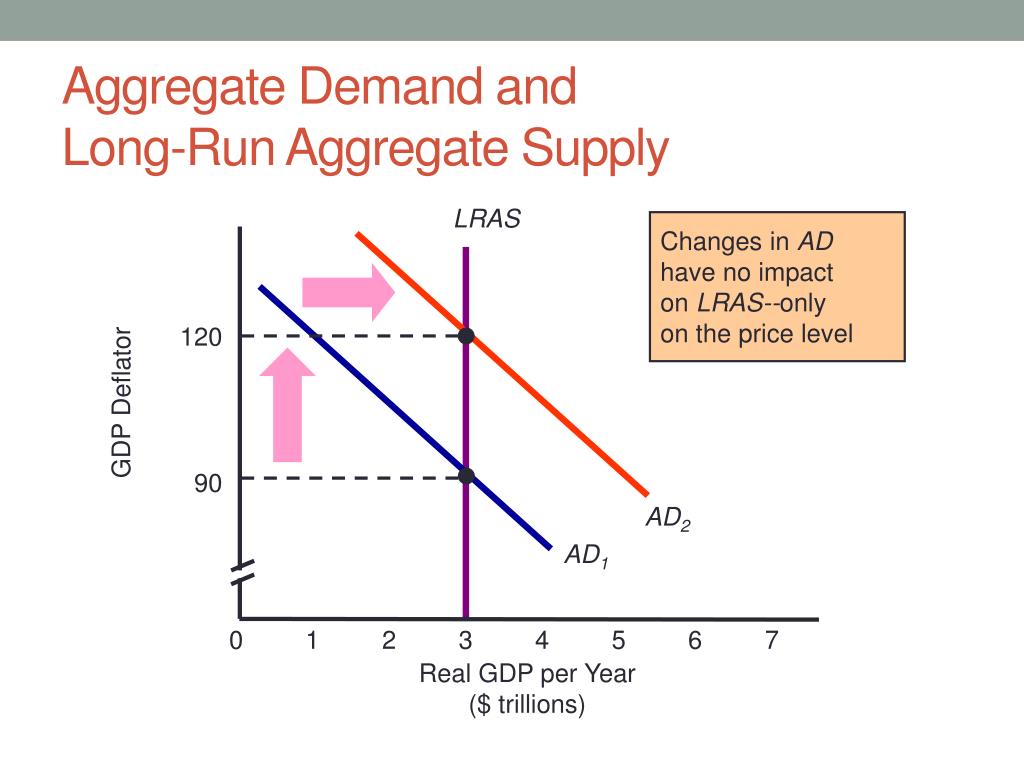
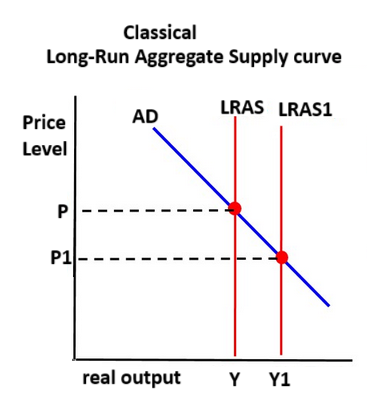
The LRAS curve is vertical because, under these assumptions, the price level has no effect on real output. If everything scales proportionally—wages, prices, input costs—then real production costs don't change. Firms have no incentive to produce more or less regardless of where the price level sits. Output is purely supply-side determined. Here's the part most introductory courses gloss over: the assumptions only hold if the economy has had enough time to adjust. "Long run" isn't a fixed duration. It's however long it takes for contracts to renegotiate, expectations to update, and capital to be reallocated. In practice, that can be anywhere from two years to a decade depending on the shock type. Policy advisors who treat the long run as a four-year election cycle misapply this framework consistently. Another thing beginners miss. The LRAS shifts, but not for the reasons you'd expect from demand-side thinking. An increase in aggregate demand doesn't shift the curve. A decrease in aggregate demand doesn't shift the curve. Only changes to the supply side do that—technology improvements, capital formation, labor force participation changes, institutional shifts like minimum wage laws or union density changes, and changes to the natural rate of unemployment. I've seen analysts incorrectly attribute LRAS shifts to fiscal stimulus, which is fundamentally a demand-side tool. It might affect potential output indirectly through infrastructure investment or human capital accumulation over many years, but that's a second-order effect, not a direct mechanism.
Get the Full Details

There's also a subtler issue with the assumption of full flexibility that comes up in practice. When you're modeling emerging economies or economies undergoing structural transition, the assumption breaks down in ways that matter. Argentina in the early 2000s, for example, had severe downward wage rigidity due to indexed contracts and strong labor institutions. Prices were also sticky because of dollarization pressures and inflation targeting regimes. The LRAS framework still works as a reference point, but the convergence to that vertical curve takes much longer and may involve significant output losses along the way. I once saw a model that ignored this and predicted a quick return to potential after a currency devaluation. It took roughly five years for the economy to re-equilibrate, not the eighteen months the standard model suggested. If you're working with this framework and need a practical starting point, here's the workflow I use. Get the potential output estimate from your central bank or statistical agency—most advanced economies publish these. Verify the natural rate of unemployment figure against recent labor market data, not just the official estimate, which tends to lag structural changes. Check whether the capital stock trajectory aligns with your time horizon. If you're projecting five years out and there's a major infrastructure program or a demographic cliff on the near horizon, adjust the capital and labor inputs before you even draw the curve. The framework has real limitations. It assumes a single equilibrium output level, but economies can have multiple potential outputs depending on which technological pathways they lock into. Path dependence matters, and LRAS analysis doesn't capture that. It also treats the natural rate of unemployment as exogenous, when in reality it's shaped by policy choices—active labor market programs, education policy, immigration rules, unemployment benefits design. You can't separate the supply-side story from the institutional one cleanly.
For policy work, I usually pair the LRAS analysis with a medium-run framework that accounts for gradual adjustment. The pure long-run picture is useful as a benchmark, but it's not actionable on its own. The adjustment dynamics—how fast expectations form, how flexible wages are in different sectors, whether hysteresis effects permanently lower potential output—those determine whether the long run is a helpful guide or a misleading abstraction. Hysteresis is the biggest risk. Prolonged demand shortfalls can damage the supply side through skill erosion, firm exits, and reduced investment. If that happens, your LRAS shifts left, and the recovery isn't just slow—it's to a lower plateau. I've seen this play out in Southern Europe post-2010, where the standard LRAS framework predicted a return to trend that never materialized because the potential itself had been eroded. The take-home isn't that LRAS analysis is useless. It's that the assumptions are more fragile than the textbook presentation suggests. The model works well for mature economies experiencing temporary shocks with intact institutions. It works poorly for economies in transition, after deep recessions with hysteresis, or when institutional changes alter the natural rate of unemployment without anyone updating the potential output estimate. Know which case you're in before you apply the framework.