What You Need to Know Before Diving Into the Chapter Breakdowns
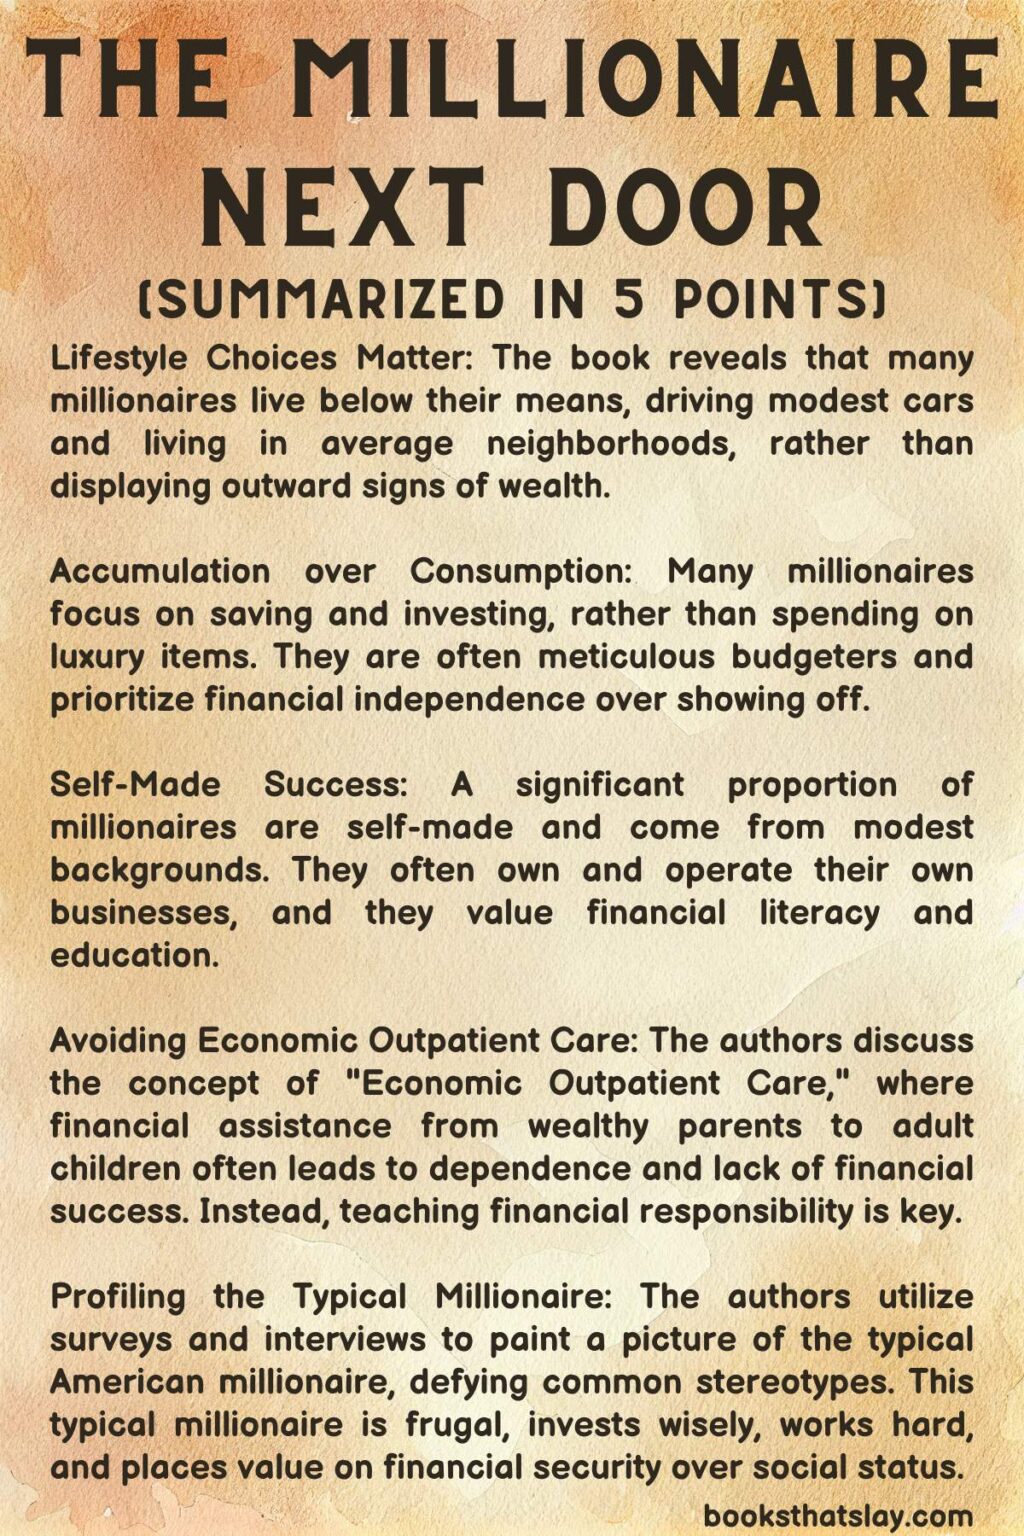
The Millionaire Next Door by Thomas Stanley and William Danko is one of those books that gets cited constantly in personal finance circles, but the chapter summaries most people find online are pretty shallow. They tell you "rich people save money" and "millions aren't what you think." The actual book has more texture than that, and if you're looking at summaries to decide whether to read it or to use it as a study tool, you should know what's actually worth your time and what isn't. I've spent years working with clients who came in after reading one of those glossy summary articles and then tried to apply the concepts without understanding the underlying framework. It doesn't work well. The book's methodology is built around specific metrics like the PA (Prodigious Accumulator of wealth) classification and the relationship between earned income, net worth, and age. Summaries usually skip all of that and hand you a couple of feel-good bullet points. That's why I'm writing this — to give you something closer to what the book actually says, with enough detail that you can use it.
The Millionaire Next Door Chapter Summaries
Chapter 1: The Millionaire Next Door introduces the central premise. Stanley and Danko found that most millionaires in America don't drive Mercedes, don't live in waterfront properties, and aren't CEOs. They run small businesses, work as professionals, and live in unglamorous suburban neighborhoods. The key insight here is that wealth accumulation is largely a behavior problem, not an income problem. Low spenders outperform high earners who blow through paychecks. The book gives specific data showing the average millionaire's net worth versus what people assume it is, which is a striking difference. I remember one client who refused to change his spending because his income was "only" $120,000 a year. He hadn't read past the first chapter of any version of this book. He'd been rich in potential for a decade already, just spending like he wasn't. Chapter 2: How to Spot a Millionaire walks through the indicators. The most practical tool from this chapter is the wasted income ratio. It's calculated by dividing your expected net worth by your actual net worth. Expected net worth is based on a formula using age and adjusted gross income. If your ratio is above 1, you're underperforming. Below 1 means you've accumulated more than the data suggests you should. This metric alone can be more useful than most people realize. A common mistake is treating it as a judgment tool rather than a diagnostic one. I've seen people get discouraged when their ratio was 1.8, but the real issue was a high mortgage on a property they didn't need. The number itself doesn't tell the full story without context. Chapter 3: Financial Genes covers the role of parents and upbringing. Stanley and Danko present data showing that parental behavior around money has a measurable impact on whether children become wealthy. It's not about how much money your parents had — it's about whether they modeled frugal behavior. The chapter argues that financial habits are transmitted culturally within families more than they are inherited through genetics. This is one of the more debated parts of the book, but the data is reasonably solid. The limitation here is that it doesn't account well for people whose parents were financially illiterate but who later developed discipline through other means. I worked with a client whose father was a compulsive spender and whose mother had no financial agency. She learned differently — through a mentor in her twenties who showed her how to track every dollar. The "genes" chapter would have painted her as a statistical loss, and she wasn't.
Chapter 4: How Did They Do It? gets into the mechanics. Most self-made millionaires in the book built wealth through business ownership or professional practice, not through stock market speculation or inheritance. The chapter breaks down career paths, spending patterns, and the role of marriage stability. One specific finding: millionaires are significantly less likely to be divorced than the general population. The chapter also notes that many of them changed careers at least once, often moving into fields with higher earning ceilings or more control over their time. This isn't always a success story. Some of the career switches came after painful failures. The book is honest about that, though summary articles tend to gloss over the difficulty. Chapter 5: The Biggest Threat to Your Wealth discusses consumption creep. This is the concept that as income rises, spending tends to rise with it unless deliberately resisted. The chapter calls this "keeping up with the Joneses," but the term predates the book. Stanley and Danko expand it into a broader category of social signaling through material display. The counter-intuitive part is that many high-income earners are actually poorer than lower-income savers because they're trapped in a lifestyle that requires constant spending to maintain. I saw this firsthand with a physician who made $450,000 a year but had less than $80,000 in investable assets. His house, cars, and club memberships consumed almost everything. He wasn't poor — he was just one paycheck away from being underwater, and he'd been making six figures for fifteen years. Chapter 6: Becoming a Millionaire offers practical guidance. The authors lay out specific steps: live below your means, avoid debt, invest consistently, and choose a spouse carefully. It sounds obvious because it is. The reason this chapter exists is that most people don't actually do these things, even though they know they should. The chapter includes case studies of real millionaires, which makes the advice concrete. One detail that gets overlooked in summaries is the emphasis on spouse selection. Stanley and Danko argue that marrying someone who shares your financial values is one of the highest-impact financial decisions you'll make. Divorce can erase decades of accumulation almost overnight. This is where the book gets practical rather than motivational.
Get the Full Details
Chapter 7: The Millionaire Mind concludes the main text with a look at the psychological profile of wealthy accumulators. The core traits identified are patience, discipline, and a willingness to forgo immediate gratification. The chapter also addresses the idea that many millionaires aren't extremely intelligent in a traditional sense — they're consistent. That distinction matters. It means the system is accessible to people who don't have exceptional earning power, only exceptional restraint. The downside of framing it this way is that it can understate the role of structural advantages, geographic luck, or access to capital, which the authors sometimes downplay.
How to Actually Use These Summaries
If you're going to work through this material, don't just read a summary and move on. The book's real value is in the data tables and the specific examples. Here's what I recommend. Read the chapters in order, but spend extra time on Chapters 2, 5, and 6. Those are the ones that translate directly into action. After each chapter, write down one specific behavior you could change based on what you read. Not a goal — a behavior. "I will stop leasing cars" is a behavior. "I want to be wealthier" is not. The wasted income ratio is the single most useful tool from the book. Calculate it yourself. Get your age, your adjusted gross income from the previous year, and your total net worth. The formula for expected net worth is approximately (age × adjusted gross income) divided by 10. Compare that to your actual net worth. If the gap is large, you have work to do. If the gap is negative, you're ahead of the curve. Track this number annually. It's more revealing than any investment return you'll see in a given year. One edge case the book doesn't address well is the impact of medical debt or unexpected catastrophic expenses on the wealth accumulation timeline. I had a client who was on track to hit a wasted income ratio below 1.0 within two years, then her brother had a stroke and she became his primary caregiver and financial support. Her net worth dropped by nearly forty percent in eighteen months. The book's framework assumes a relatively stable economic environment, which isn't always realistic. The workaround is to build a larger emergency fund than the standard three-to-six-month recommendation — I suggest six to nine months if you have dependents or variable income, and to treat that buffer as non-negotiable.
What the Book Gets Wrong
Several points from the book don't hold up well in the current environment. The housing market data is from the 1990s and early 2000s, when buying a modest home was far more accessible relative to income. Today, in many markets, the "buy a house and live in it for fifteen years" advice would leave someone significantly worse off than renting and investing the difference. The book also underestimates the role of student loan debt in delaying wealth accumulation for younger readers. A twenty-five-year-old today with $120,000 in student loans is starting from a completely different position than the sample population the authors studied. Another limitation is the narrow definition of success. The book treats net worth as the primary metric, which works for its purpose but ignores other dimensions of financial health like cash flow flexibility, optionality, and risk exposure. Someone with a high net worth but all of it tied up in an illiquid business is in a different position than someone with the same net worth in diversified, liquid assets. The PA classifier doesn't account for this. I recommend pairing the book's framework with a liquidity assessment before making any major financial decisions based on its conclusions. If you're looking for a resource that covers similar ground but with more current data, the work by Michael Kellogg on the Financial Independence movement offers a more modern take on the same principles. He builds on the foundations Stanley and Danko laid but accounts for student debt, gig economy income, and the realities of housing costs in 2020s America. The core message is the same — spend less than you earn — but the path is different now.
Final Notes
The book is worth reading if you're willing to filter out the nostalgia for an era that may not have been as favorable to wealth-building as the authors remember. The chapter summaries you find online will give you the gist, but they'll miss the nuance that makes the material actually useful. Do the math yourself. Calculate your wasted income ratio. Track it over time. And don't let anyone convince you that the only path to wealth is earning more. The book's central finding is still valid even if the specific numbers need updating.