The One Page Financial Plan That Actually Stays Useful
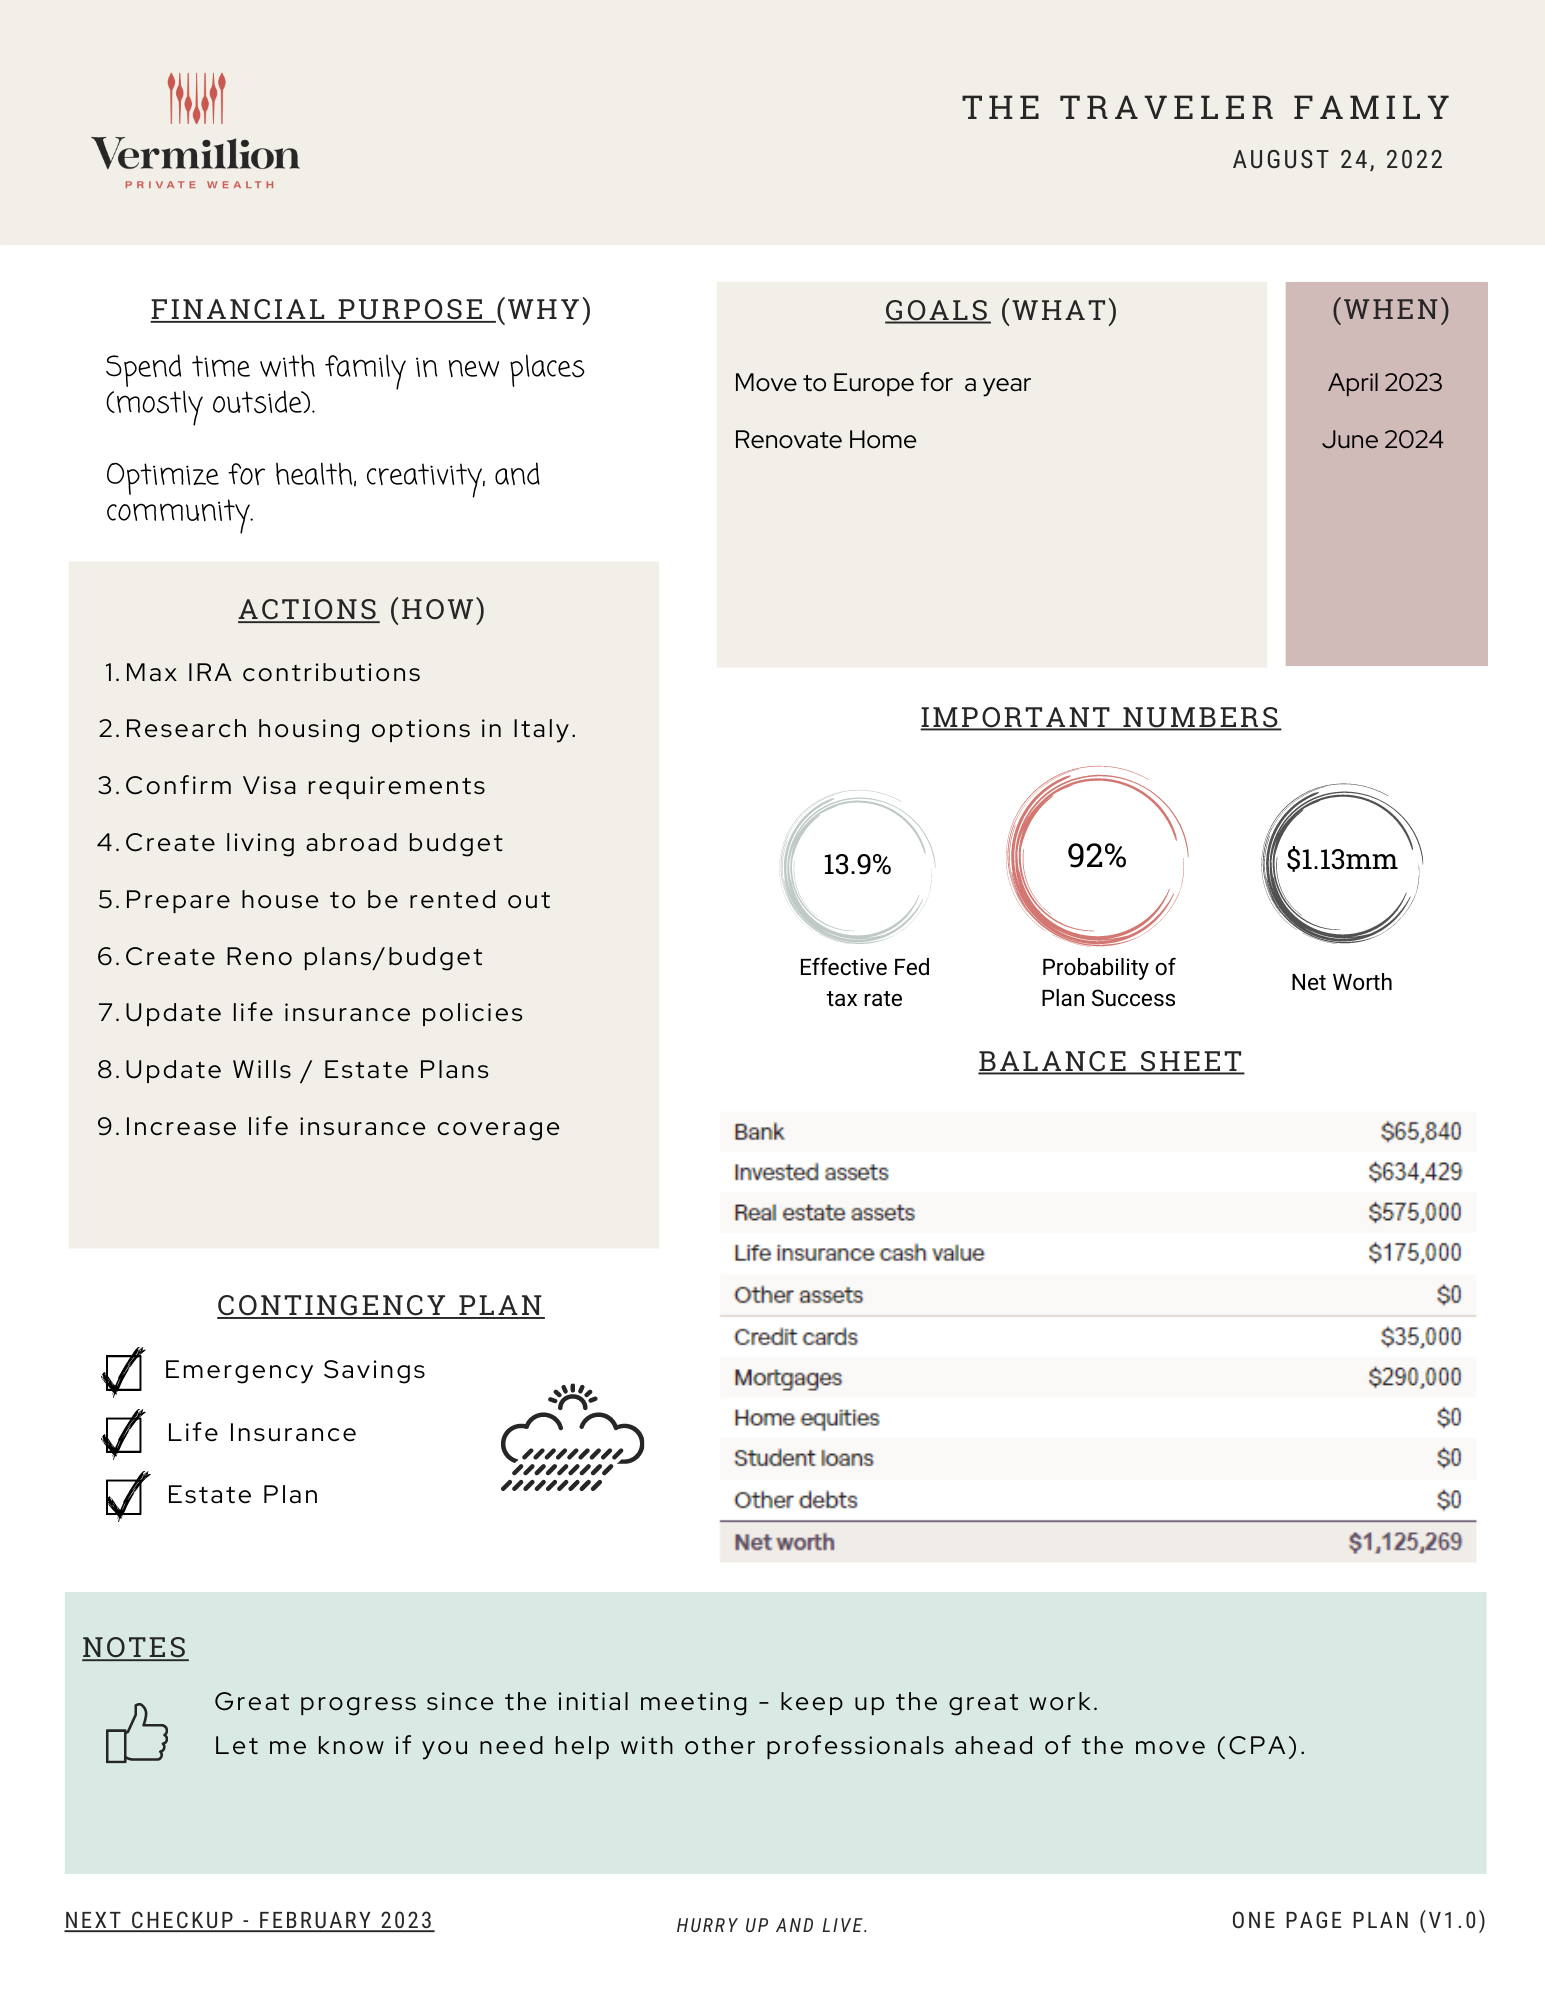
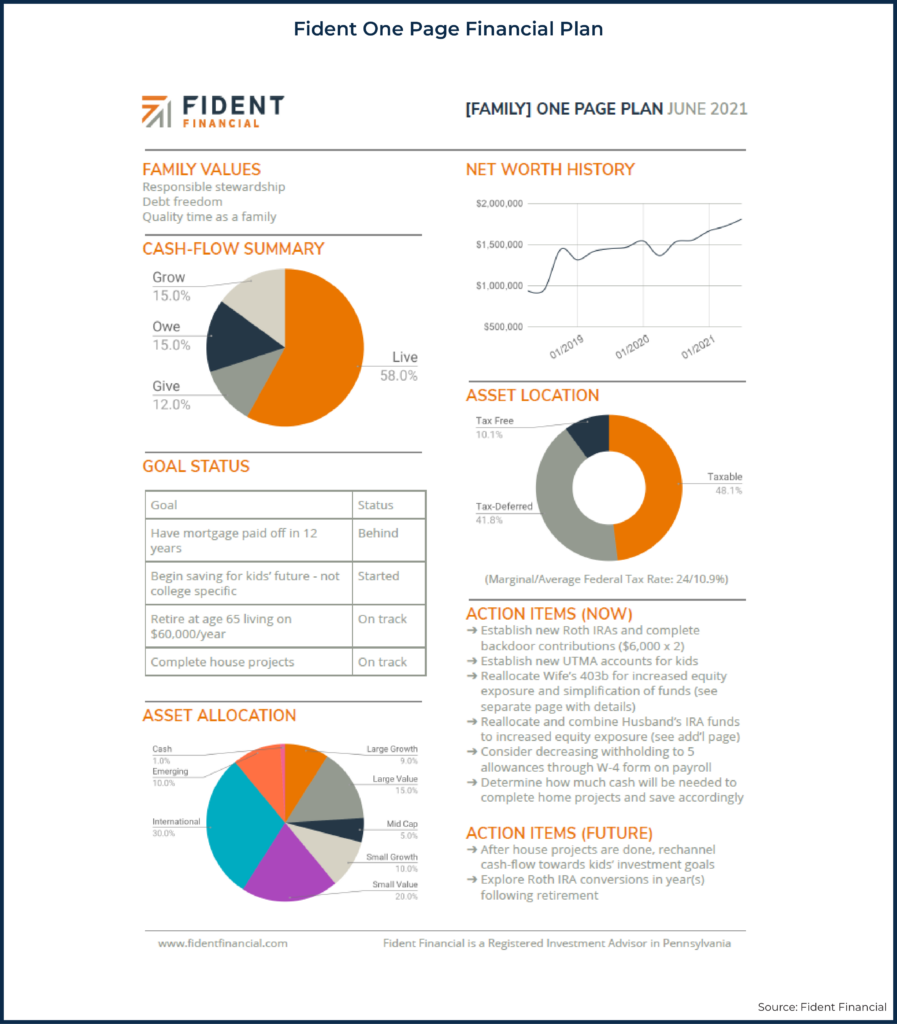
A one-page financial plan is a single-sheet summary of your net worth, cash flow, debts, and top financial goals. It replaces a multi-tab spreadsheet or a three-section Word doc with something you can actually look at. Most people who try this abandon it within six months because they treat it like a tax document instead of a living plan. I've spent over a decade watching clients build these, abandon them, rebuild them, and eventually find the right level of detail that sticks. The plan works because it forces prioritization. When you have one page, you can't hide behind a tenth tab of minor subscriptions you forgot about. You have to decide what matters enough to include, and that decision alone reveals your actual financial situation more clearly than any automated tool ever could.
Where to put the numbers and what goes on the page
Top third is net worth. Assets in one column, liabilities in the other, difference in a third. Don't round to the nearest thousand. Write $4,237.81 if that's what your checking account says. I had a client in 2019 who wrote "$12,000" for his emergency fund when it was actually $3,847.22 because he rounded down to feel better. The gap between what he thought he had and what he actually had caused him to skip a credit card payment that quarter. Exact numbers matter even when they're uncomfortable. Middle third is cash flow. Income on the left, fixed expenses on the right, variable expenses below that. Include debt minimums as a separate line. Track three months of actual bank statements before filling this in. I once saw a freelance client claim her monthly income was steady at $6,400. Her actual receipts showed $2,100 one month and $11,300 the next. She had been budgeting based on her best month, which meant she missed two rent payments before realizing what happened. Average it across twelve months, not six, and write the number down somewhere you'll actually see it. Bottom third is goals. Not vague ones like "save more" or "get out of debt." Specific goals with amounts and timelines. "$3,200 emergency fund by October" is different from "build an emergency fund." I use a simple format: goal, target amount, monthly contribution needed, target date. Anything without all three fields is a wish, not a plan.
Why one page fails and how to fix it before it becomes clutter again
The most common failure mode is that it becomes a scrapbook for every financial decision you ever make. Someone adds a side-hustle income line, then a new credit card payoff tracker, then a retirement projection, and suddenly it's two pages again. The fix is simpler than people expect: cut one section before adding another. If you add a new income stream, remove the oldest goal. The page is a discipline tool, not an archive. Archives belong in your spreadsheet or your financial planner's file. The one-page plan is for daily reference. Another failure point is treating it as a static document created once a year. The plan loses value after about sixty days because life changes faster than annual reviews capture it. I recommend updating it every ninety days with a fifteen-minute session. Pull your bank statements, recalculate the top third, adjust the middle third based on any new bills or income changes, and update the bottom third goals. That's it. The whole process takes about twenty minutes if your accounts are organized. It takes about forty-five if you're still logging into three different banking portals to find numbers.
Get the Full Details

The counter-intuitive part most beginners miss
Most people think the one-page plan is about accuracy. It's not. Accuracy is important but secondary. The primary function is visibility. A plan that's slightly inaccurate but sits on your desk and gets looked at daily is far more effective than a perfect plan that lives in a folder you open twice a year. I've watched clients with $127 in untracked subscription charges on their statements ignore a $4,000 net worth discrepancy because the discrepancy was hidden in a spreadsheet they stopped using. The one-page plan prevents that by design. It forces everything into view. The second thing people miss is that the plan works best when it's intentionally incomplete. Leave out the $47 gym membership you cancelled six months ago and forgot to remove. Leave out the stock account you haven't logged into since 2021. Incompleteness creates cognitive dissonance, and that dissonance is what drives you to either add the missing piece back in or acknowledge that it doesn't matter anymore. Either outcome is progress.
When this method breaks down completely
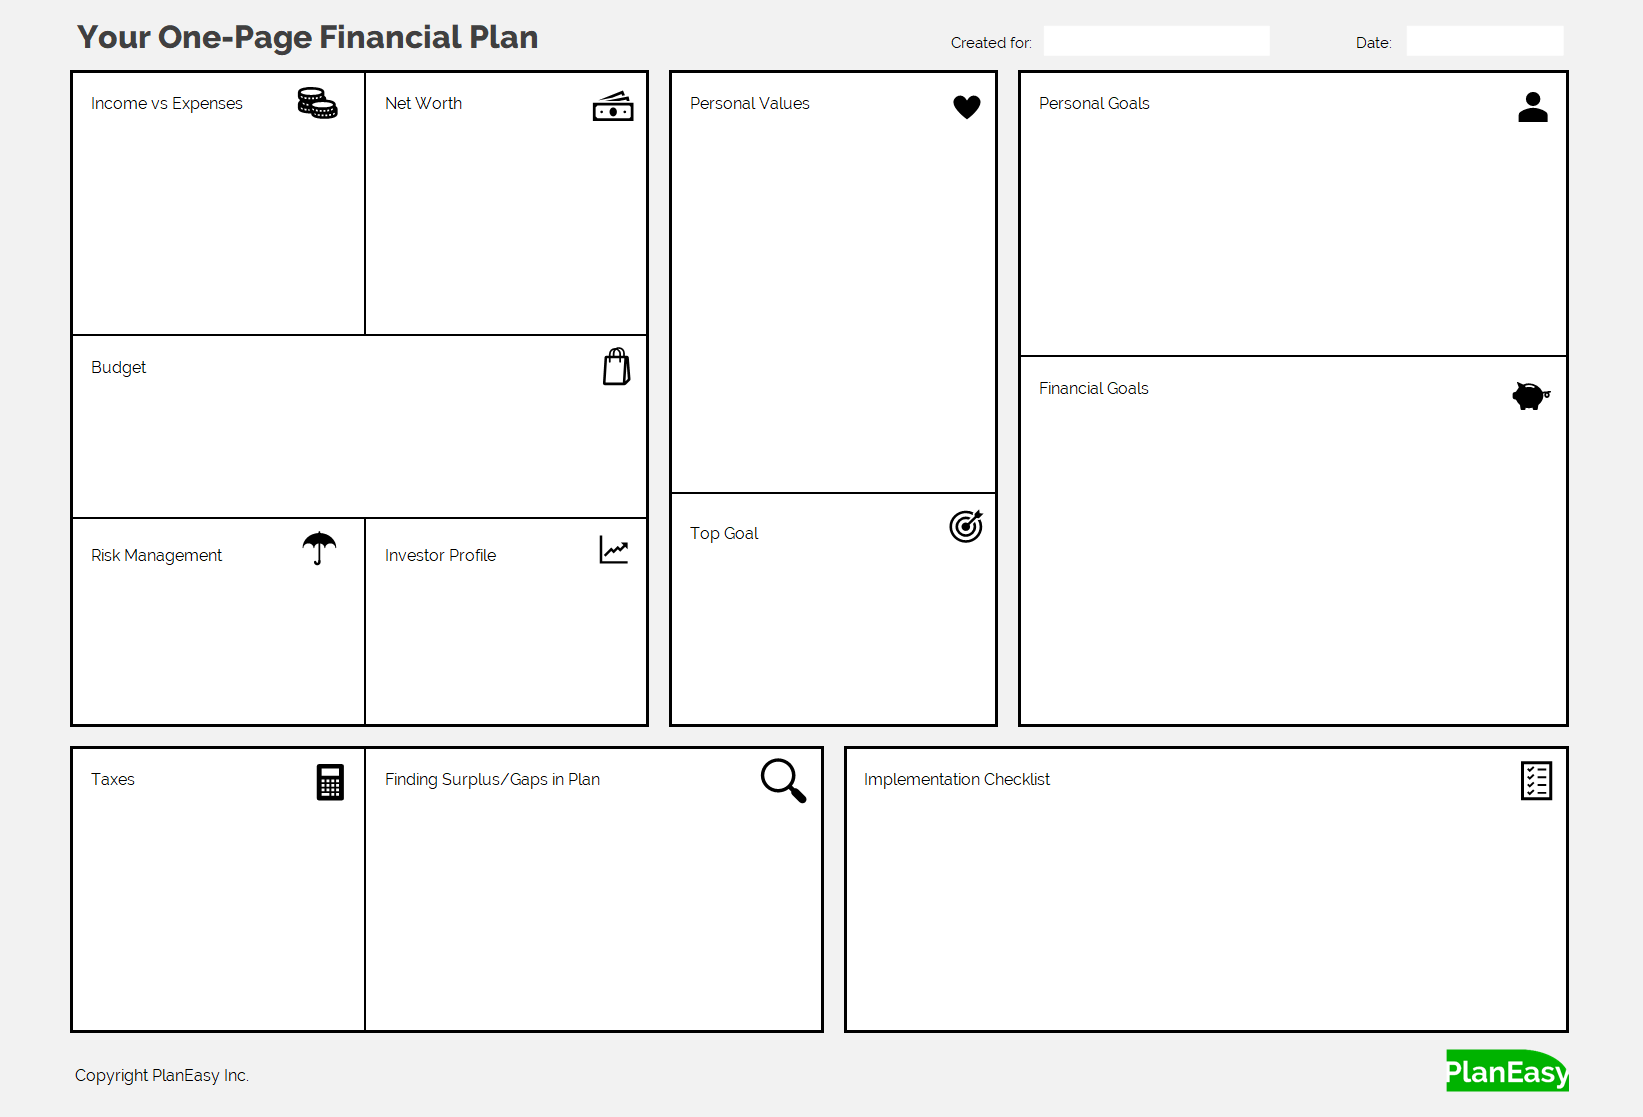
One-page plans fail for people with highly complex tax situations, multiple businesses with cross-liabilities, or international assets. If you're dealing with passive activity losses, depreciation schedules, or offshore accounts, a single page will miss critical interactions between your tax strategy and your cash flow. In those cases, use a one-page summary as a dashboard but maintain a separate detailed plan underneath. Think of it as a menu at a restaurant: the menu is one page, but the kitchen still needs the full recipe cards. If you only have the menu, you won't know how to cook the meal, and you'll make decisions based on incomplete information. Open a blank document or grab a piece of paper. Draw three boxes. Label them net worth, cash flow, and goals. Fill in each box with the most current numbers you can find. Don't search for older statements. Don't try to reconstruct history. Use today's numbers and accept that they're approximate. The goal is to create a reference point, not a forensic audit. I usually tell clients to spend twenty minutes on the first draft and nothing more. Perfection on the first attempt is a sign that you're not finishing fast enough, which means you'll abandon it sooner rather than later. For the actual template format, a basic Google Sheet with three sections works. I've used this same structure with clients across different platforms and the layout is identical: top section for balances, middle for monthly flow, bottom for targets. The formatting doesn't matter nearly as much as the discipline of keeping it to one page. PDF versions circulate from several financial planning associations, but the content inside them is usually generic enough that you could recreate it yourself in ten minutes.
How to measure whether it's actually helping
After ninety days, ask yourself whether you made any financial decisions based on the information on that page. If the answer is no, the plan isn't being used, and you need to either simplify it further or put it somewhere you'll physically see it. I've had clients tape theirs to their bathroom mirror. Others print it and leave it on their kitchen table. The physical placement matters more than the format. A digital file in your Documents folder gets less attention than a printed sheet on your fridge. That's not a metaphor. That's just what happens when people actually follow through on financial habits. If you stick with it for six months, you'll likely notice that your spending patterns shift slightly without you consciously deciding to change them. The plan creates awareness, and awareness changes behavior. That's the whole mechanism. Nothing more complicated than that.