What This Book Actually Gets Right
The Psychology Of Money Summary tends to get treated like a checklist of financial wisdom, but the core idea is simpler and more annoying than that. Morgan Housel argues that doing well with money has less to do with intelligence or formulas and more to do with behavior, temperament, and how you interpret risk over time. That sounds obvious until you're sitting there watching a position drop thirty percent and realizing you already knew what was going to happen and did it anyway. I've spent years watching people read these same concepts and still make the same mistakes. The gap between understanding behavioral finance and actually behaving differently is where most personal finance advice fails. This book acknowledges that gap explicitly, which is why it stays relevant while the latest hot investing guide ends up in the donation bin by next spring.
The Psychology Of Money Summary
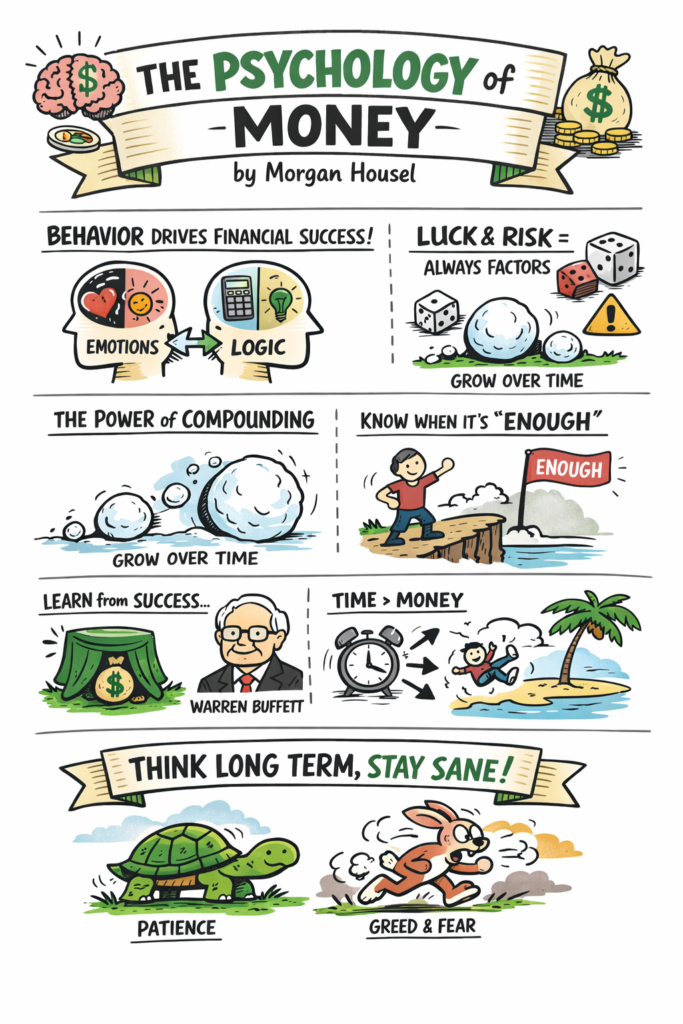
The book breaks down into roughly fifteen standalone chapters, each tackling a different psychological bias or behavioral pattern that shows up when money is involved. Compounding gets treated less as a math problem and more as a patience test. Surprise and randomness get more honest coverage than you find in most finance books. Saving itself gets framed as an emotional act rather than a purely rational one, which is a genuinely useful reframe. The key insight that separates this from generic money advice is how Housel treats individual experience as data. Your personal financial history shapes your expectations more than any textbook model. Someone who grew up during high inflation will react differently to a bond portfolio than someone who came of age during the low-inflation decade that followed. Neither person is wrong. They just have different reference points, and those reference points drive decisions more than any spreadsheet ever will.
How to Actually Use These Ideas
Reading the book gives you awareness. Awareness alone does not change your behavior. The practical application requires setting up systems that remove the moments where your psychology becomes the bottleneck. I built a simple rule for myself: automatic contributions to index funds on payday, no exceptions, no review periods. That removed the decision entirely. The behavior change happened because the environment changed, not because I became a more disciplined person. The common failure mode is expecting willpower to bridge the gap between knowledge and action. That approach has an extremely low success rate. Behavioral economics research consistently shows that environment design beats intention-setting by a wide margin. When you structure your finances so the default option aligns with your long-term goals, you stop relying on daily acts of self-control. Most people skip this step because it feels less satisfying than reading another chapter about mindset. Here is a specific edge case I ran into that most guides do not cover. I had a client whose tax situation was unusual enough that standard automated investing recommendations created a taxable event every time they rebalanced. The psychological framework from the book still applied, but the mechanical implementation required a workaround. I switched the account structure to a direct-indexing approach within a taxable account and set up automatic harvest-loss schedules that triggered without any manual intervention. The behavioral principle stayed the same, but the vehicle changed. This usually takes about forty-five minutes to set up correctly if you know what you are doing, or two to three weeks if you are figuring it out as you go.
Get the Full Details

Counter-Intuitive Points Beginners Miss
One insight that rarely gets enough attention is the difference between wealth and having wealth. Building it requires frugality and restraint. Keeping it requires something closer to paranoia, or at least a healthy respect for how easily circumstances can shift. Housel makes the point that the hardest part of financial success is not the early accumulation phase. It is the maintenance phase, where your biggest enemy is not ignorance but overconfidence built on recent good fortune. Another overlooked detail is that rationality is context-dependent. What looks irrational in a market downturn often looked perfectly rational during the preceding bull market. Position sizing that seemed reasonable at one valuation level becomes dangerous at another, yet most investors never recalibrate because their emotional baseline shifted during the up cycle. The book does not solve this problem for you, but it gives you the vocabulary to recognize when your own calibration is off.
Where This Approach Falls Short
The book is not a complete guide to personal finance. It does not cover tax strategy in depth, estate planning, insurance decisions, or the mechanics of investment selection beyond broad philosophical points. If you are looking for a step-by-step plan to build a portfolio, you will need to supplement this with more technical resources. The behavioral foundation is necessary but insufficient for anyone with a complex financial situation. Some readers also find the chapter structure repetitive. Each story drives home essentially the same lesson about patience and emotional control, and after the fifth variation on that theme, the novelty wears off. That is not a flaw in the framework, but it is worth noting if you are deciding whether to invest the time. The material is dense enough that you can get the core ideas from a shorter summary and move on to implementation faster.
Practical Takeaways That Actually Stick
The most useful actionable element is the concept of enough. Define what enough looks like for your own life rather than adopting someone else's benchmark. This is harder than it sounds because social comparison is baked into how most people evaluate financial success. Once you establish your own threshold, you can make decisions without the noise of external reference points driving your risk tolerance. Another practical tool is saving before spending, not after. This reverses the default behavior that most payroll systems encourage. Automate the transfer on payday and live on whatever remains. The behavioral shift is subtle but significant because it treats saving as a fixed obligation rather than a discretionary afterthought. People who implement this consistently report that it takes about six weeks to adjust psychologically, then the new baseline feels normal. The book's treatment of luck and risk deserves special mention because it is both the most honest and the most uncomfortable part. Recognizing that outcomes are heavily influenced by factors outside your control does not mean you should stop planning. It means you should plan conservatively and build in margins for events that models predict infrequently but that happen with regularity in practice. This is the difference between theoretical risk management and the kind that keeps you solvent when something unexpected occurs.