How Revenue Recognition Actually Works in Practice
The Revenue Recognition Principle Guides Accountants In
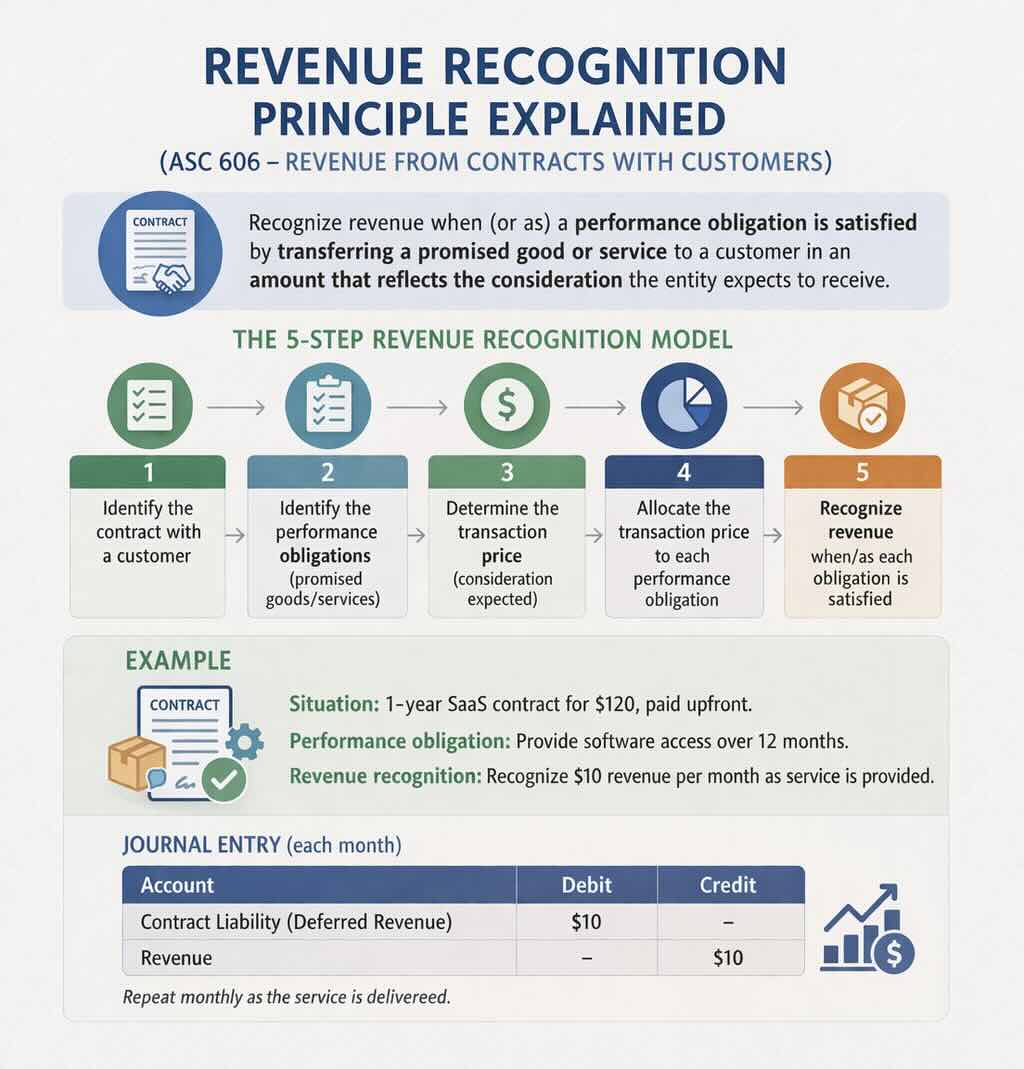
Most people think revenue recognition is just about recording sales when you invoice them. That is wrong. The principle determines when you can legitimately record revenue on your books, and getting it wrong means your financial statements are garbage regardless of how clean your general ledger looks. The core rule is straightforward: recognize revenue when performance obligations are satisfied, not when cash changes hands. If you deliver goods or services over time, you recognize revenue over time. If you deliver everything upfront, you recognize it all at once. The difficulty comes from the gray areas where contracts don't fit neatly into either box. I have been dealing with this since 2014 across multiple industries, and the edge cases never stop appearing. Here is one that still bothers me. A client had a software licensing deal structured as an annual subscription with implementation services bundled in. They were recognizing the entire contract value upfront because they treated it as a single performance obligation. The contract explicitly stated implementation was optional for about 40 percent of customers. When I pulled the clause and traced it against the five-step model under ASC 606, we had to split the contract into two distinct performance obligations. That moved roughly 30 percent of their revenue recognition into a twelve-month straight-line pattern instead of month one. The rest of the team wanted to stick with the simpler approach. I held the line because the audit trail would not have survived a single review from outside counsel. The five-step model is the framework you follow:Identify the contract with the customer. Identify the performance obligations in the contract. Determine the transaction price.
Allocate the transaction price to each performance obligation. Recognize revenue when or as each performance obligation is satisfied.
Step one trips people up because they assume a signed document automatically creates a valid contract. It does not. The contract needs commercial substance, it needs to be enforceable, and there has to be reasonable assurance of payment. I have seen companies recognize revenue on agreements that were effectively verbal or had payment terms that violated credit policies just because someone in sales thought a handshake was binding. It is not. Step two is where most mistakes happen. A performance obligation is a promise to transfer a distinct good or service to the customer. Distinct means the customer can benefit from it on its own or together with other readily available resources, and the promise is separately identifiable within the contract. Bundled services and products often fail the separately identifiable test. For example, if you sell custom manufacturing equipment along with a two-year maintenance plan, those are usually distinct. But if you sell a customized software solution where the license only works with your proprietary platform and ongoing support is essential to its functionality, those may need to be treated as a single performance obligation. The distinction matters enormously for timing. Step three requires you to estimate variable consideration. This includes things like rebates, discounts, refunds, chargebacks, and performance bonuses. You use either the expected value method or the most likely amount method, depending on which better predicts the outcome. The catch is that variable consideration gets constrained. You can only include it in the transaction price to the extent it is probable that a significant reversal will not occur later. I spent three months working through a distributor agreement where the volume discount tiers created a variable consideration problem that we could not resolve using the expected value method. We ended up using the most likely amount approach by modeling the highest probable sales tier based on historical ordering patterns, and that held up during the external audit without a single adjustment. Step four is pure allocation math. You allocate based on standalone selling prices. If you do not have an observable standalone selling price for a component, you estimate it. There are acceptable estimation methods: adjusted market assessment, expected cost plus margin, and residual approaches. The residual approach has strict conditions. You can only use it when the selling price of a good or service is highly variable or uncertain relative to other goods in the portfolio. Misapplying the residual approach is a common audit finding. Step five is where the rubber meets the road. Revenue recognition happens either over time or at a point in time. The over-time criteria are specific: the customer simultaneously receives and consumes the benefit as you perform, the customer controls the asset as it is created, or the asset has no alternative use to you and you have an enforceable right to payment for performance completed to date. Most service contracts and long-term construction contracts fall under the first or third criteria. Everything else defaults to point-in-time recognition. One thing beginners consistently miss is the enforceable right to payment requirement under the no alternative use criterion. It does not mean you get paid if the customer cancels for convenience. It means you get paid for work performed plus a reasonable margin, and that right must be enforceable even if cancellation is for reasons other than your failure to perform. I worked on a contract where the cancellation clause gave the customer the right to cancel for convenience with thirty days notice, but the payment on cancellation only covered costs, not margin. We initially classified it as over-time recognition. A reviewer flagged it, and we reversed to point-in-time because the right to payment did not include a reasonable profit margin. That single change shifted a quarter million in revenue from month eight to month twelve. Another overlooked nuance is principal versus agent considerations. If you are a principal, you recognize revenue at the gross amount. If you are an agent, you recognize only the net commission or fee. The control test is the deciding factor. Did you control the good or service before it transferred to the customer? Indicators include primary responsibility for fulfillment, inventory risk before transfer, and discretion in establishing prices. Companies frequently misclassify themselves as principals when they are agents, inflating revenue figures materially. One of my clients had a marketplace arrangement where they claimed principal treatment on $2.4 million in transactions. The inventory risk was minimal because they never took possession, and the pricing was set by the actual service providers. We reclassified the entire amount to agent treatment, dropping reported revenue to $312,000. The revenue quality improved but the top line took a noticeable hit, and the CEO was not happy about it. There are real downsides to this framework. It is complex, it requires judgment calls that different accountants will make differently, and it does not provide the comfort of bright-line rules. Small businesses with straightforward product sales can apply it mechanically. Service-based businesses, subscription models, and any arrangement with bundled components will require actual analysis. The framework also creates timing mismatches between revenue recognition and cash collection that can distort your profitability picture quarter to quarter, especially if you are collecting on long contracts upfront and recognizing over time. If your business has simple one-time sales with no contingencies, you probably do not need a dedicated revenue recognition process beyond basic accrual accounting. But if you have contracts spanning multiple periods, bundled offerings, variable consideration, or international arrangements, you need a documented methodology. I recommend maintaining a revenue recognition policy memo for each contract type you offer, with the specific conclusions on performance obligations, transaction price allocation, and recognition patterns. Auditors and tax authorities will ask for this. Having it prepared in advance saves you from scrambling during reviews. For reference, the authoritative guidance in the United States is ASC 606, Revenue from Contracts with Customers, issued by the FASB. Internationally, the equivalent is IFRS 15. The principles are substantially converged but there are differences in areas like contract modifications and license arrangements that matter if you operate across jurisdictions.