Why the Gail Vaz Oxlade Budget Worksheet Actually Works
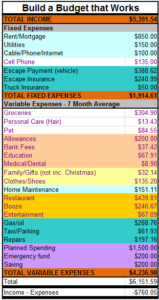
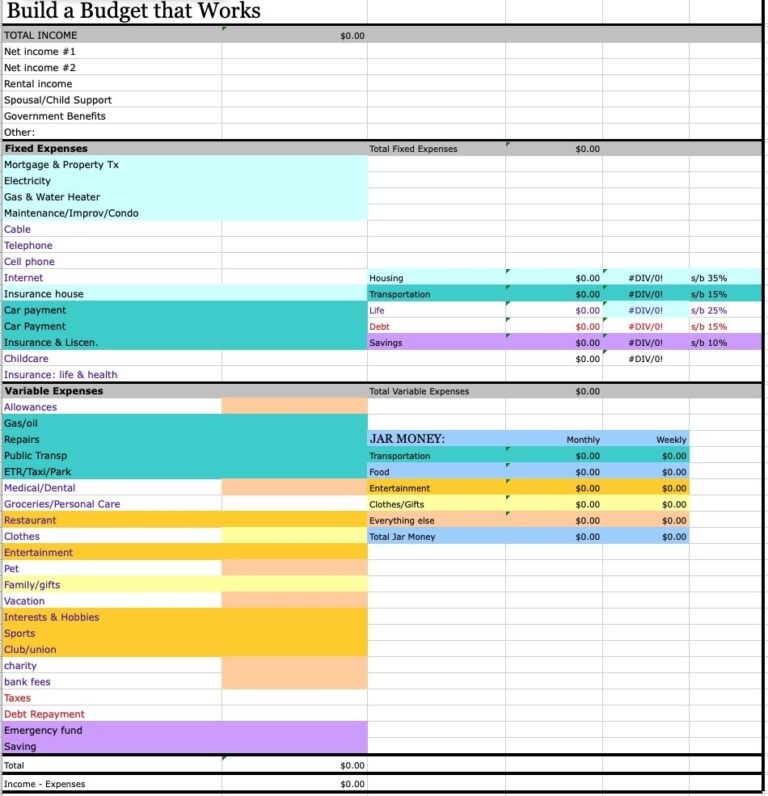
The Til Debt Do Us Part Gail Vaz Oxlade Budget Worksheet is one of those tools that looks almost too simple to be useful, but it strips away enough noise to make your money problem obvious within a single sitting. I ran through it with a client last fall who had been tracking expenses in an app for three years and still didn't know where the leak was. She filled the worksheet in forty minutes. By row seven, she could see she was spending $340 a month on subscriptions she didn't use. The app never showed that to her. The basic structure divides every dollar into one of four buckets: fixed expenses, variable expenses, debt payments, and savings. You write each line item by hand or type it in. The key move is that you record what you actually spent, not what you think you should have spent. That distinction is what separates people who use this successfully from the ones who abandon it after two weeks.
Til Debt Do Us Part Gail Vaz Oxlade Budget Worksheet
The worksheet was created as part of the CBC show and book, but the actual PDF circulates in a handful of formats now. Some versions come from the official website, others from personal finance forums and archive sites. The core layout stays consistent: a grid with income at the top, expense categories below, a section for listing debts alphabetically with interest rates and minimum payments, and a final calculation row that tells you whether you are running a surplus or a deficit. What makes it different from a standard spreadsheet budget is the emphasis on the zero-based allocation method. Every dollar of income gets assigned a job before the month starts. If you have $100 left over after filling every category, that $100 goes somewhere deliberate, usually debt or savings. The worksheet forces you to answer where before you spend.
How to Use It Without Quitting by Wednesday
Most people mess this up by trying to be too precise on week one. They categorize a coffee purchase to the exact cent and then feel guilty when they overshoot by four dollars later in the week. Here is how to actually get results. Week one is for data gathering, not behavior change. Fill out the worksheet using last month's actual numbers. Do not guess. Pull bank statements, credit card exports, receipts, whatever you have. Round to the nearest dollar. The goal is to see your baseline, not to fix anything yet. You will find errors in your mental model of your own spending during this step alone. I had a contractor swear he spent $80 a month on groceries before he filled out this worksheet and saw his real number was $310. He buys lunch at a construction site diner every day and never counted it. Week two is where you assign jobs to every dollar. Income minus expenses should equal zero. If you overshoot expenses, trim a variable category or add income. If you undershoot, you need to increase something or acknowledge the gap. The Til Debt Do Us Part Gail Vaz Oxlade Budget Worksheet shows you the gap clearly because the math does not lie.
Get the Full Details

Month two and onward is when you actually adjust behavior. This is also when people quit, usually because they encounter irregular expenses. A $600 annual insurance premium wipes out a perfectly balanced month if you did not set aside $50 a month for it. The workaround is to create sinking fund rows for any expense that comes less than monthly. Put the total divided by twelve into each month's budget. This is a detail the original worksheet hints at but does not spell out explicitly.
Common Pitfalls and What to Do About Them
The biggest issue I see is people treating the worksheet like it belongs to a single person when two or more earners share an account. They split income 50-50 on paper and then argue about who owes what. The fix is to list each income source separately and merge the totals only in the income section. Expenses stay individual until the final allocation row. Another issue is the debt section. People list their debts in order of balance size rather than alphabetically, which is what the worksheet asks for. The alphabetical layout is not arbitrary. It prevents you from fixating on the credit card with the highest balance while ignoring the one with the worst interest rate. Use the worksheet as written, then layer in a debt payoff strategy on a separate sheet. Combining both systems on one grid creates visual clutter that leads to skipped months. I ran into a specific edge case recently with a freelancer who had no fixed salary. Her income varied from $2,100 in one month to $6,800 the next. She kept failing the worksheet because she could not balance the high-income months. The solution was to budget off her lowest expected month and treat anything above that as discretionary debt or savings. That way the worksheet stays balanced even in bad months. High months simply generate a surplus that rolls forward.
Where the Method Breaks Down
This worksheet assumes you have relatively stable expenses and can predict your income within a reasonable range. If you are a gig worker with zero income certainty, or if you carry variable-rate debt that swings wildly month to month, the Til Debt Do Us Part Gail Vaz Oxlade Budget Worksheet will give you false confidence. You will balance the numbers and still end up short because your actual costs shifted outside the categories. In those cases, I recommend combining it with a rolling twelve-month forecast. Use the worksheet for monthly cash flow management, but keep a separate spreadsheet that projects your next twelve months based on recent history. That catches seasonal shifts and compounding interest effects that a single-month snapshot misses.

Getting the Worksheet
The original version is available through the Til Debt Do Us Part program website, though access sometimes requires registering for the email list. Several personal finance communities host archive copies as well. The content is identical regardless of source. The important part is not the PDF file itself. It is the discipline of filling it out honestly every month and adjusting from there. I stick with a modified Google Sheets version that adds conditional formatting to highlight overspent categories in red. The original worksheet does not flag variances visually. If you want that, you have to build it yourself. Otherwise, a printed copy or the default PDF works fine for the first three months. After that, the spreadsheet version saves time on recalculation and lets you keep a rolling history of twelve months for trend analysis.
What to Track Beyond the Worksheet
The worksheet covers your base well, but it does not capture debt interest accumulation or investment returns. If you carry balances, track the interest saved each month by making extra payments. The worksheet shows you the extra payment amount, but it does not project the long-term impact. A simple side calculation of principal reduction versus interest paid over twenty-four months will show you which debt to target first. Savings and investment accounts should be listed as categories within the worksheet, but the growth itself belongs elsewhere. This separation keeps the budget readable. One page for allocation, one place for growth tracking. Mixing both on the same grid inflates the row count and makes the whole thing feel overwhelming, which is a common reason people stop using it.