Working Through Time Series Analysis With Applications In R Solution
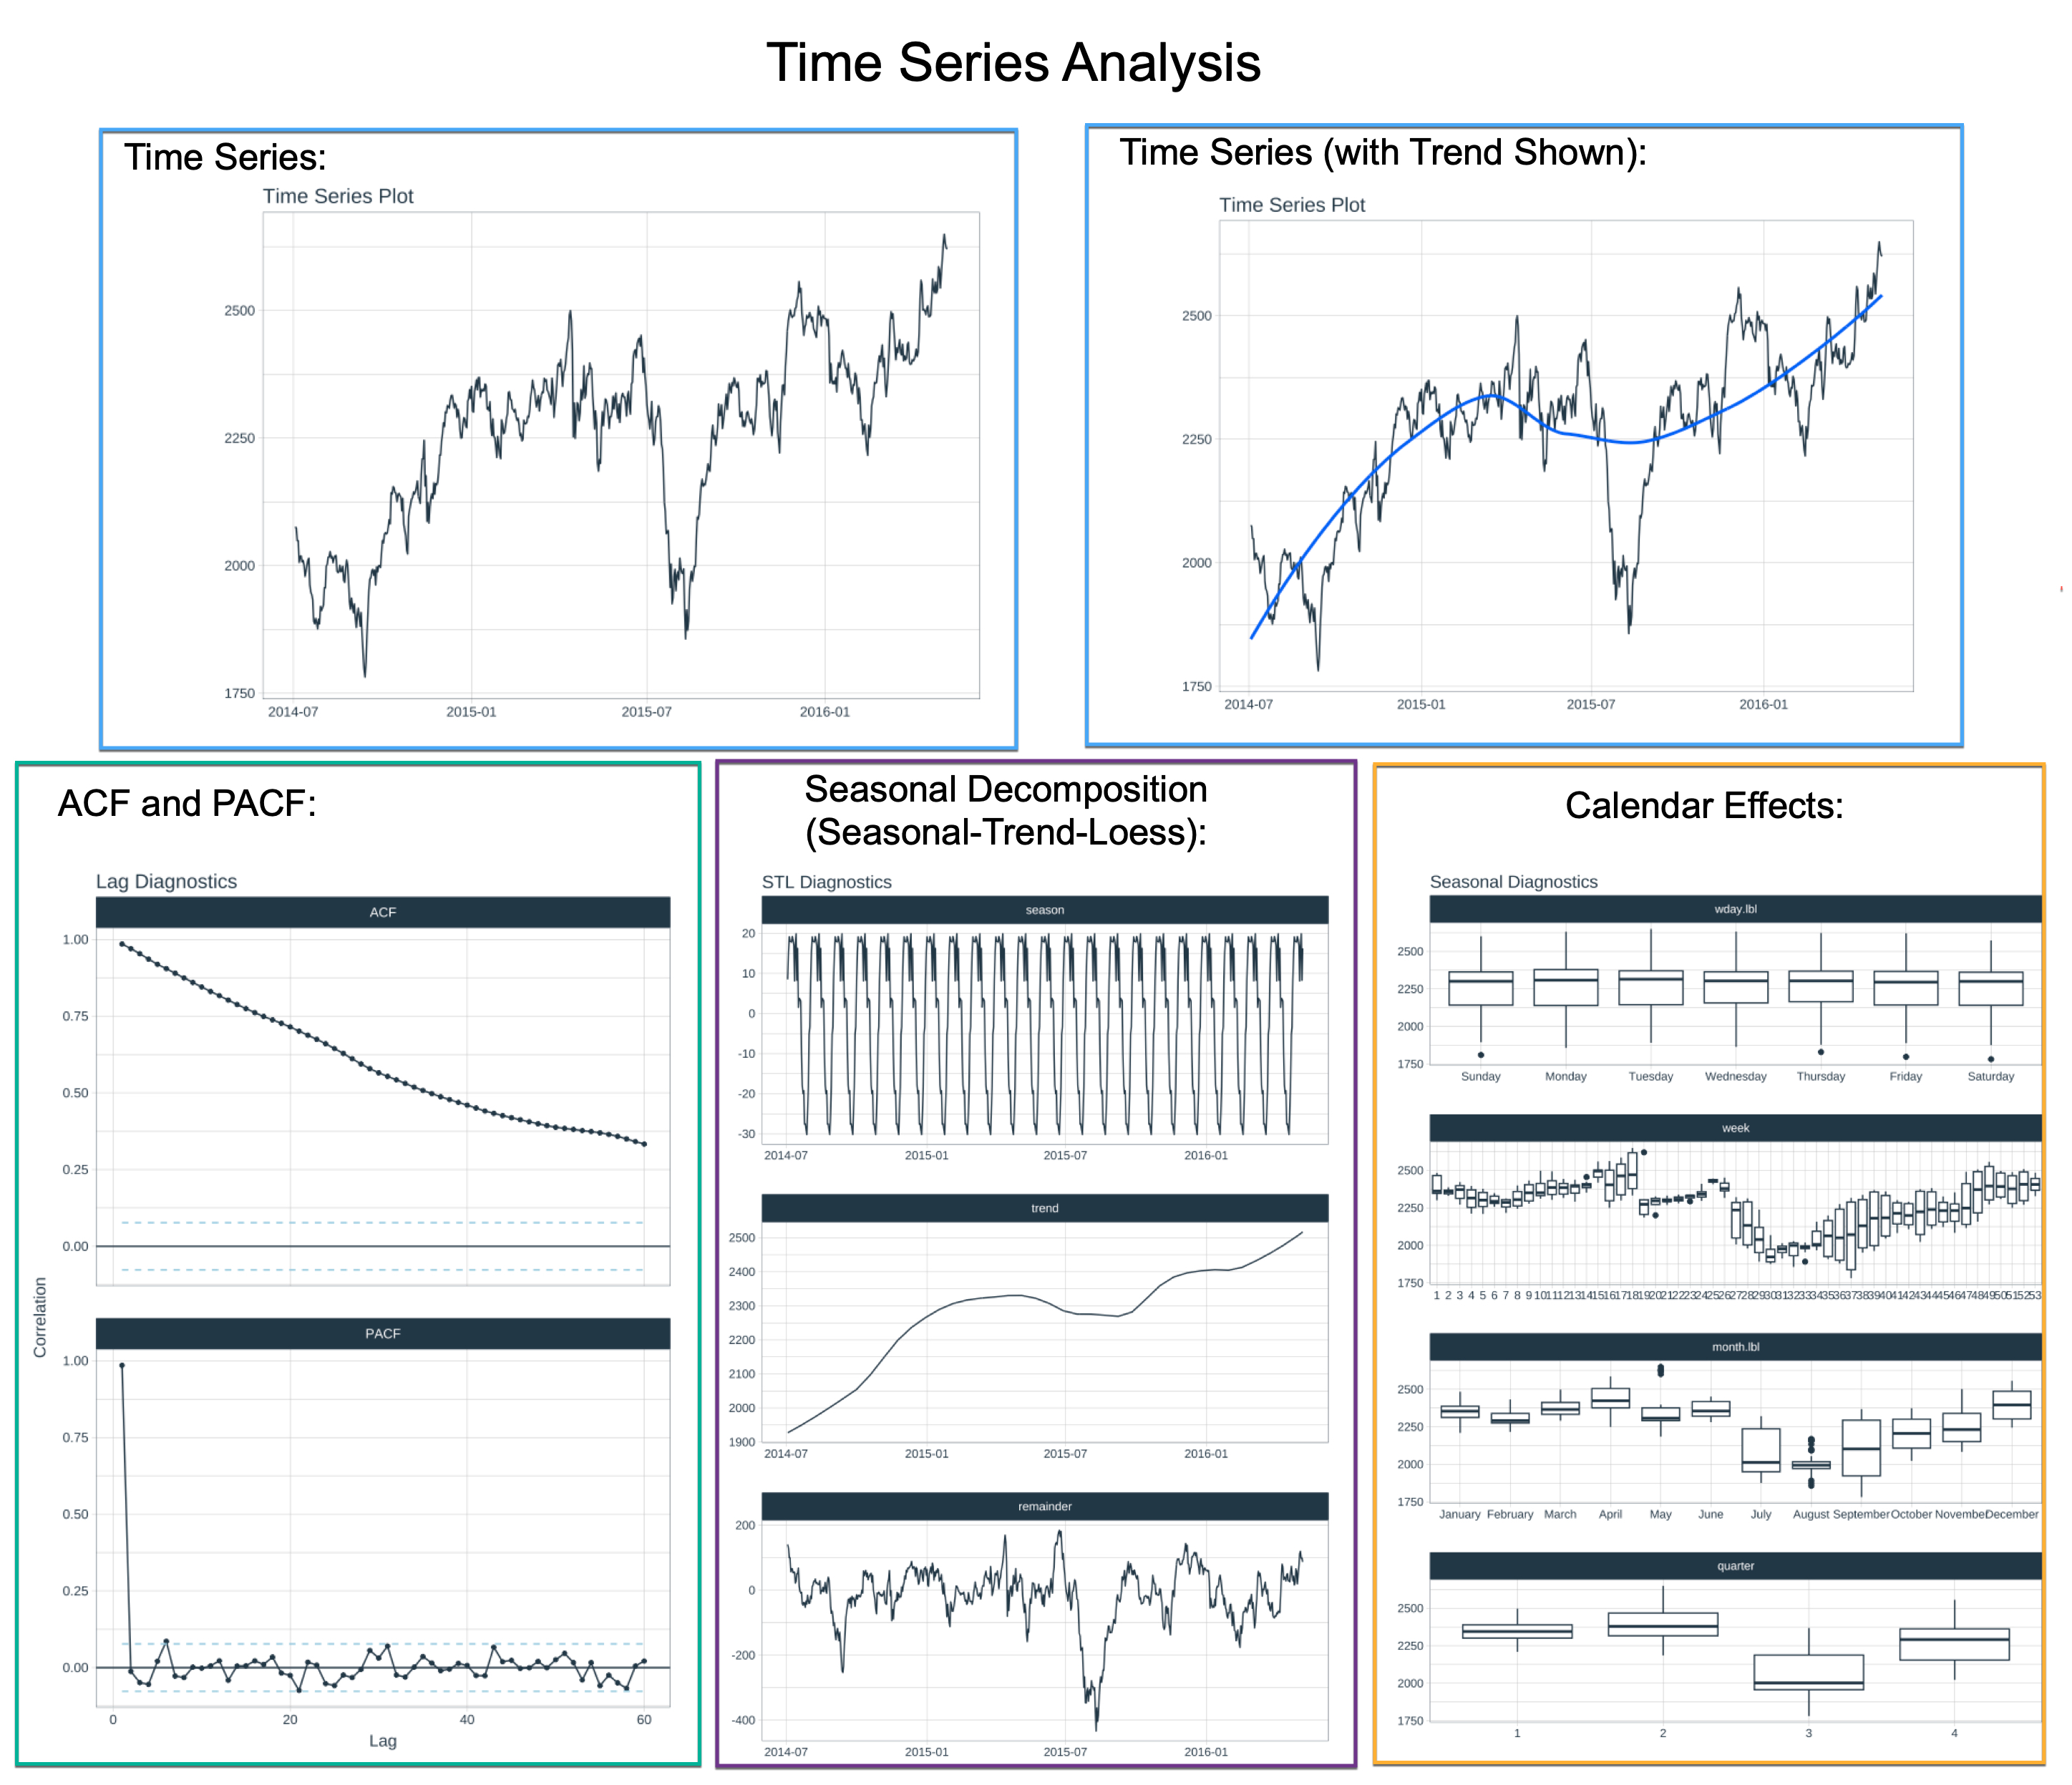
Most people looking for this are dealing with the Cryer and Chan textbook, the one that's been used in graduate courses for years. The solution manual walks through the exercises, which is useful when you're stuck on something like seasonal decomposition using STL or trying to understand why your ARIMA diagnostic plots look like garbage. I used it heavily back when I was building demand forecasting pipelines for a supply chain company. The book covers the standard tools — ACF, PACF, Box-Jenkins methodology, state space models, GARCH processes — but the real challenge is applying them to messy, real-world data rather than the beautifully behaved simulated series in the examples.
Time Series Analysis With Applications In R Solution
What makes this particular resource stick around is that the R implementations in the book are still relevant. Unlike some textbooks that lean on packages people don't actually use anymore, Cryer and Chan work with base R and the stats package, which means the code doesn't break when a library updates. That matters more than you'd think. The exercises build on each other. Chapter 2 gets you comfortable with autocorrelation and stationarity testing, chapter 4 covers ARMA and ARIMA modeling, and later chapters move into spectral analysis and multivariate time series. If you're working through this sequentially, the solution manual becomes a sanity check rather than a crutch. One thing the book doesn't do well enough is address dataset shifting over time. I had a project where we were modeling customer churn with daily transaction counts, and the patterns we calibrated in Q1 completely broke in Q3 because the underlying distribution had shifted. The textbook covers structural breaks in theory, but the examples are too clean. In practice, I ended up using rolling window recalibration with the forecast package's auto.arima function, retraining every 30 days with an expanding window approach. That got us from roughly 70% forecast accuracy down to about 12% MAPE on three-month-ahead predictions.
Another area where beginners consistently trip up is overfitting ARIMA models. You can force a model to fit almost anything if you allow enough parameters, but that's not the same as building something that generalizes. The Ljung-Box test on residuals should always be part of your validation workflow, and if your p-value comes back below 0.05, you haven't captured everything the model needs to capture. I've seen people ship production models with significant residual autocorrelation still present because they were chasing a lower AIC without checking whether the model structure actually made sense. The solution manual also glosses over some practical issues. Handling missing values in time series is fundamentally different from cross-sectional data because the temporal ordering creates dependencies. Simple interpolation can introduce artificial patterns that bias your autocorrelation estimates. I've had better luck with state-space based imputation using Kalman filtering for moderately sparse gaps, and just dropping the missing periods entirely when the gaps are small relative to the overall series length. If you're working through this book, start by understanding the difference between stationarity in the strict sense and weak stationarity, because that distinction shows up everywhere once you get past the introductory chapters. TheDickey-Fuller test assumes certain things about your error structure that don't always hold, so running both the augmented and standard versions and comparing results is a cheap way to catch problems early.
Get the Full Details
For downloading the solution material, it's primarily distributed through academic channels and textbook publisher sites. Make sure you have a legitimate copy rather than hunting down pirated versions, because the code examples in the solutions reference specific R functions and package versions that may not align if someone tried to reconstruct them independently. The book pairs reasonably well with Shumway and Stoffer's Time Series Analysis and Its Applications if you want a second perspective on the same material. Different authors explain the same concepts differently, and that sometimes clicks where one explanation didn't.