Working with present and future value calculations doesn't have to be a guessing game.
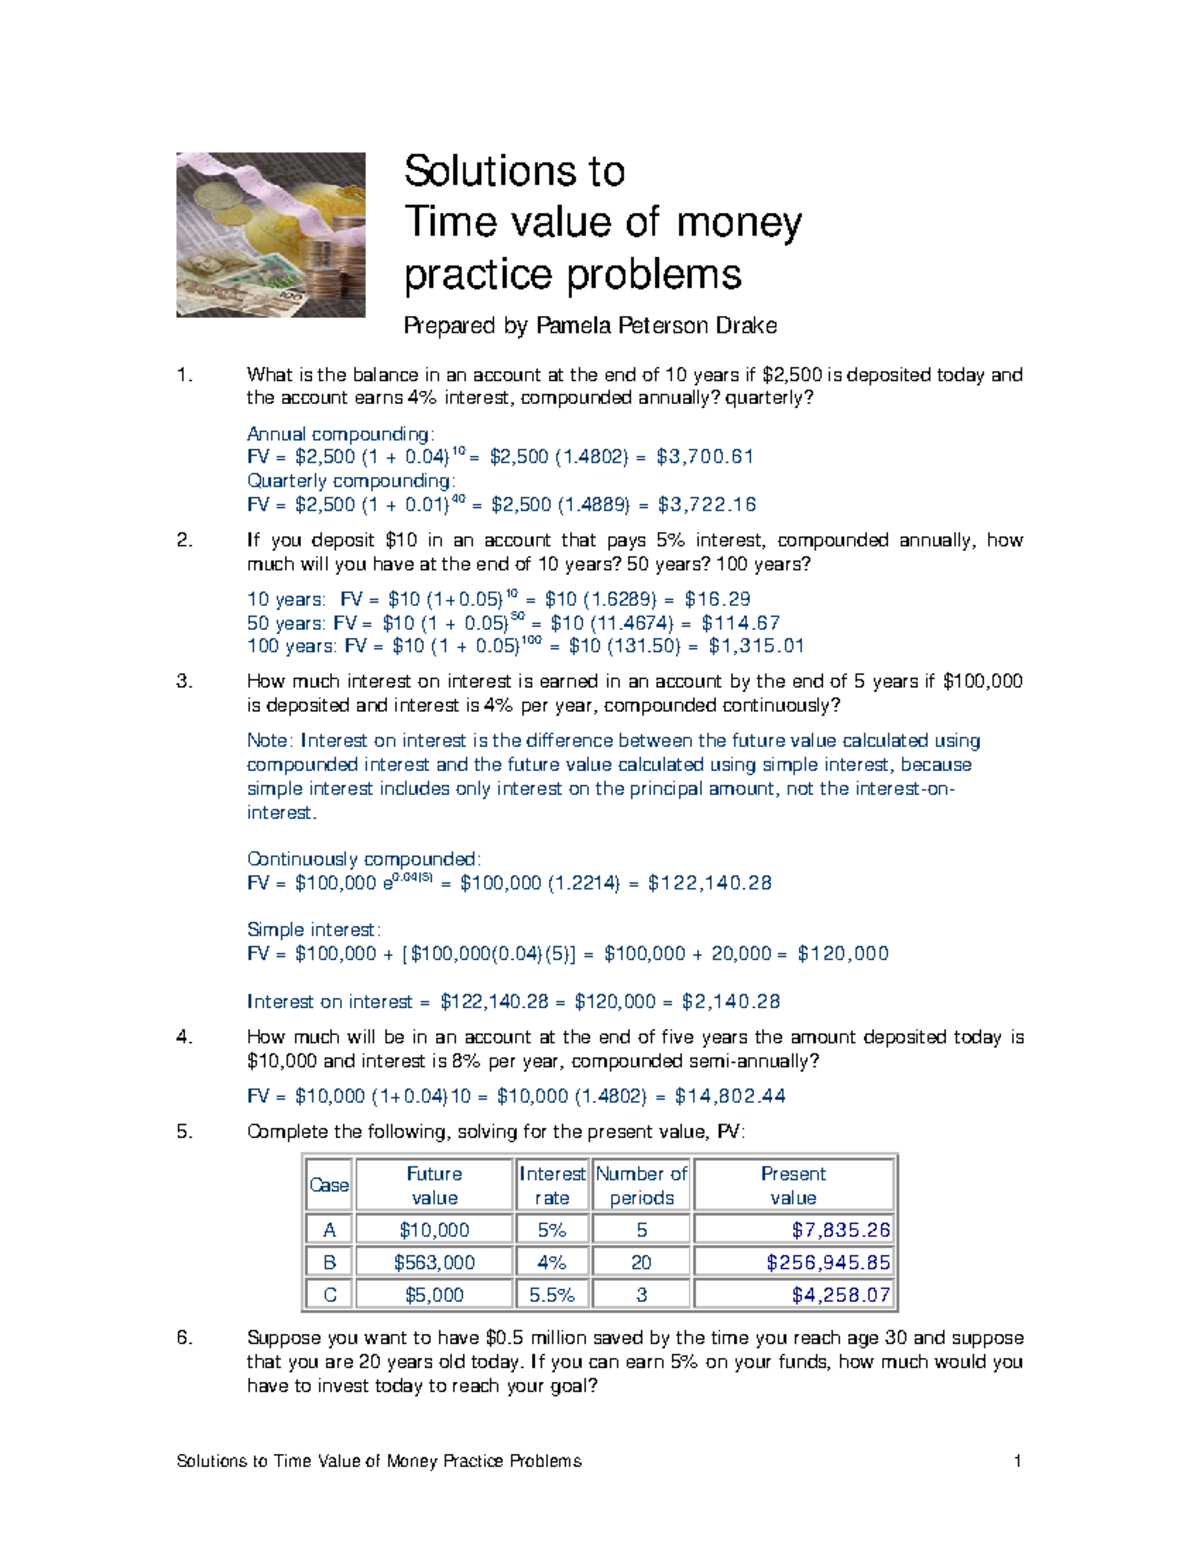
I keep seeing the same mistakes in finance threads and in actual work spreadsheets. People mix up compounding periods, swap PMT and PV, or just punch numbers into a financial calculator without understanding what each variable actually represents. The concept itself is straightforward—money available now is worth more than the same amount later—but the problems get messy fast once you introduce irregular cash flows, varying compounding frequencies, or lease agreements with residual values. The core relationship is simple. You compound a present amount forward or discount a future amount backward. The standard formula is FV = PV × (1 + r)^n where r is the rate per period and n is the number of periods. That works cleanly when payments are level, timing is regular, and the rate doesn't change. Most real-world scenarios aren't clean.
Common Time Value Of Money Problems And Solutions
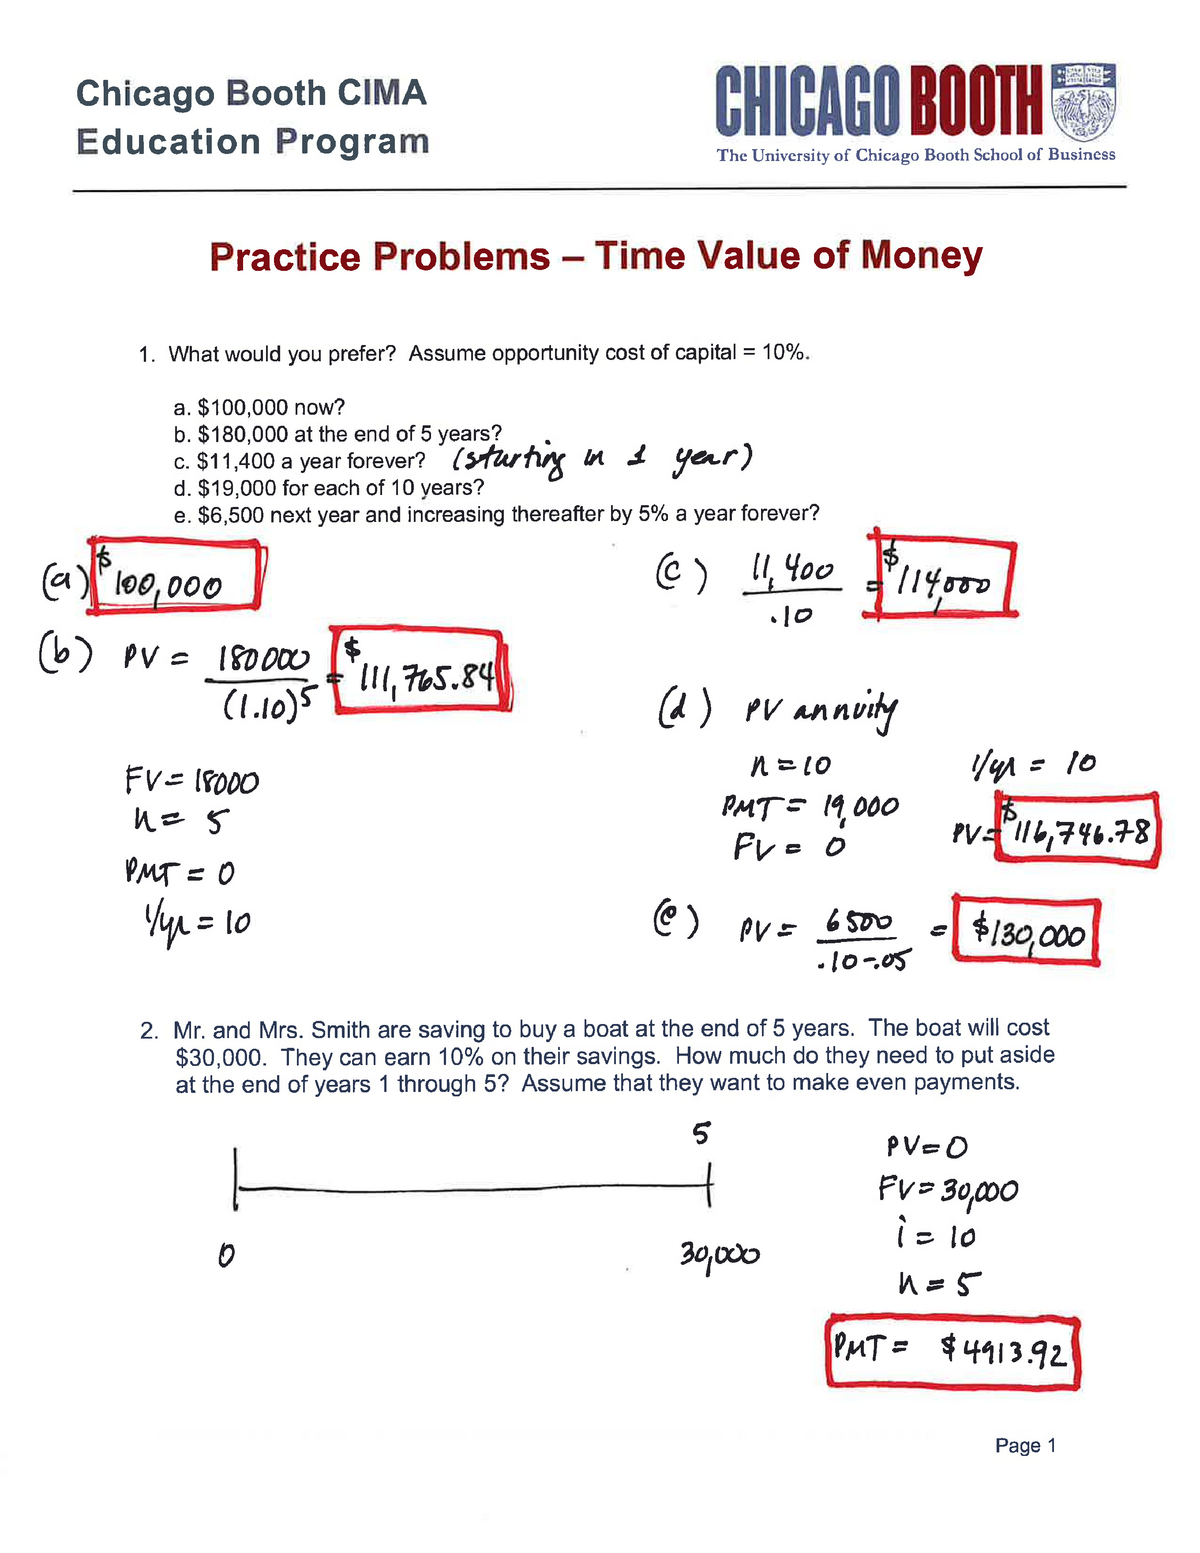
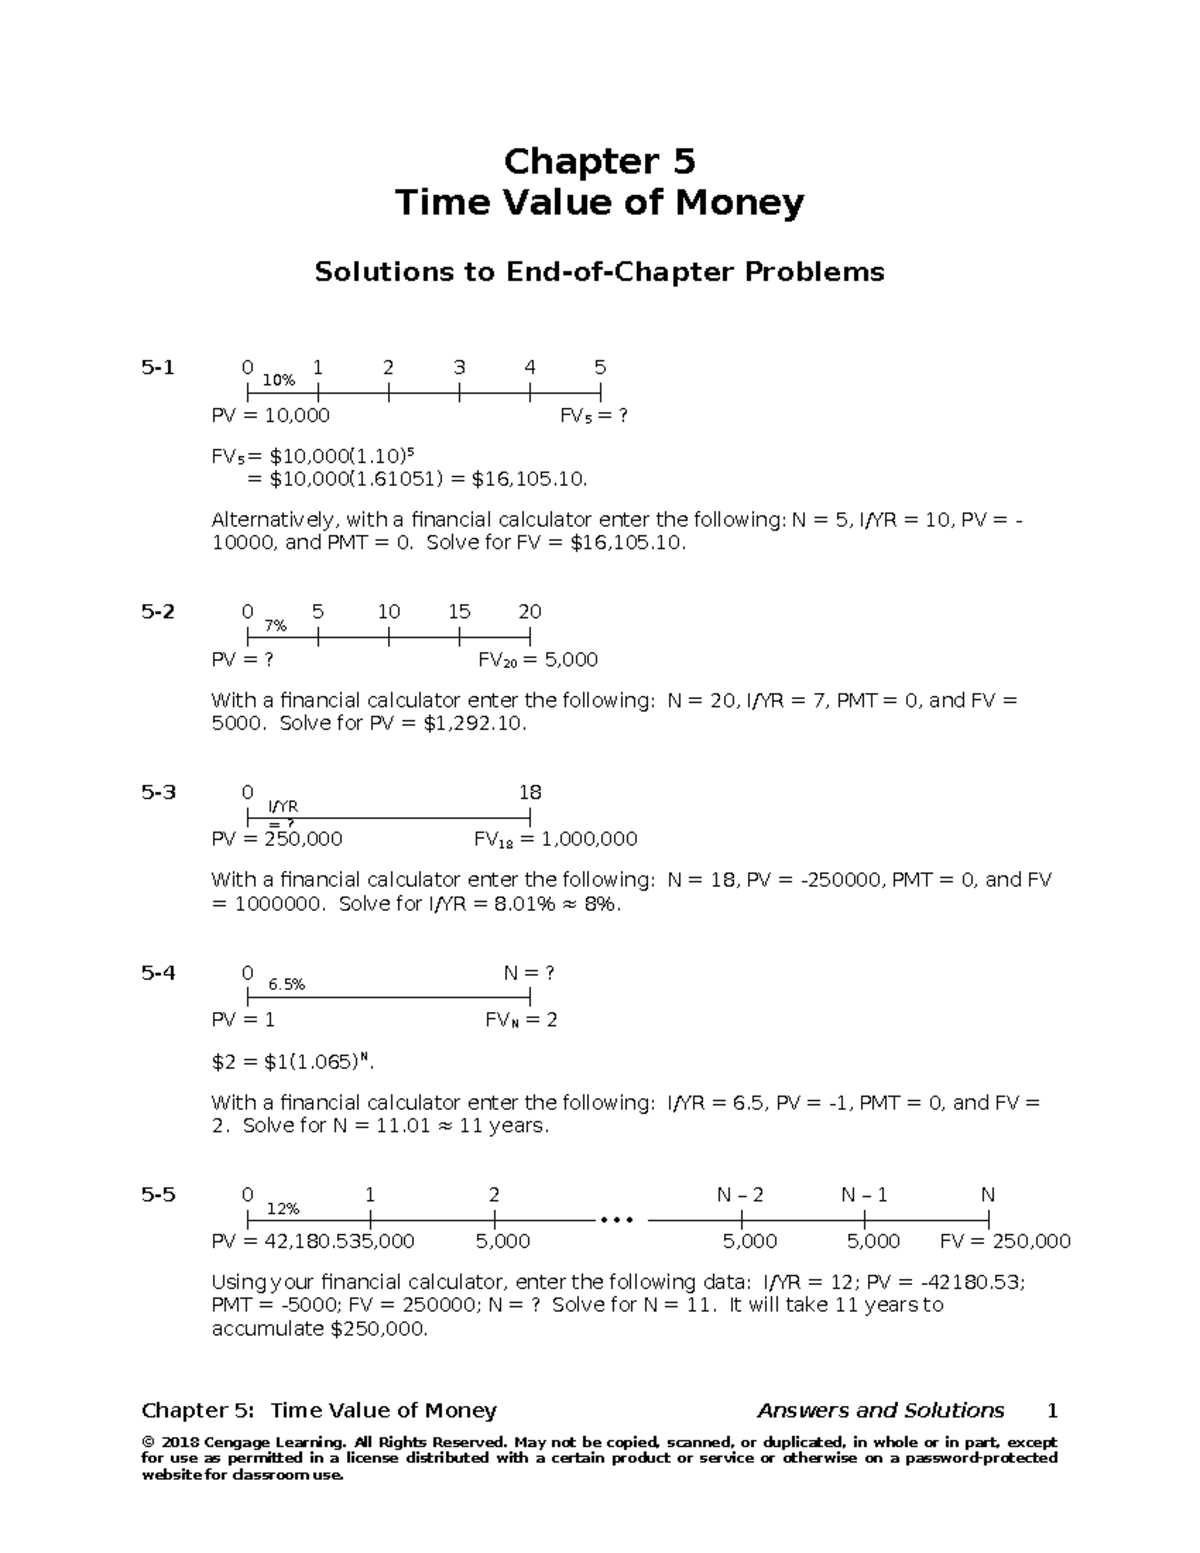
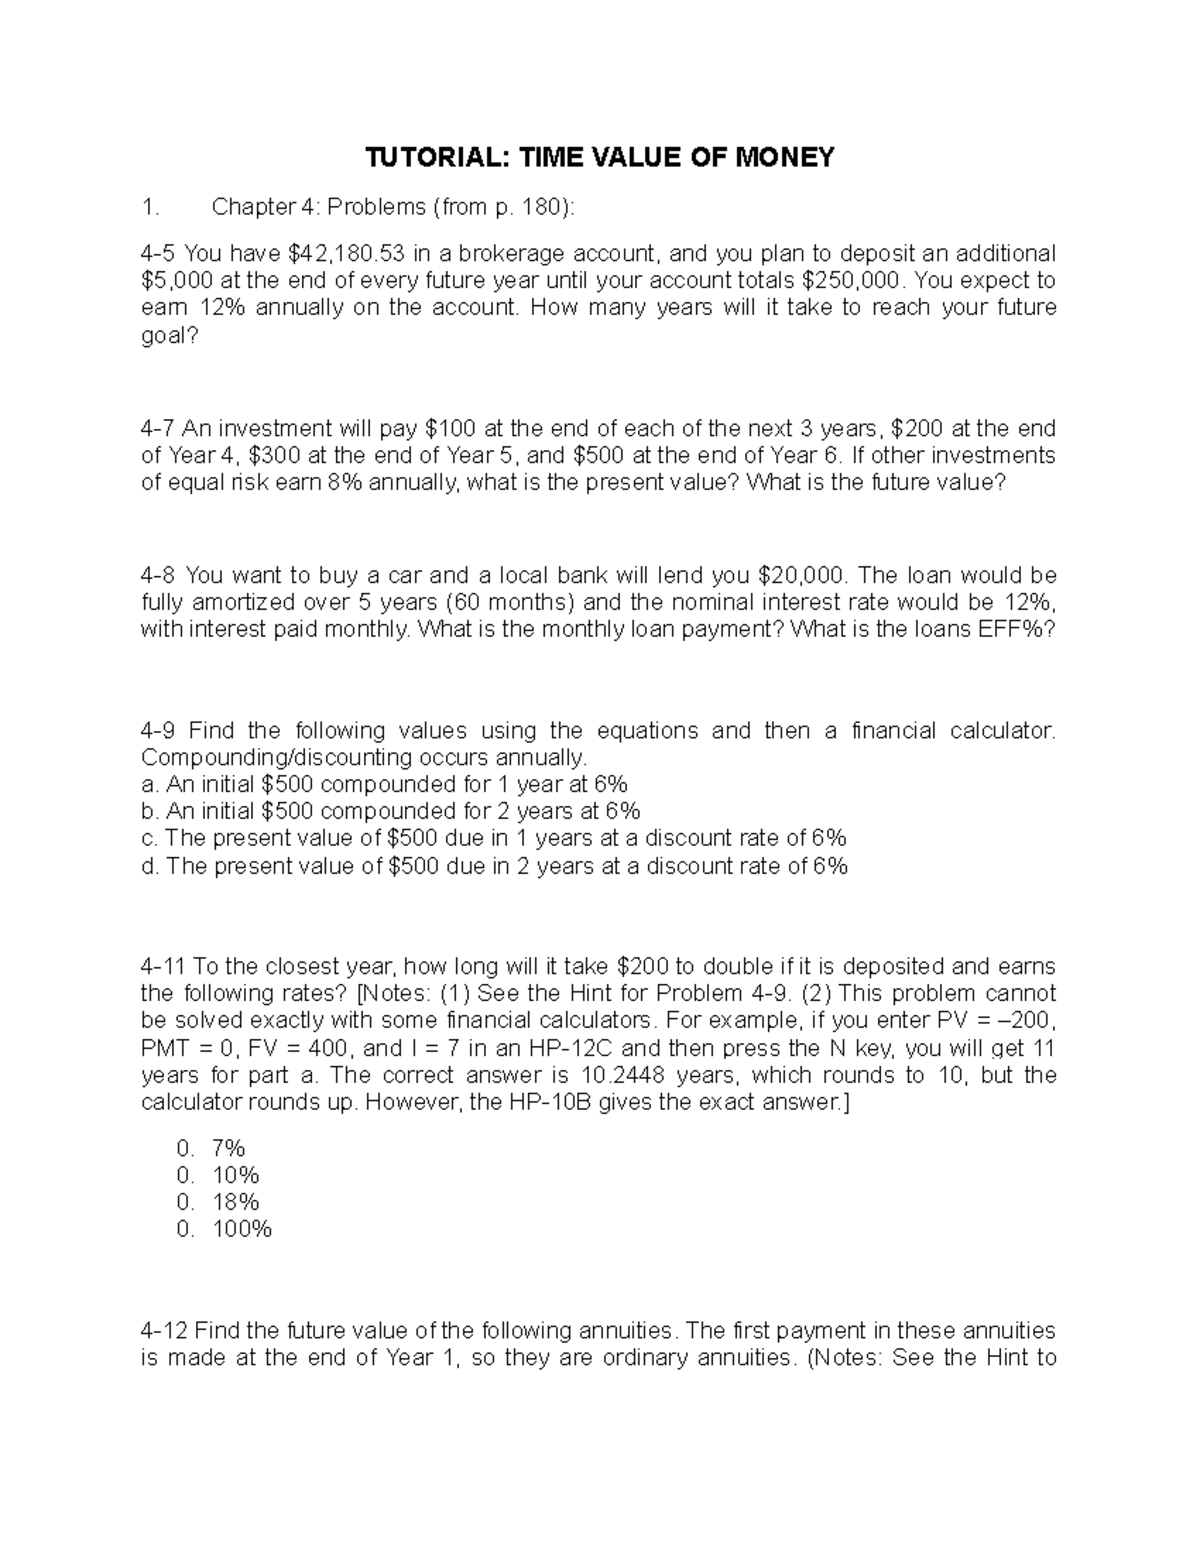
Here is how I actually approach these calculations instead of relying on rote memorization. First, I map out the cash flow timeline. Draw it out, even roughly. Mark every inflow and outflow with its exact timing. I once had a client trying to value a piece of equipment with a maintenance schedule that hit at months 6, 12, 24, and then every 12 months after that, plus a lump-sum overhaul at year 5. The textbook formulas don't handle that pattern. I broke it into separate streams, discounted each one individually, and summed the results. Took me about twelve minutes in Excel instead of twenty minutes of struggling with a financial calculator that only handles uniform series. The second step is getting the rate and period count aligned. This is where most errors happen. If your cash flows are monthly but the rate is quoted annually, you need the periodic rate, not the annual rate. The difference between using 8% and 8%/12 for a five-year monthly calculation is substantial. Over sixty periods, the error compounds into real dollar amounts that matter in negotiations or audit reviews. I also see people forget about the difference between nominal and effective rates. An 18% nominal rate compounded monthly is not the same as 18% effective annually. The effective rate is about 19.56%. Using the wrong one changes every downstream calculation. You can convert between them with the formula (1 + r/n)^n - 1 where n is the number of compounding periods per year.
When payments aren't level, the standard annuity formulas break. That doesn't mean you're stuck. You can use Excel's NPV function for irregular flows, or the XNPV function when the dates aren't evenly spaced. I prefer XNPV because it actually uses the specific calendar dates rather than assuming perfect periodicity. In one case, a client had a loan with payments on the 3rd of each month instead of the 1st, and the accrued interest calculation was off by about two hundred dollars annually because the billing system assumed monthly periods. Switching to date-specific discounting fixed it completely. Another frequent issue is confusing annuity due with ordinary annuity. In an ordinary annuity, payments happen at the end of each period. In an annuity due, they happen at the beginning. The difference is one period of interest. For a five-year lease with monthly payments, that single period shift can change the present value by roughly one percent. It sounds small until you are dealing with a multi-million dollar lease obligation on a balance sheet. Perpetuities come up more often than people expect. A perpetuity just divides the payment by the rate. Forever payments of fifty thousand a year at 7% are worth about seven hundred fourteen thousand. Simple, but I've seen this misapplied to preferred stock valuations where the dividend isn't actually guaranteed forever. Once you factor in call provisions or dividend truncation risk, the perpetuity model gives you a ceiling, not a price. The real value is usually fifteen to twenty percent lower depending on credit quality.
Get the Full Details

For growing annuities, the formula adjusts to account for the growth rate. The present value equals the first payment divided by the difference between the discount rate and the growth rate, adjusted for the number of periods. This comes up in business valuation when projecting cash flows that grow at a steady rate for a finite time before transitioning to terminal value. I typically run both the finite growing annuity and a terminal value calculation separately, then discount the terminal value back to present. It adds clarity and makes it easier to spot when the growth assumption is driving the entire valuation rather than the discount rate. Amortization schedules are another area where mistakes accumulate. The payment formula for a fully amortizing loan is PMT = PV × r / (1 - (1 + r)^-n). People who skip the derivation and just memorize tend to make errors when the problem involves partial periods or balloon payments. I always verify the result by running a quick schedule in a spreadsheet. If the final balance isn't zero or the target residual, something is wrong with the input assumptions. One edge case that trips people up involves discount rates that change over time. A project might face a ten percent cost of capital for the first three years and then drop to eight percent. The standard single-rate formulas don't work here. I handle this by discounting each segment separately and compounding the intermediate values forward. Year one through three cash flows get discounted at ten percent. Year four onward cash flows get discounted first at eight percent to the end of year three, then that result gets discounted at ten percent back to today. It takes three steps instead of one, but it is mathematically correct.
Internal rate of return calculations are where things get genuinely frustrating. IRR assumes reinvestment at the IRR itself, which is almost never realistic. If your IRR is twenty-two percent but you can only reinvest at nine percent, your actual return is materially lower. Modified internal rate of return, or MIRR, fixes this by letting you specify separate reinvestment and finance rates. I use MIRR almost exclusively now. The difference between IRR and MIRR on a typical commercial real estate deal with irregular cash flows can be four to six percentage points. That gap changes whether a deal passes the hurdle rate or gets rejected. For anyone building these models, I'd recommend keeping a separate inputs section at the top of the sheet. Rate, periods, payment amount, growth rate, compounding frequency—all in one place. It cuts debugging time from hours to minutes when a number needs to change. I've spent mornings re-tracing an entire model only to find a hardcoded rate buried in a cell three tabs away. The Excel functions available here are reasonably reliable but they assume consistency. NPV assumes the first cash flow occurs at the end of period one. If your initial investment happens at time zero, you add it separately rather than including it in the NPV function. Put it inside and your result will be wrong. PV has the same behavior. Always check whether your first cash flow is at the beginning or the end of the period before trusting the output.
I also suggest building a simple check column. For any annuity calculation, the sum of the principal repayments should equal the original loan amount or investment. For a discounting problem, adding all the present values back through the future value formula should return approximately the original future amount. Small rounding differences are normal. Large discrepancies mean something is misaligned in the inputs or the formula. When dealing with continuous compounding, the formula shifts to FV = PV × e^(rt). This shows up mostly in academic finance and some derivatives pricing. For practical business work, discrete compounding is almost always more appropriate. Continuous compounding sounds precise but it rarely matches how money actually works in commercial contracts. Banks quote nominal rates with specific compounding periods. Using continuous compounding on a standard loan estimate will give you a slightly inflated number that won't match the contract terms. If you want a reference sheet, I usually build my own based on the situation. The standard formulas cover the basics, but the real value is in knowing which formula applies to which cash flow pattern. A sinking fund calculation is different from a capital recovery calculation even though both use the same annuity factor. Sinking fund asks how much you need to set aside periodically to reach a future target. Capital recovery asks what periodic payment a present amount can support. Swap the formulas and you get opposite answers.

The practical takeaway is this: understand the cash flow pattern before you pick a formula. Map the timeline. Align the rate and periods. Verify with a secondary calculation. Most problems solve themselves once you stop forcing the numbers into the first formula you remember and actually look at what the cash flows are doing.