Building a Practical Time Value of Money Model in Excel
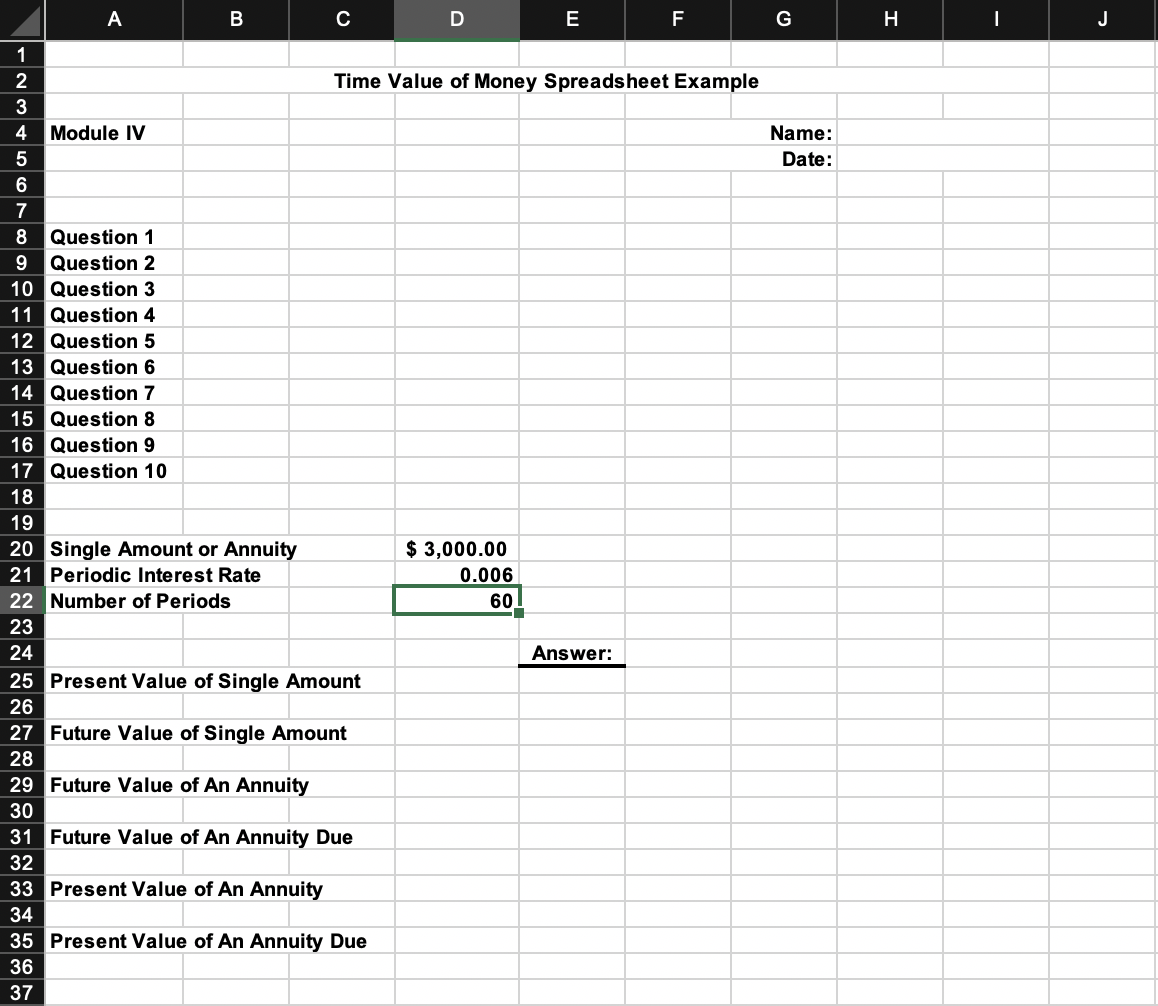
Most people overcomplicate TVM calculations. They throw NPV, IRR, PMT, and FV formulas at a spreadsheet and pray it lines up. The result is usually a mess of mismatched cash flow dates and silently wrong answers. I spent years fixing these models for corporate finance teams, and the pattern is always the same: someone assumed end-of-period payments when the contract said beginning of period, or they mixed up nominal and effective rates without noticing. A TVM spreadsheet breaks down into five variables: present value (PV), future value (FV), payment amount (PMT), interest rate per period (Rate), and number of periods (Nper). You know four of them and solve for the fifth. The Excel functions are straightforward, but the devil is in the assumptions you bake into the cells. Set up your sheet with clear labeled inputs at the top. Put each variable in its own cell with a description next to it. Do not hardcode numbers into formulas. This alone prevents maybe 60 percent of the errors I see in junior analysts' work. Build a section below that lists your cash flows out period by period. When your model shows every individual flow rather than just relying on PV or FV functions, it becomes much easier to audit and explain to someone who did not build it.
The Functions and What They Actually Mean
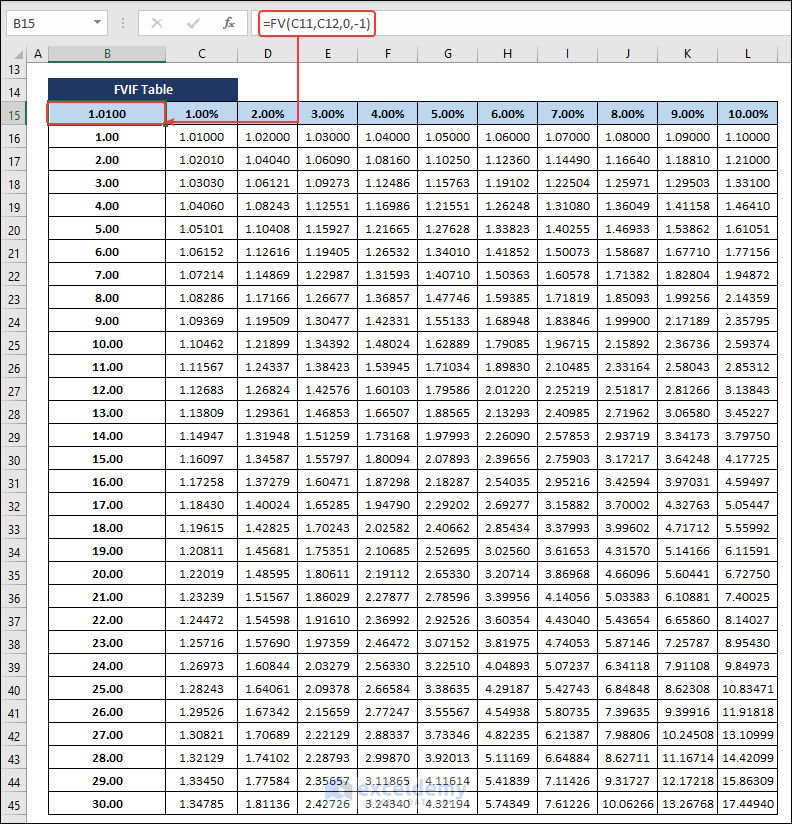
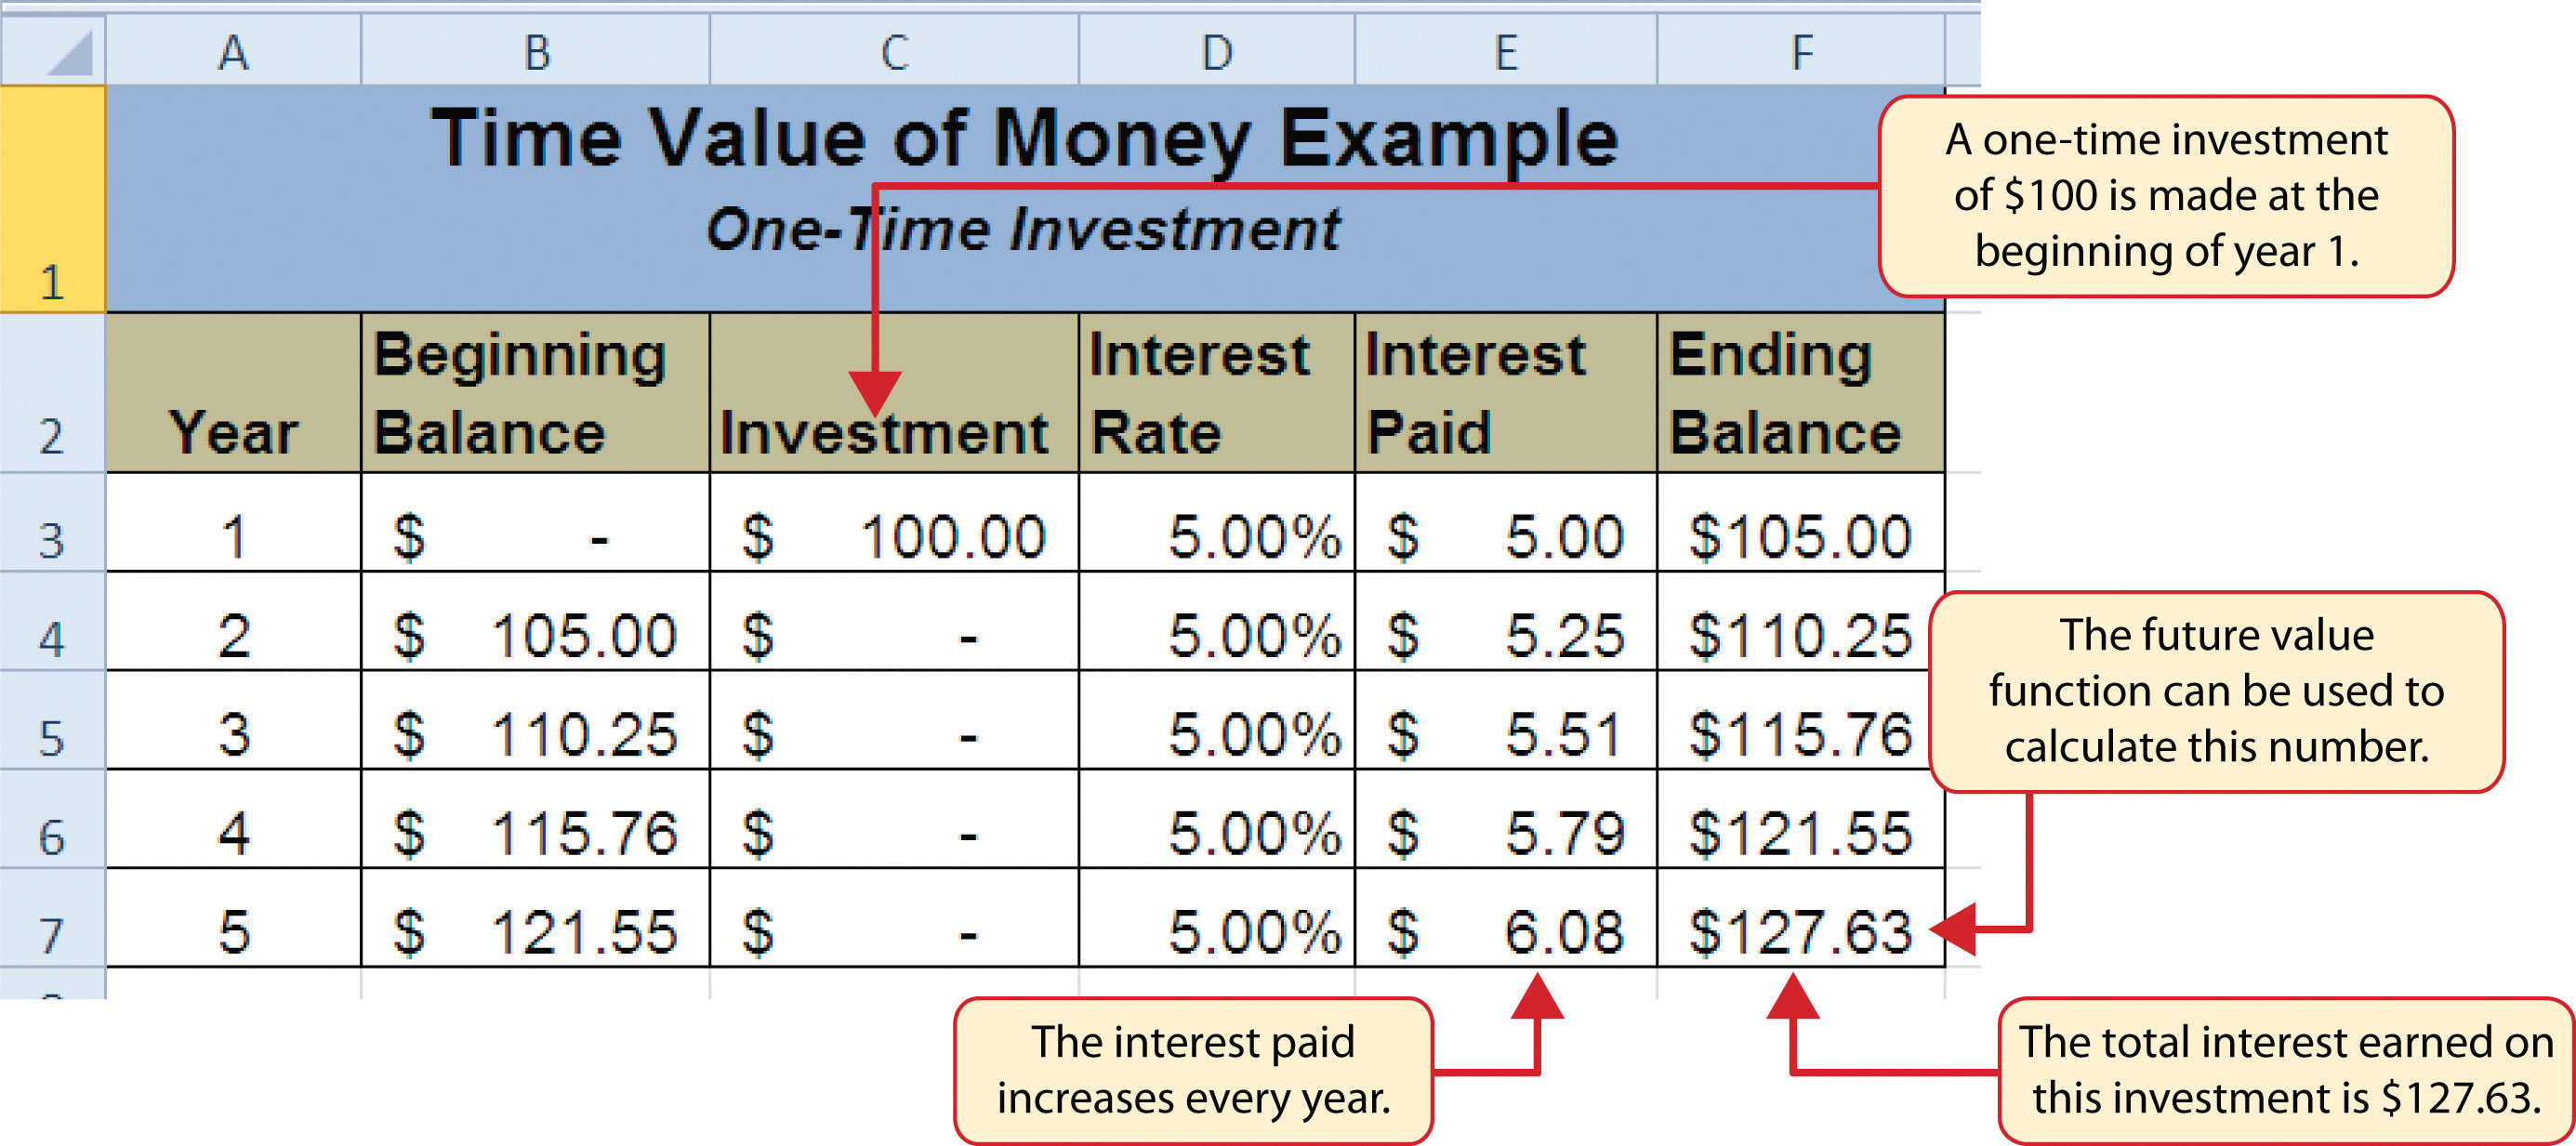
Let me walk through the core Excel functions without pretending this is exciting. PV function returns the present value of a series of future cash flows. Syntax: =PV(rate, nper, pmt, [fv], [type]). The type argument is where people lose money. Type 0 means payments occur at period end. Type 1 means payments occur at period start. If you are modeling a lease with monthly payments due on the first day of each month, you must use type 1. Using 0 instead will shift every payment one period later in your timeline and overstate the present value slightly. The error is small on short durations but compounds noticeably on multiyear schedules. FV function is the inverse. It tells you what a series of payments or a lump sum will grow to at a given rate. Syntax: =FV(rate, nper, pmt, [pv], [type]). I use this mostly for retirement and savings projections, but also for sinking fund calculations where a company sets aside money regularly to repay debt later.
PMT function solves for the periodic payment amount when you know the loan size, rate, and term. Syntax: =PMT(rate, nper, pv, [fv], [type]). One thing beginners miss here: Excel returns the payment as a negative number because it treats cash outflows as negative by convention. Your spreadsheet should either handle the sign consistently or you should wrap it in ABS() so the display reads naturally. Mixing signs is how you end up with a loan balance that goes positive instead of amortizing to zero. NPV and IRR handle uneven cash flows. Syntax for NPV: =NPV(rate, value1, [value2], ...). Important caveat that trips everyone up: Excel's NPV function assumes the first value occurs at the end of period one, not at time zero. If you have an upfront investment at t=0, you must add it separately outside the NPV function. I used to see this mistake in pitch books all the time. The fix is simple: =NPV(rate, period1_through_periodN) + initial_outlay. Do not feed the initial outlay into the NPV function itself. IRR finds the discount rate that makes NPV equal zero. Syntax: =IRR(values, [guess]). The guess argument is optional but helpful when cash flows flip signs multiple times, which creates multiple mathematical solutions. Providing a reasonable guess narrows the search and avoids getting back some bizarre rate like 47 percent when the answer should be near 12 percent.
Get the Full Details
Setting Up the Model Step by Step
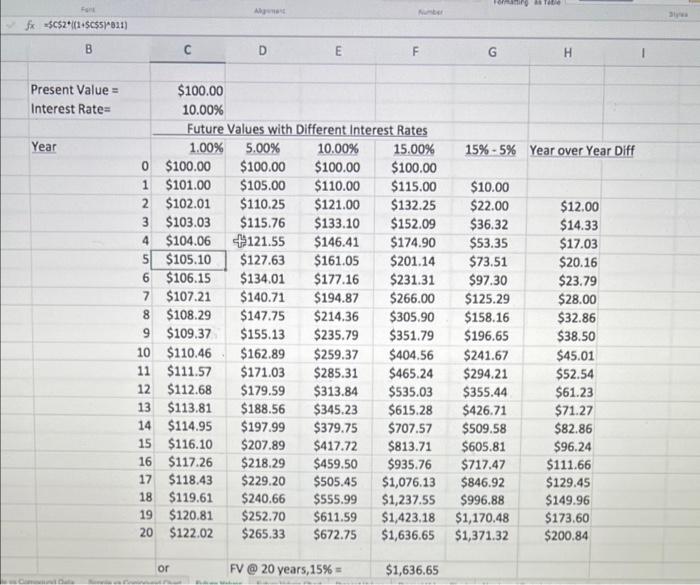
Start with a clean input section. Label each variable. Give them conditional formatting rules so negative values flash red and zero values are easy to spot. Below that, build a period-by-period table with columns for period number, cash flow date, inflow, outflow, and net cash flow. Use DATE functions to tie each period to an actual calendar date instead of relying on sequential integers. Real projects have irregular dates, and using plain integers quietly introduces rounding errors that surface only when you cross-reference to external schedules. For the discounting calculation, I prefer explicitly building the PV of each cash flow row rather than using a single NPV function. This means a column with a formula like =NetCashFlow / (1 + Rate)^PeriodNumber. The total of that column should match your NPV result. If it does not, you have a timing mismatch somewhere. This double-check takes maybe three extra minutes but catches subtle errors that would otherwise sit invisible until a stakeholder asks a question you cannot answer quickly. When modeling annuities, separate the constant payment stream from any irregular adjustments. Keep them in different sections of the sheet. Combining them makes the model fragile because any change to the base assumption forces you to redo the entire schedule.
A Real Problem I Encountered and How I Fixed It
Once I was reviewing a corporate lease model where the lessor had structured quarterly payments with a balloon payment at the end. The analyst had used the PV function with an annual rate and quarterly periods without adjusting the rate. The resulting present value was off by roughly four percent. That sounds small until you are dealing with a half-million dollar lease. The fix was converting the annual nominal rate to a quarterly rate by dividing by four, which is correct for a nominal rate compounded quarterly. But here is the subtlety that matters: if the contract specifies an effective annual rate instead of a nominal rate, you need to convert using (1 + EffectiveRate)^(1/4) - 1. I missed this distinction on that project for about two days before someone noticed the discrepancy. Now I always verify whether a stated rate is nominal or effective before plugging anything into a TVM function. Rate and period matching is the biggest one. If your payments are monthly, your rate must be monthly and your periods must be monthly. Mixing an annual rate with monthly periods produces garbage. This is the error I encounter most frequently in entry-level models. The second is confusing IRR with modified IRR. Standard IRR assumes all interim cash flows are reinvested at the IRR itself, which is almost never true in practice. MIRR lets you specify separate reinvestment and financing rates and usually produces a more realistic picture. The difference between IRR and MIRR can be several percentage points on longer projects with large intermediate outlays. A third issue is the assumption of constant discount rates. TVM formulas assume a single rate applies across all periods. Real world discount rates change. If you need accuracy, you should build a scenario where each period has its own discount rate and calculate PV manually by discounting each cash flow individually rather than relying on PV or NPV functions. It is more work but it is also more honest.
Limitations You Should Accept Upfront
A TVM spreadsheet is only as good as its assumptions. It cannot account for inflation unless you build it in explicitly. It does not handle tax effects, transaction costs, or credit risk changes over time. If you are making decisions that depend on these factors, the spreadsheet will give you a baseline number that looks precise but is actually misleadingly narrow. The model gives you a number. It does not tell you whether that number is right for your specific situation. Anyone treating TVM outputs as absolute truth rather than directional guidance is skipping a critical step. For projects with highly uncertain cash flows, scenario analysis or Monte Carlo simulation is more appropriate than a deterministic TVM model. A spreadsheet will happily produce an IRR for a project whose revenue streams are based on guesses. The confidence you place in that IRR should reflect the quality of the underlying assumptions, not the precision of the formula.

When to Use a Template Versus Building From Scratch
Prebuilt templates exist for common scenarios: loan amortization, bond valuation, retirement planning, lease analysis. They save time if your use case is standard. I usually recommend building your own template rather than downloading one. A downloaded template carries assumptions you may not notice, and fixing someone else's structural errors is harder than writing the thing correctly the first time. A self-built model is easier to explain, easier to audit, and easier to adjust when your actual parameters diverge from the template defaults. Take a $100,000 loan at 6 percent annual interest with monthly payments over 5 years. The monthly rate is 0.5 percent. The number of periods is 60. The PMT function gives you =PMT(0.005, 60, -100000), which returns approximately 1,933.28. You then build an amortization table where each row shows the period number, beginning balance, payment, interest portion, principal portion, and ending balance. The interest portion equals the beginning balance multiplied by the monthly rate. The principal portion equals the payment minus the interest portion. The ending balance equals the beginning balance minus the principal portion. Repeat for all 60 periods. The final row should show a balance of zero or within a few cents due to rounding. This manual schedule approach is worth doing even when the PMT function gives you the answer directly. It reveals how the interest-to-principal ratio shifts over the life of the loan. Early payments are mostly interest. Later payments are mostly principal. If you prepay in the first year, you save significantly more interest than if you prepay in year four. That insight does not come from the PMT function alone. It comes from seeing the schedule laid out period by period.
Quick Reference for the Core Functions
PV = =PV(rate, nper, pmt, [fv], [type])
FV = =FV(rate, nper, pmt, [pv], [type])
PMT = =PMT(rate, nper, pv, [fv], [type])
NPV = =NPV(rate, cash_flow_values)
IRR = =IRR(cash_flow_values, [guess])
MIRR = =MIRR(values, finance_rate, reinvest_rate) Keep this list somewhere visible while you build. Memorizing the syntax by heart wastes more time than keeping a reference open. The arguments that cause the most trouble are fv, type, and the handling of the initial cash flow in NPV. These are the ones to double-check every time you switch between functions.
Final Thoughts on Building Reliable TVM Models
The goal is not to make the spreadsheet look impressive. The goal is to make it correct, auditable, and easy to modify when assumptions change. A clean TVM model with clear labels, explicit assumptions, and a period-by-period cash flow schedule will serve you better than a single sheet crammed with nested formulas that produce the right answer for the wrong reasons. Validation matters more than complexity. Check your results against a known benchmark or a second method whenever possible. If two approaches give the same answer, your model is likely sound. If they diverge, you have found the error before it becomes someone else's problem.