What You Actually Need to Know About Times Interest Earned
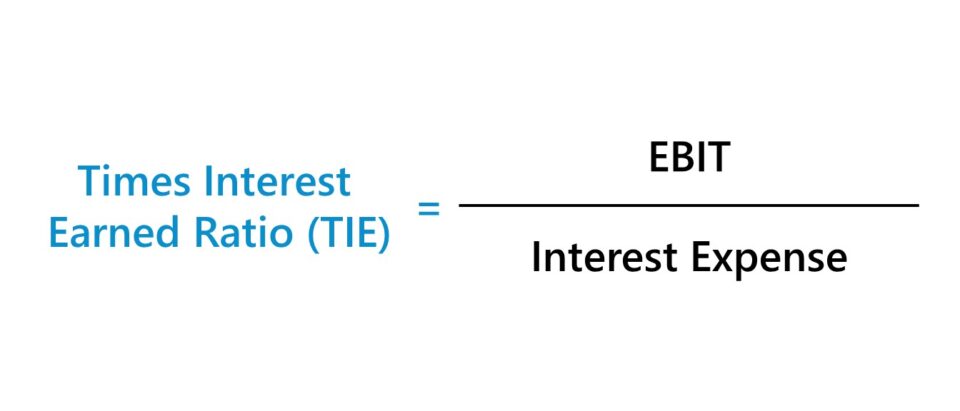
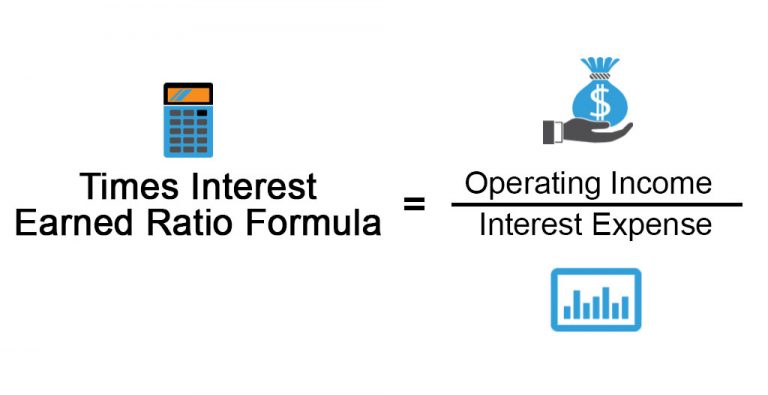
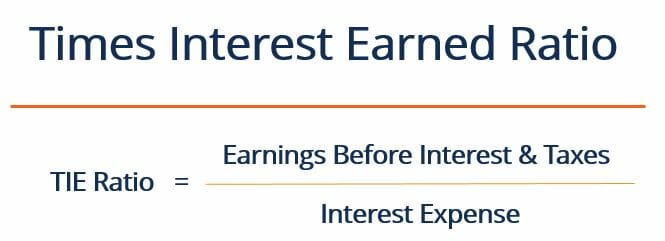
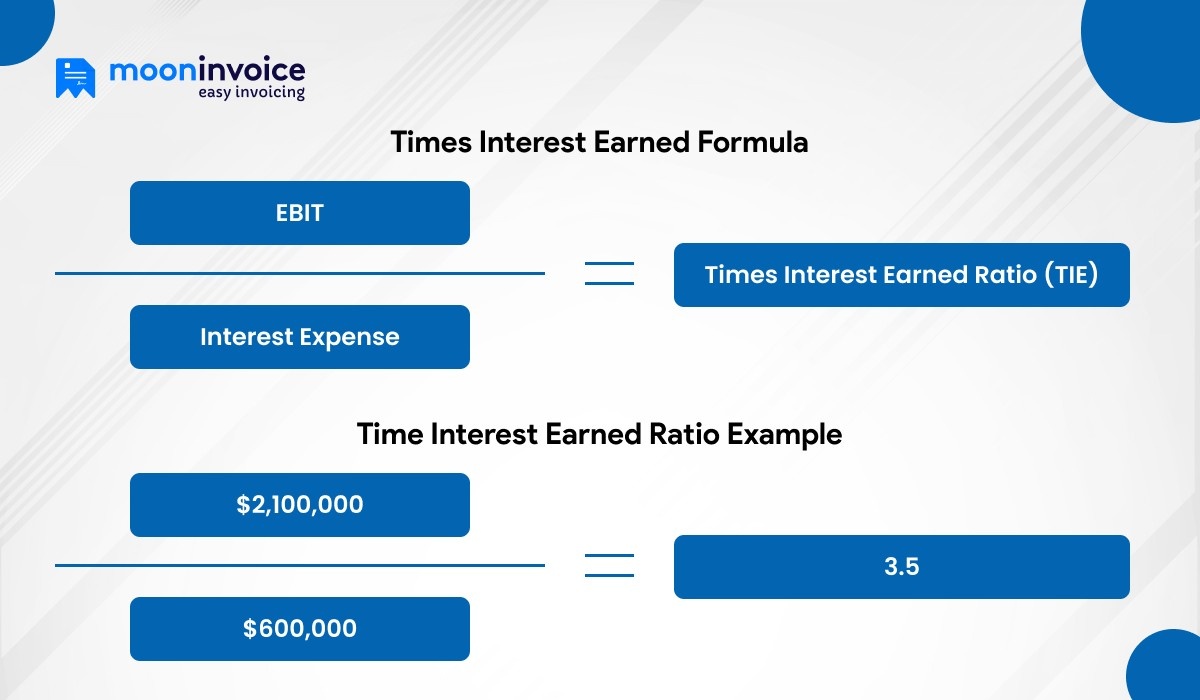
The Times Interest Earned Ratio Formula is straightforward arithmetic, but the way it's applied in real financial analysis is where things get messy. Credit analysts use it to measure whether a company can actually service its debt from operating earnings. If you're building a model or reviewing a balance sheet, here's how it works and where people routinely mess it up. Calculate it by taking earnings before interest and taxes, dividing that number by total interest expense. The formula is EBIT divided by Interest Expense. That's it. The result tells you how many times over a company could cover its interest obligations with current operating profit. A ratio above 2.5 is generally considered comfortable for investment-grade companies. Below 1.5 and lenders start getting nervous. I spent years working through distressed debt situations, and I've seen this ratio misread more times than I can count. The biggest mistake people make is using net income instead of EBIT. Net income includes interest expense after it's been deducted, so it understates the company's actual ability to pay. You have to go back up the income statement to the operating profit line. I had a situation once where a company reported a net loss but had an EBIT-positive TIE ratio of 1.8. On the surface it looked distressed because of the bottom line, but the interest coverage was actually manageable. The net loss came entirely from asset impairment charges, not operating problems. That distinction mattered when we were deciding whether to buy the bonds at a discount.
Here's a practical example. Company A has revenue of five million dollars, cost of goods sold at three million, operating expenses at one point two million, and interest expense of three hundred thousand. EBIT comes to eight hundred thousand. Divide eight hundred thousand by three hundred thousand and you get a TIE ratio of 2.67. The company covers its interest payments almost two and three-quarter times over. That's a decent position but not bulletproof if revenue dips even slightly. The counter-intuitive part that most beginners miss is that a higher ratio doesn't always mean better credit quality. I've analyzed companies with TIE ratios above 10 that were actually in worse shape than peers sitting at 4. This happens when a company has minimal debt, so the denominator is tiny. A high TIE in that case is just telling you the company isn't leveraging much, not that it's swimming in cash. The metric needs context. Compare it to industry peers, look at the absolute interest payment amount, and check whether EBIT is growing or shrinking. A declining EBIT with a stable TIE ratio means the company is actively deleveraging, which could be a warning sign if management is cutting necessary investments to reduce debt. Another edge case I ran into repeatedly involves capitalized leases and off-balance-sheet financing. After ASC 842 and IFRS 16, most lease obligations now appear on the balance sheet, but older financial statements or certain jurisdictions still have operating leases that don't show up as debt. When I was underwriting a commercial real estate deal a few years back, the reported TIE ratio looked fine at 3.2. Once I added back the operating lease payments to both the numerator and denominator, the adjusted TIE dropped to 1.9. That adjustment changed our entire risk assessment on the transaction. Always check whether lease obligations are embedded in interest expense or sitting separately.
There are also situations where EBIT itself is problematic as the numerator. For capital-intensive businesses, depreciation and amortization are large non-cash charges that inflate EBIT without generating cash. Some analysts prefer to use EBITDA divided by interest expense in those cases, though that's technically a different metric. The choice between EBIT and EBITDA as the numerator can shift the ratio by a full point or more in heavy industry sectors. I usually run both and flag the difference rather than picking one arbitrarily. The main limitation of this ratio is that it's a snapshot. It tells you what happened last period, not what will happen next quarter. A company can have a strong TIE for three consecutive years and then suddenly face a contract loss or supply chain disruption that eliminates its margin. I always pair TIE with a forward-looking view, pulling in guidance data, order backlogs, and sector trends. The ratio alone won't save you from a deteriorating business. Another practical bottleneck is the treatment of interest itself. Some companies report interest expense net of capitalized interest, while others gross it up. If the company is in construction or development, the reported interest expense might be far lower than the economic cost of borrowing because a significant portion is being capitalized into assets. I learned this the hard way on an infrastructure project where the TIE ratio looked like 5.0 until I discovered that only about 40 percent of the actual borrowing costs were being expensed. The rest was sitting on the balance sheet in construction in progress. Adjusted for the full interest burden, the real coverage ratio was closer to 2.1.
Get the Full Details
If you need a reliable way to calculate this quickly, you can pull the numbers directly from any standard income statement. Look for the line item labeled earnings before interest and taxes or construct it by taking operating income and confirming interest expense is listed below it. Most financial data platforms like Bloomberg or even free sources like Yahoo Finance will provide pre-calculated interest coverage ratios, but they don't always adjust for the lease and capitalization issues I mentioned. Double-check the inputs before trusting the output. The formula itself doesn't require any special software. A spreadsheet with basic addition and division will handle it. The skill is in knowing which line items to use and when to adjust them. That's what separates a competent analysis from a lazy one.