Practical Personal Finance Moves That Actually Work
Most people approach personal finance from the wrong angle. They try to track every coffee, obsess over budget spreadsheets, and then quit when they see they still aren't saving enough. I spent years watching clients do this before I figured out what the leverage points actually are.
The single biggest mistake I see is the order of operations. People save what's left after spending. That almost never works because spending is infinite and income is finite. Instead, automate the savings first. Set up a direct deposit split so 20% goes straight into a separate account before you ever see it. I had a client in 2019 who was making $72,000 a year and couldn't figure out where his money went. After switching to automatic allocation, he hit $40,000 in liquid savings in 18 months without changing a single habit. The trick is that you don't notice the money when it never hits your checking account.
The Core Principles Behind Tips For Finance Best
These aren't theories pulled from blogs. They're the patterns that show up consistently across completely different income levels and life situations.
Pay yourself first, but define "first" precisely. Automate three things on payday: retirement contributions above any employer match, a taxable brokerage account, and an emergency fund until it hits six months of expenses. After that, redirect the emergency fund payments into additional investing. This removes decision fatigue entirely. You're not choosing to save each month. The choice was made months ago by your automation settings.
The debt payoff strategy matters far less than people think. Whether you use avalanche or snowball, the mathematical difference over a typical portfolio is small. What actually moves the needle is the rate at which you eliminate high-interest debt, not the order. I once worked with someone who had $14,000 in credit card debt at 24% APR and $48,000 in student loans at 5.2%. She chose the snowball method because of the psychological wins, paying off three smaller cards first. She saved roughly $340 in interest compared to pure avalanche. That's real money, but it's also negligible relative to the overall strategy. Pick the method that keeps you consistent. Consistency beats optimization every time.
Investing should be almost entirely boring. A low-cost total market index fund like VTSAX or FZROX handles 90% of what individual investors need. Attempting to pick stocks or time the market has a 94% failure rate for retail investors according to SPIVA data. I watched a client in 2021 try to day-trade meme stocks after seeing results on social media. He lost $8,200 in eleven days. Meanwhile, his brother put the same amount into an S&P 500 index fund and had it grow to about $11,000 by early 2024. Not a competition, just two different decisions with two different outcomes.
Edge Cases That Break the Standard Advice
Here's something most guides won't tell you. The standard advice assumes you have a steady paycheck. It falls apart quickly if your income is irregular. When I work with freelancers or commission-based earners, I switch to a zero-based budget using a rolling average system. Instead of budgeting off last month's income, you budget off the trailing three-month average and adjust weekly. This prevented one client from overdrafting during a slow quarter in 2022. He was a graphic designer with income ranging from $3,200 to $11,000 per month. His original budget was based on a $7,000 average, so when January came in at $3,800, he was short by nearly $2,000. The rolling average caught this two weeks early instead of three months too late.
Another overlooked area is the interaction between tax-advantaged accounts and your actual tax situation. Maximuming out an IRA is great advice, but if you're in a high state with no income tax and your employer offers a strong 401k match, the sequence matters. Contribute enough to the 401k to get the full match first. That's an immediate 100% return on that portion. Then max the IRA. After that, go back and increase 401k contributions. I've seen people skip the 401k match because they were so focused on "maxing every account" that they left free money on the table.
Specific Tactics for Different Income Levels
Making under $50,000 a year: focus on increasing income before you obsess over cutting expenses. At this level, the gap between income and necessary spending is too small for budgeting alone to close it meaningfully. A side income of even $400 a month changes everything. The math is simple. Budgeting harder at this income level hits diminishing returns fast because your essential costs are already consuming most of what you make.
Making $50,000 to $120,000: this is where automation pays the highest dividends. Your income is predictable enough to set and forget systems, and your margin for error is large enough that small improvements compound quickly. The 50/30/20 framework actually works well here as a starting point, even if you refine it later.
Making over $120,000: the problems shift from saving enough to managing complexity. Tax optimization, estate planning, and investment diversification become the real challenges. A CPA who understands your situation specifically matters more at this level than any budgeting app.
What Most People Get Wrong About Emergency Funds
The standard recommendation is three to six months of expenses in a high-yield savings account. That's correct for most people. But the size should scale with your risk profile. If you have job insecurity, dependents, or irregular income, aim for eight to twelve months. I worked with a single parent in healthcare who had two young children and a contract position. She kept six months in savings and felt secure. Then her department restructured, and she was laid off. Her six months lasted exactly five months because medical premiums continued during the search. She ended up using a credit card for one month of expenses, which set her back. If she'd aimed for eight months, she would have been fine. The difference between five and eight months of expenses is usually just a few hundred dollars a month in savings. It's worth the extra effort.
The Trade-Offs Nobody Talks About
Maximizing retirement contributions reduces your current liquidity. If you put 25% of your income into a 401k and an IRA, you might not have the cash for a house down payment or a major expense without taking penalties or loans. This isn't necessarily bad, but it's a real constraint. Before going aggressive on retirement, make sure you have at least three months of expenses liquid. Then consider whether a down payment is on the horizon.
Similarly, aggressively paying down low-interest debt while also investing is usually suboptimal mathematically. If your mortgage is at 3.5% and your expected market return is 7%, math says invest. But if that 3.5% mortgage payment is the thing keeping you from sleeping at night, pay it down. Peace of mind has a quantifiable value in reduced stress and better decision-making.
The biggest limitation of nearly all personal finance frameworks is that they assume rational behavior. They don't account for lifestyle inflation, social pressure, or the emotional aspects of money. I've seen people who followed every rule perfectly still struggle because they never addressed their relationship with spending. A therapist or financial coach who focuses on behavior can sometimes do more in six sessions than a budgeting app can do in six years.
Tools That Actually Help
YNAB works well for people who need to manage tight margins and want real-time visibility into every dollar. It has a learning curve of about two weeks, after which most users report feeling significantly more in control. However, it requires active daily use. If you're going to forget to log transactions for three days, you'll lose the benefit.
Mint is shutting down, which is forcing a migration. Tiller Money and Empower are the closest functional replacements, though neither replicates Mint's bill tracking features perfectly. For pure net worth tracking, Empower is strong. For budgeting, Tiller's spreadsheet approach gives you more control but requires more setup time.
For investing specifically, Vanguard, Fidelity, and Charles Schwab all offer comparable low-cost index funds. The differences between them are marginal for most investors. Pick the one where you feel most comfortable and where fees are lowest for your specific account type. Fee differences of 0.02% don't move the needle meaningfully over a lifetime.
A Realistic Timeline
If you're starting from zero, the first year should focus on building the emergency fund and stopping high-interest debt accumulation. Month one: set up automation. Month two to six: build the emergency fund. Month six to eighteen: tackle debt while investing the minimum to get employer matches. After that, scale investments and optimize taxes. This isn't a race. Someone who takes three years to get to a solid foundation will end up in a better position than someone who burns out in six months trying to do everything at once.
The people I see succeed long-term aren't the ones with the best strategies. They're the ones who stick with a mediocre strategy for ten years. A decent budget followed consistently beats a perfect budget abandoned after three months. The same applies to investing, debt payoff, and every other component of personal finance.
Gallery Tips For Finance Best
29 Best Personal Finance Tips for Beginners and Beyond
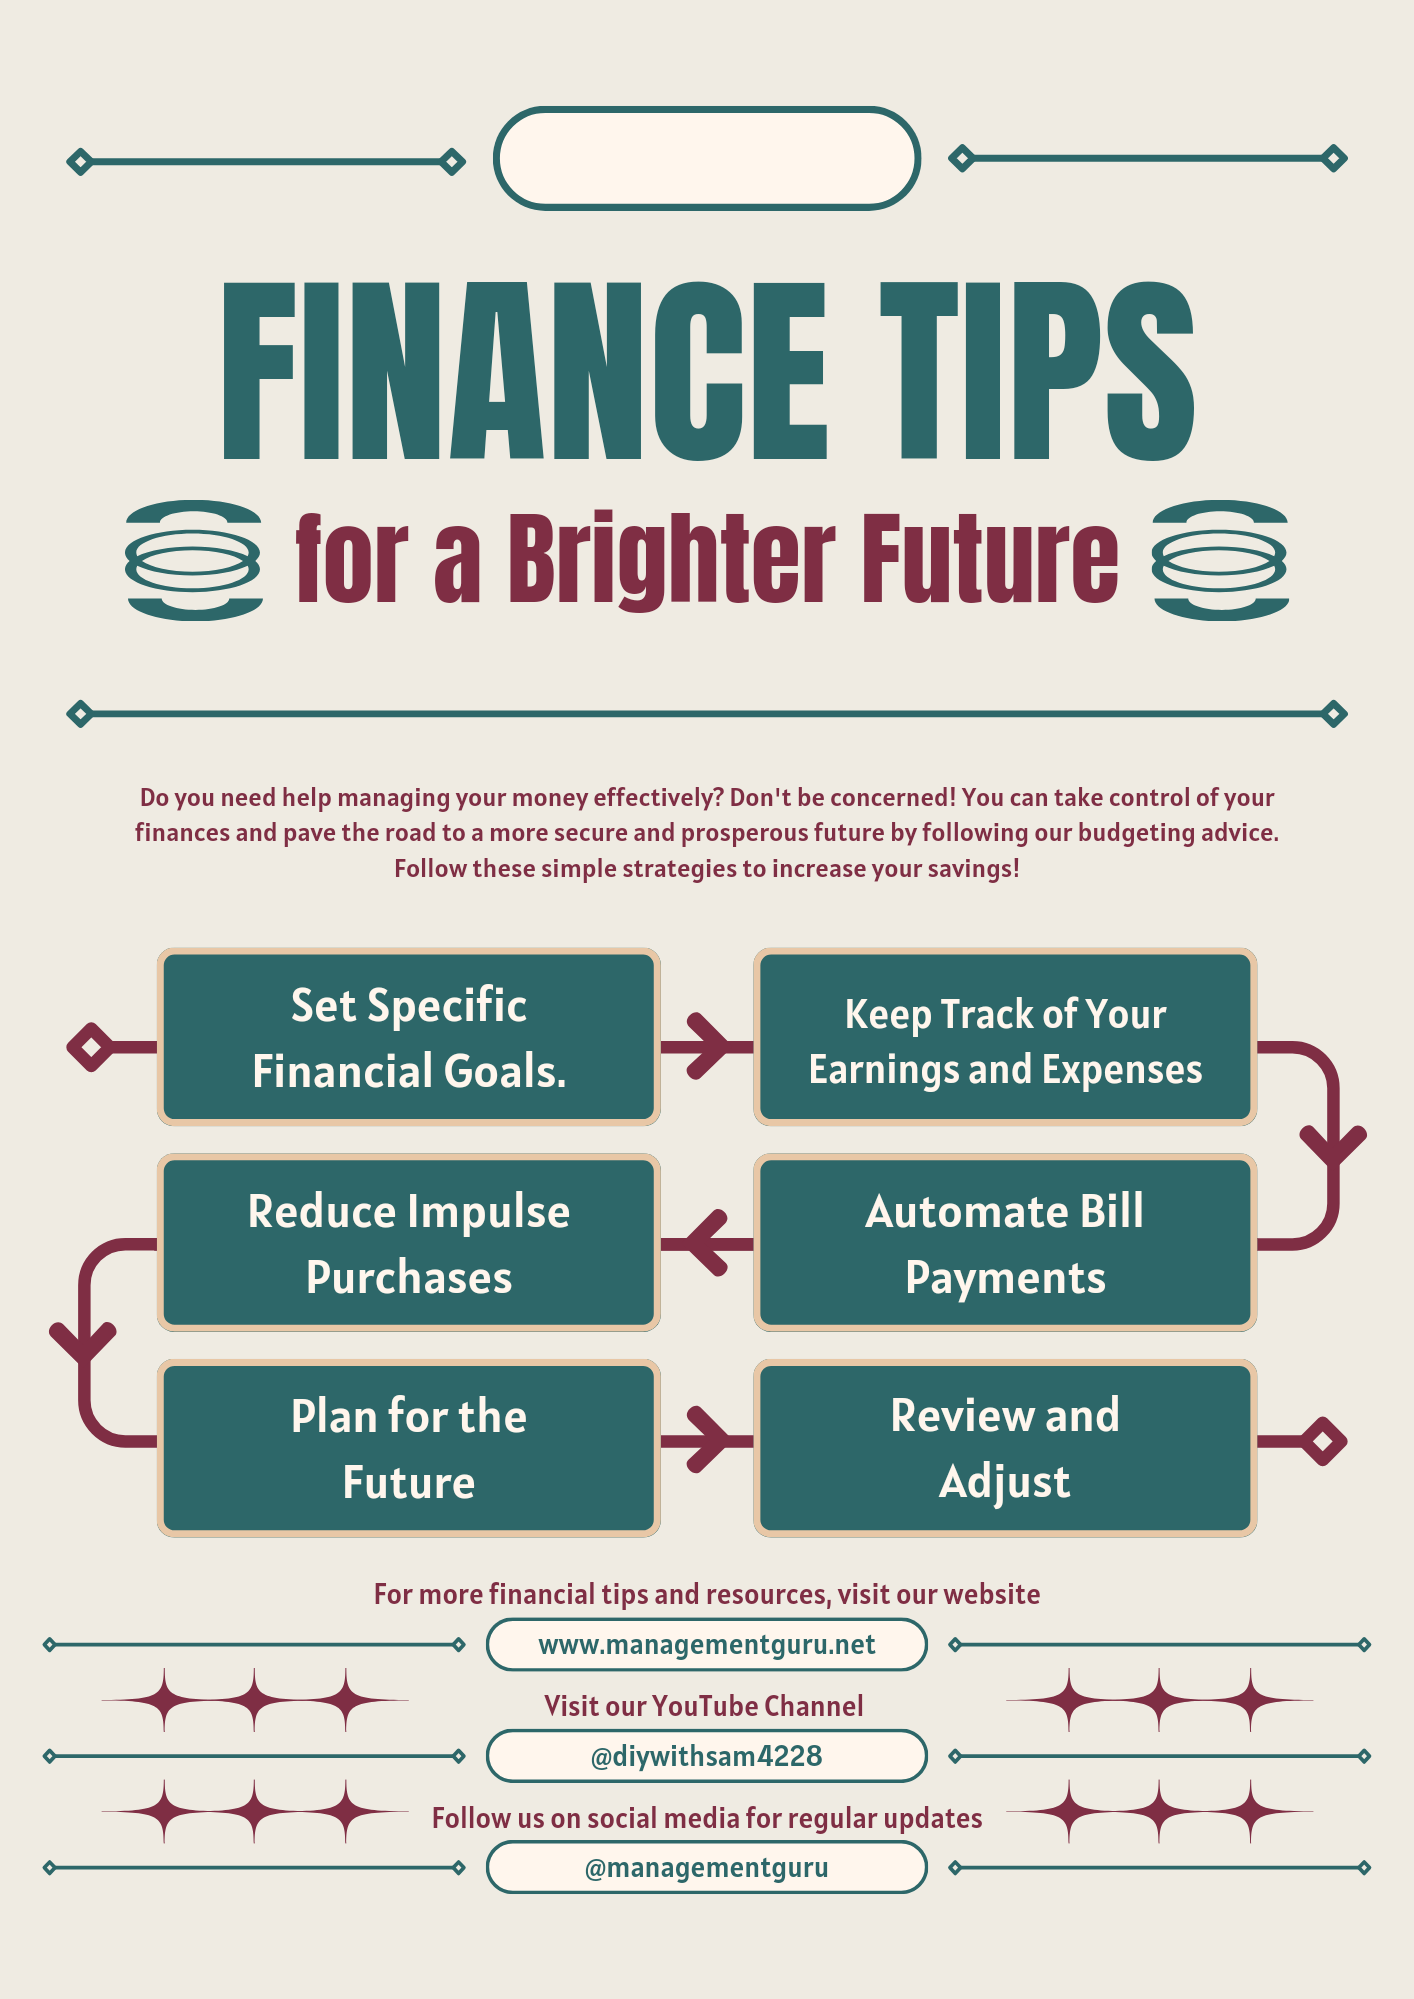
10 Best Personal Finance Tips - Management Guru | Management Guru
45 personal finance tips for your financial well being – Artofit
Personal Finance Tips: 7 Expert Strategies for Financial Success
Best 20+ Personal finance ideas on Pinterest | Finance, Budgeting tips and Financial planning