How to Actually Approach Trading US Treasuries Alongside Equities
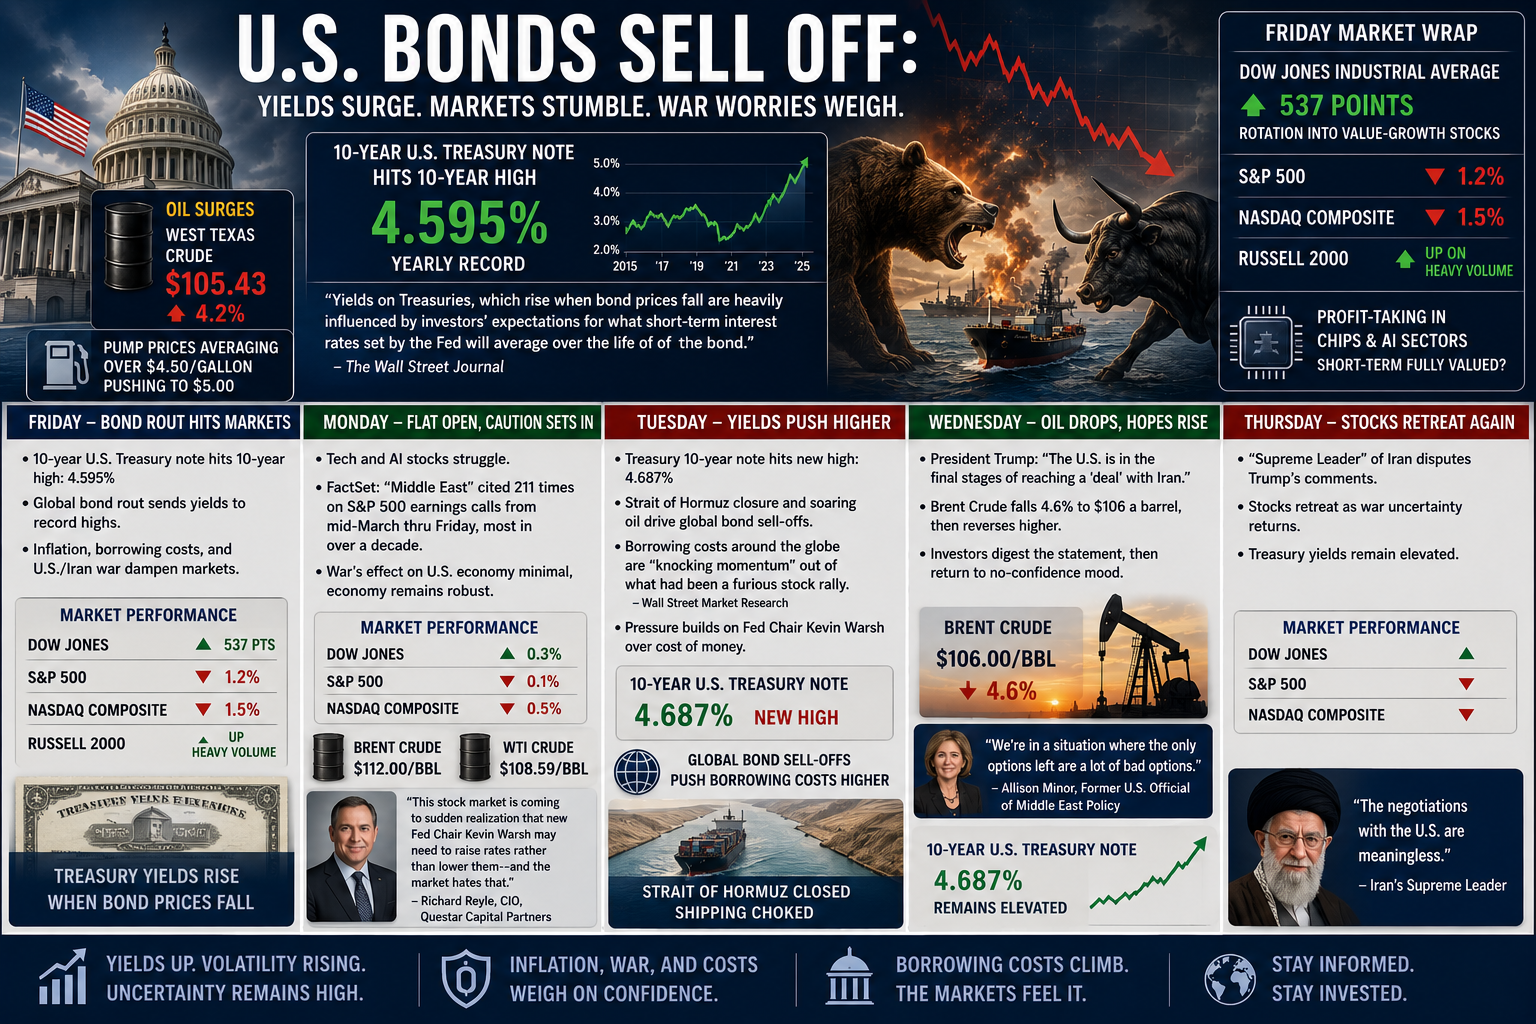
I used to run a systematic macro desk and the thing nobody tells you is that bonds and stocks don't just move inversely. They move against each other on different timeframes and for completely different reasons. When inflation data comes out, rates rip higher and equities sell off simultaneously. When there is a flight to safety during a geopolitical scare, both asset classes can rally together because everyone is dumping risky stuff and parking it in the 10-year. Understanding when each regime applies is more important than any individual indicator. The first thing most people get wrong is assuming the Fed Funds Rate is the rate that matters for bond pricing. It isn't. The yield curve is what moves markets. When the 2-year yield jumps 15 basis points and the 10-year barely moves, that is a different signal than when the 10-year runs 25 points while the 2-year stays flat. The steepening versus flattening dynamic tells you whether the market is pricing in growth or pricing in stress. I watched traders lose money on both sides of that trade repeatedly in 2022 because they were only looking at the headline rate decision and ignoring the curve. For equities, the correlation between duration risk and stock valuations is real but inconsistent. During quantitative tightening phases, long-duration stocks like unprofitable tech tend to underperform short-duration value names. During easing cycles, the reverse happens but with a lag of roughly three to six months. You cannot just buy growth because the Fed pivoted. The market has already priced in the pivot within days, usually before the actual announcement. I learned that the hard way when we ran into a situation where the FOMC cut rates in a split vote and the market sold off because the cut was interpreted as a sign of distress rather than a stabilizing move. That day, the S&P 500 dropped nearly 2 percent and the 10-year yield actually rose because Treasuries were being sold to cover margin calls in the equity book.
Here is the practical setup I ended up using for most of the year. I maintain a watchlist of three Treasury spreads: the 2s10s curve, the 5s30s butterfly, and the TIPS breakeven rate. I also track the MOVE index alongside the VIX. When the MOVE spikes above 130 and the VIX is below 20, that is almost always a bond-driven move hitting the equity market, not the other way around. That meant reducing equity duration, not increasing it. The inverse is also true. When the VIX is elevated but the MOVE is calm, the stress is equity-specific and shorting bonds as a hedge becomes counterproductive because the flight-to-safety bid is already baked into yields. The biggest practical headache I ran into involved the mismatch between bond settlement and equity execution timelines. Bond trades settle T plus one while most equity trades settle T plus two now, and that asymmetry creates liquidity traps around month-end and quarter-end. I encountered this in April 2023 during the regional banking stress. We had to roll a large treasury position and the bid-ask spread on the 10-year note widened to about 8 basis points from a normal 1.5. Meanwhile, the SPY was trading with sub-penny spreads. The only workaround was to break the trade into smaller chunks over 45 minutes and use limit orders priced at the mid-market instead of chasing the tape. Waiting even five minutes would have added roughly 12,000 dollars in slippage on a 50 million dollar position. That taught me to never try to execute large bond flows during economic data releases unless you have direct access to a principal desk. Another counter-intuitive point is that yield does not always predict equity direction the way textbooks say it does. Rising yields can coexist with rising stocks if the rise is driven by strong economic growth expectations rather than inflation expectations. What matters is the decomposition. Real yields are the real constraint on equity valuations. If nominal yields are climbing but real yields are stable or falling, equity multiples can actually expand. If real yields are climbing rapidly, that is when P/E compression hits. I tracked this by comparing the 10-year nominal yield against the 10-year TIPS yield in real time. The spread between them is what you should be watching, not the headline number.
On the tools side, most retail traders are working with data that is 15 minutes stale for bond prices. Free platforms will show you the last traded price on the 10-year note from earlier in the session while the market has moved 20 basis points. If you are trying to pair trade bonds and stocks using free data, you are trading against an information disadvantage that institutional desks exploit routinely. The minimum viable setup involves a terminal or a subscription service that provides near-real-time benchmark yields, a reliable source for breakeven inflation rates, and a way to calculate duration exposure across your combined portfolio in one view. Something like a basic spreadsheet model that takes your equity beta and your bond DV01 and shows you the net sensitivity to a 25 basis point move in the 10-year. That model typically takes about 45 minutes to build properly but saves hours of guesswork during volatile periods. There are also specific times of year when bond and equity correlation breaks down predictably. The December rebalancing window in particular causes artificial volatility in both markets because institutional accounts adjust their allocations to hit target weights. During the final two weeks of December, you will see correlation coefficients between the S&P 500 and Treasury yields swing from negative to positive without any fundamental reason. Trading the signal during that window tends to produce mediocre results. The same applies to June and September when certain pension funds and endowments do their semi-annual rebalancing. Position sizes matter less than timing, and most models do not account for this calendar effect. If you are building a combined portfolio, the allocation question is simpler than people make it. A 60-40 equity to bond split that uses intermediate Treasuries as the fixed income component is not a static allocation. The bond portion needs to be adjusted based on where the 10-year yield sits relative to its historical average. When the 10-year yield is above 4.5 percent, the bond portion carries meaningful income and lower duration risk, so you can afford a slightly higher equity weighting. When the 10-year drops below 3 percent, the bond portion becomes a yield trap with high duration risk and you should reduce equity exposure regardless of what the equity valuation metrics say. I know that sounds like it contradicts value investing principles, but it is about managing the total portfolio risk, not picking individual winners.
Get the Full Details
Stop orders in the bond market behave differently than in equities. A stop loss on a Treasury position does not execute at your stop price during a fast market. It executes at the next available price, which can be several basis points away. I once placed a stop at 4.20 percent on a short treasury position and it filled at 4.45 percent because the market gapped down on CPI data. That 25 basis point miss turned a manageable loss into a significant one. Using limit orders or pre-set algorithmic exits instead of stops reduces that slippage but adds complexity. For most traders, keeping position sizes small enough that a 10 to 15 basis point slippage does not materially impact returns is the simpler solution.
The Mechanics of Pairing Both Markets
The core strategy most people overlook is using Treasuries as a volatility dampener rather than as a standalone investment. An equity portfolio that includes a 15 to 20 percent Treasury allocation tends to have lower maximum drawdowns during corrections, but the total return is also lower in bull markets. The tradeoff is real and it compounds over time. A 5 percent lower annual return over a decade is a very large difference in absolute terms. However, the psychological benefit of staying invested during a downturn often outweighs the mathematical cost because most retail investors abandon their strategy precisely when it is working. I have seen too many people sell equities at the bottom of a correction and then chase them back up at higher valuations because they could not tolerate the drawdown. The bond allocation prevents that behavioral mistake. When it comes to actual trade execution, timing matters more than direction. Entering a Treasury position right after a FOMC statement is usually a bad idea because the initial reaction is dominated by algorithmic trading and market makers adjusting their books. Waiting 30 to 60 minutes allows the price discovery to stabilize. Conversely, if you are trading equities, entering immediately after the bond market reacts to data can be profitable because the equity market often underreacts on the first pass. The bond market moves first and the equity market catches up over the next few hours. That lag is not reliable enough to build a strategy around, but it is useful for understanding flow dynamics. One specific limitation that deserves mentioning is the impact of the Federal Reserve as a market participant. The Fed holds roughly 25 percent of outstanding Treasuries and its balance sheet decisions directly affect supply and demand dynamics in ways that technical analysis cannot capture. When the Fed is doing quantitative tightening, it is effectively removing a major buyer from the market. That structural shift means bond yields will trend higher over time regardless of what the business cycle says. This is not a cyclical phenomenon. It is a regime change. Ignoring it while applying traditional bond market frameworks leads to systematic errors. The same applies to equities because higher structural yields compress valuation multiples across the board.
The practical takeaway is straightforward. Monitor the 10-year yield, the 2s10s curve, and the TIPS breakeven rate together. Watch how they move relative to each other, not in isolation. Use bond allocation as a portfolio stabilizer rather than a return enhancer. Size your positions to account for bond market slippage and settlement asymmetry. Avoid trading during the first 30 minutes after major economic data releases unless you have institutional-grade execution. And recognize that the correlation between bonds and stocks is not a fixed number. It changes depending on whether the dominant driver is inflation, growth, or risk sentiment. Getting that distinction right early in your process will save you from making the same mistakes I made for the first three years of running this desk.