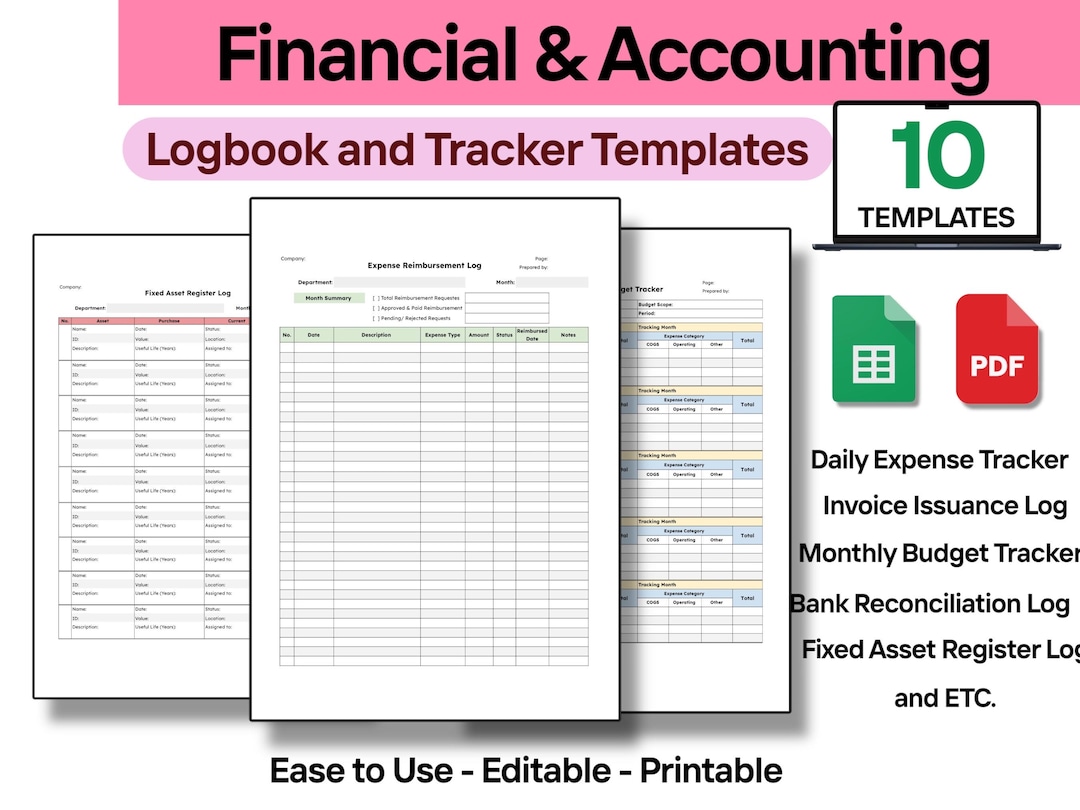
Most people thinking about a finance logbook are already overcomplicating it. A finance logbook is simply a structured record of your financial activity over time. The purpose is visibility. You track income, expenses, fees, and transactions so patterns become visible that would otherwise stay hidden in bank statements and spreadsheets nobody checks. The best ones are boring. The worst ones are elaborate systems you abandon after three weeks because they require too much maintenance.
I used a hand-built template for years. It tracked everything from mortgage interest deductions to rental property depreciation schedules. The problem wasn't the tracking. The problem was the format. When you're managing multiple accounts and trying to reconcile discrepancies between what your brokerage shows and what actually hit your bank, a poorly organized spreadsheet turns into a source of anxiety rather than clarity. That was the moment I started paying attention to structured logbook approaches that prioritized consistency over completeness.
Top 10 Finance Logbook
When people talk about the Top 10 Finance Logbook options, they usually mean different things. Some want simple expense trackers. Others need tools that handle tax classification automatically. A few need something that integrates with accounting software for business use. I looked at a lot of these. Here is what actually matters, based on experience rather than features listed on a website.
The ones worth considering share a few traits. They handle recurring entries without turning into maintenance nightmares. They allow custom categorization that maps to your actual life. They export data cleanly so you can move to another system if you decide this isn't working. And they don't require you to enter every single transaction manually unless you want to.
How to Set One Up Properly
Start with the categories, not the account connections. Most people begin by linking bank accounts and letting the software auto-import transactions. This looks efficient until you discover that the automatic categorization is wrong about forty percent of the time. You then spend more time correcting imports than you would have spent entering manually. Instead, define your categories first. Make them specific enough to be useful but broad enough that you won't need to create new ones every month.
I learned this the hard way with a client who tracked investment income separately from employment income but lumped all expenses into a single bucket called "living costs." After six months of data, the logbook showed exactly zero insight into where money was actually going. The fix was restructuring the expense categories into housing, transportation, insurance, debt service, food, entertainment, health, and miscellaneous. That took twenty minutes. The usefulness increased dramatically.
The next step is deciding on a reconciliation cadence. Daily reconciliation is ideal but unrealistic for most people. Weekly reconciliation catches issues before they compound. Monthly reconciliation means you will find problems that are already expensive. Pick weekly if you can manage it. If not, pick monthly and accept that some errors will go unnoticed longer.
For the actual tool, the choice comes down to complexity tolerance and use case. A simple Google Sheet works fine for personal budgeting with basic categories. Excel handles more complex scenarios with formulas and conditional formatting. Dedicated finance logbook software like QuickBooks, FreshBooks, or specialized personal finance tools offer more structure but introduce subscription costs and learning curves. I personally use a hybrid approach now. A spreadsheet for personal tracking and QuickBooks for anything involving business income or investment properties. The separation prevents cross-contamination and makes tax season significantly less painful.
Common Pitfalls That Waste Time
The biggest mistake I see is chasing perfection in the early stages. People spend weeks designing the perfect category structure, setting up rules, and building dashboards. By the time they finish the setup, they have three weeks of unentered data and already feel behind. Just start. Enter today. Add yesterday. Build the system around your actual behavior, not your ideal behavior.
Another common issue is maintaining too many accounts in the logbook when you really only need two or three for meaningful analysis. Tracking every coffee purchase across five different credit cards adds granularity that nobody uses in practice. Consolidate where it makes sense. Merge small accounts into broader categories. The goal is signal, not noise.
A third problem is treating the logbook as a historical archive rather than a living document. I once worked with someone who spent an hour every Sunday reviewing last week's entries for errors they identified after the fact. The result was burnout. The fix was a monthly review instead of a weekly deep dive. Weekly spot-checks are sufficient. Monthly reviews catch the real issues.
Edge Cases You Should Know About
Currency conversion is the first edge case. If you hold accounts in different currencies or make international purchases, your logbook needs to handle conversion rates consistently. Some tools do this automatically through API feeds. Others require manual entry with a fixed rate. The discrepancy between what your bank converted at and what you recorded can grow to surprising levels over a year. I keep a separate spreadsheet for currency conversions with the exact rate and date for every foreign transaction. It saves hours during tax preparation.
Cryptocurrency transactions represent another tricky area. Most standard logbooks treat crypto like regular currency, which is wrong. Crypto transactions involve cost basis tracking, capital gains calculations, and potential taxable events that a simple expense entry won't capture. If you hold crypto, use a specialized tracker like CoinTracker or Koinly alongside your main logbook. Don't try to force crypto into a system built for fiat.
Business expenses mixed with personal expenses is the third edge case. This is far more common than people admit. You run a side business from home, use a personal card for a work purchase, or have a rental property that shares utilities with your primary residence. I made this mistake with a rental property I managed for two years. The logbook couldn't distinguish between repairs that were deductible and improvements that needed to be capitalized. The workaround was creating a separate sub-account within the same spreadsheet specifically for that property, with clear labeling for every entry. It cost one afternoon to set up and saved me from a messy tax filing.
What to Look for When Choosing a Tool
Export capability should be non-negotiable. If the tool doesn't let you export to CSV or Excel, it is a trap. You will be locked in, and data migration later will be painful. Look for tools that offer open export formats.
Automated categorization is useful but not essential. Understand that no automated system is reliable enough to run on autopilot. Budget fifteen minutes a week for manual review regardless of how smart the categorization claims to be.
Mobile entry is important if you plan to update daily. A clunky mobile interface means you will stop using it. Test the mobile experience before committing.
Price matters, but consider it against the time you will spend maintaining the system. A thirty-dollar annual subscription that saves you two hours per month is cheaper than a free tool that becomes a burden you abandon.
I should note that no single logbook tool solves every problem. For simple personal budgeting, free tools like Google Sheets with a well-structured template will serve you well for years. For business use or complex investment tracking, paid tools justify their cost through time savings and error reduction. The key is matching the tool to your actual complexity level, not aspirational complexity.
The Top 10 Finance Logbook landscape has plenty of options. The right one depends on what you are tracking, how much maintenance you can sustain, and whether you need tax-ready outputs. Start simple. Iterate. Fix what breaks. That is the practical path rather than searching for a perfect system that doesn't exist.
Gallery Top 10 Finance Logbook
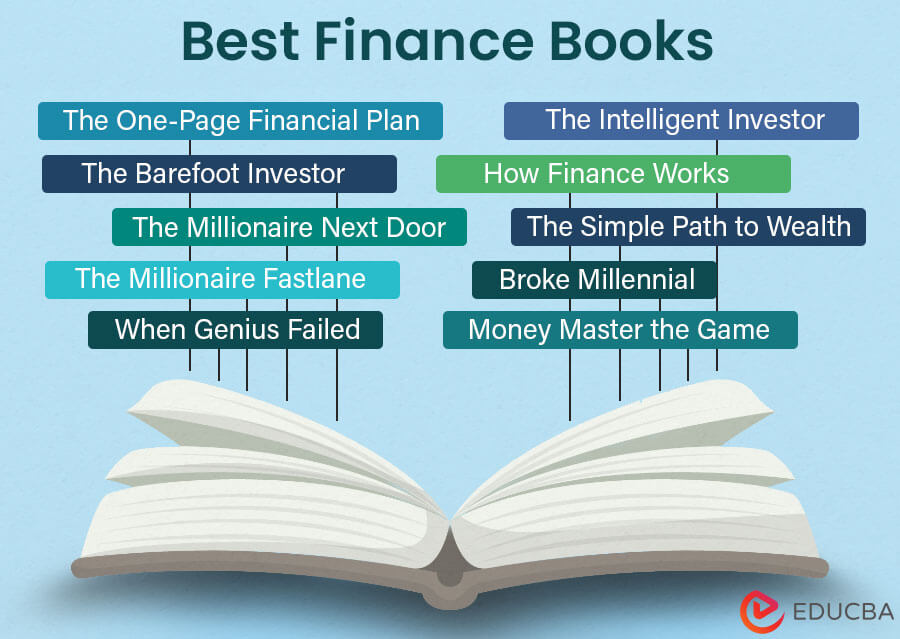
Top 10 Finance Books (Updated for 2023) | EDUCBA
Top 10 Finance Books to Read in 2025 by Bust-Down Books
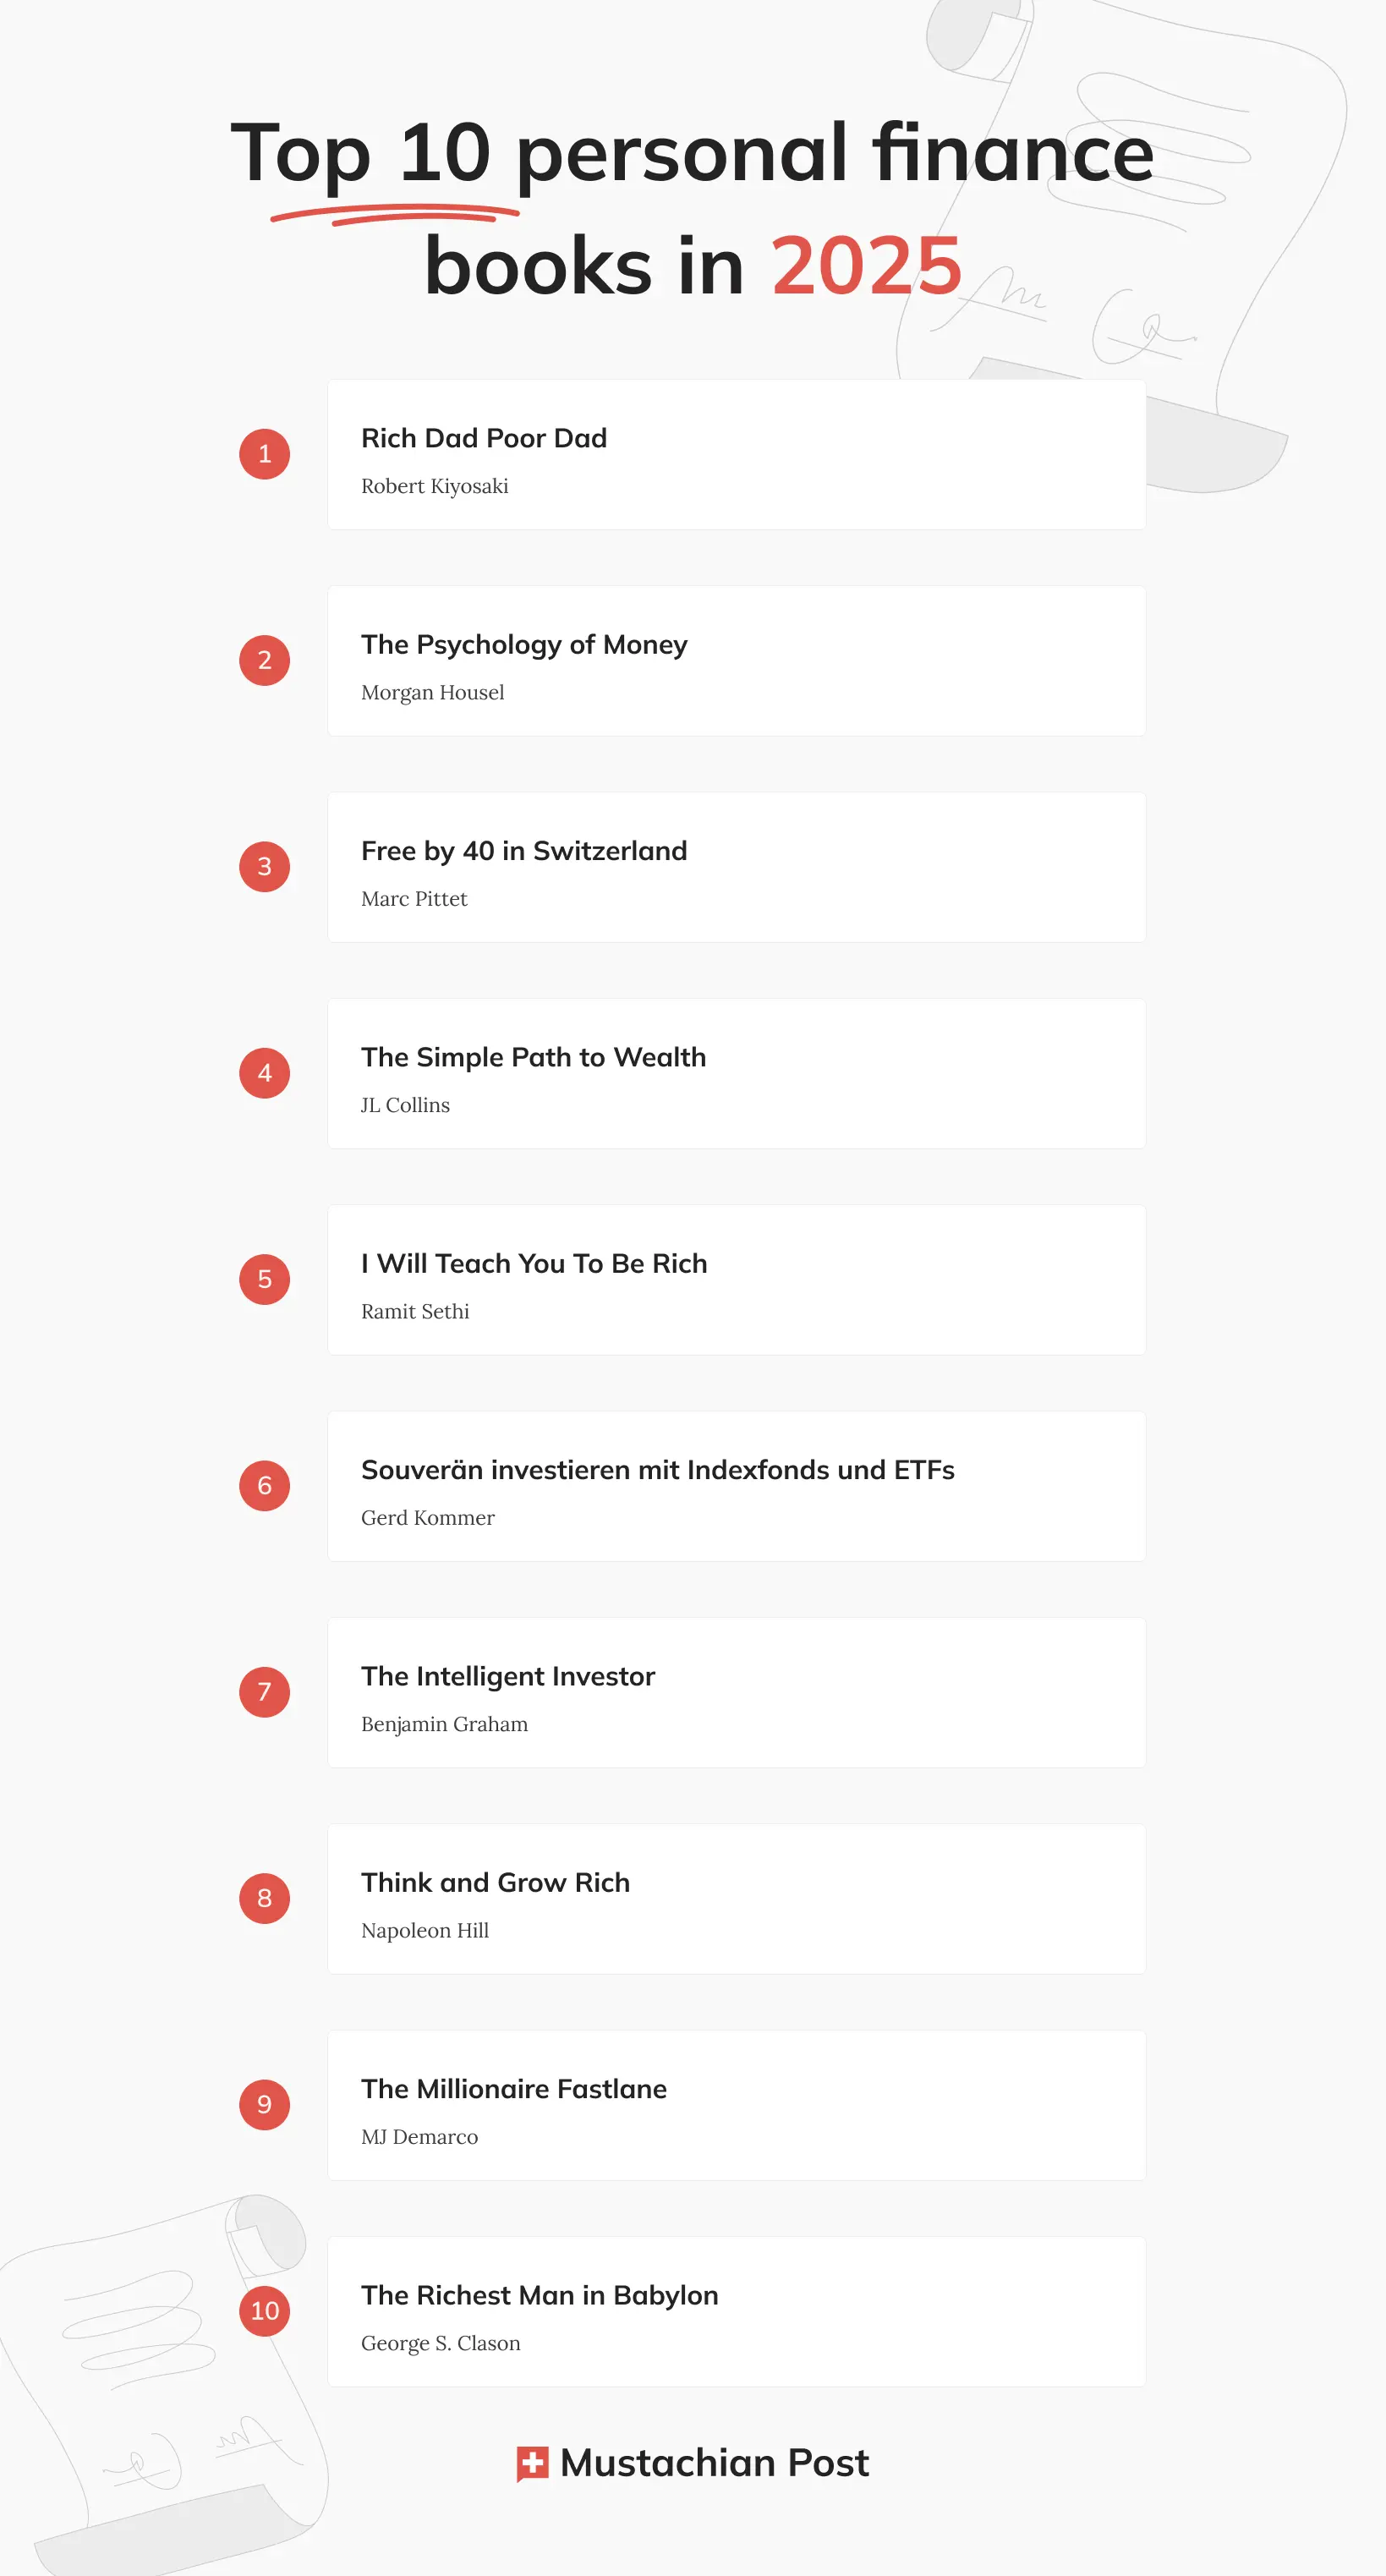
Top 10 personal finance books to read in 2026
Amazon.com: 10 Column Log Book: Customizable Ten Column Logbook | Large Multipurpose Log with 10 ...
Amazon.com: 10 Column Ledger Book: Large Accounting Ledger Logbook for Small Business, Personal ...