What They Actually Are and Why Most People Buy the Wrong Kind
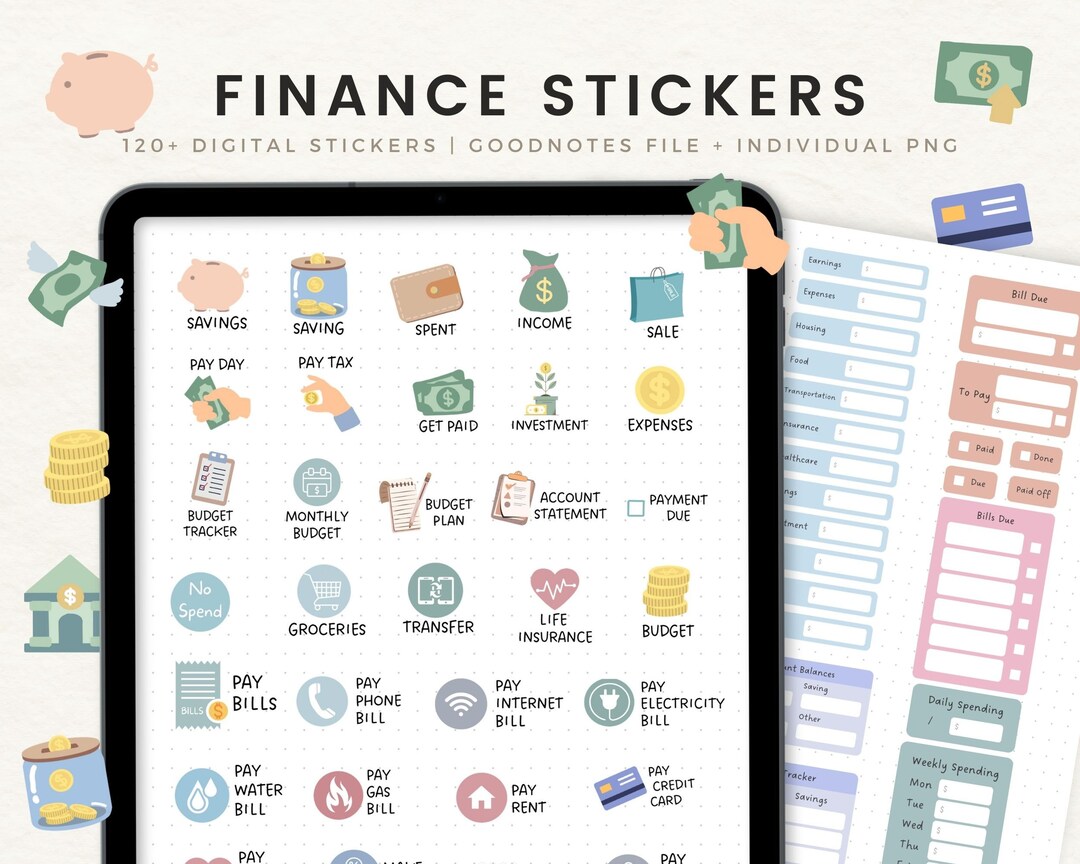
Finance journal stickers are small adhesive labels designed to organize budget categories, expense tracking, and savings goals in physical planners or bullet journals. The ones people actually recommend aren't the cheap Amazon bulk packs with 2,000 random icons. They're the specialized sets made by a handful of small businesses that print using professional-grade vinyl and matte finishes. The difference shows up within three months when you're actually using them daily. I've gone through probably six different sticker brands over the years. The ones that survive my planner end up being the ones with consistent sizing, decent adhesive that doesn't bubble after a month, and a legend system that actually matches up with the categories I track. Everything else becomes background noise that I stop noticing and eventually stop using.
Top Finance Journal Stickers — What I'd Actually Buy
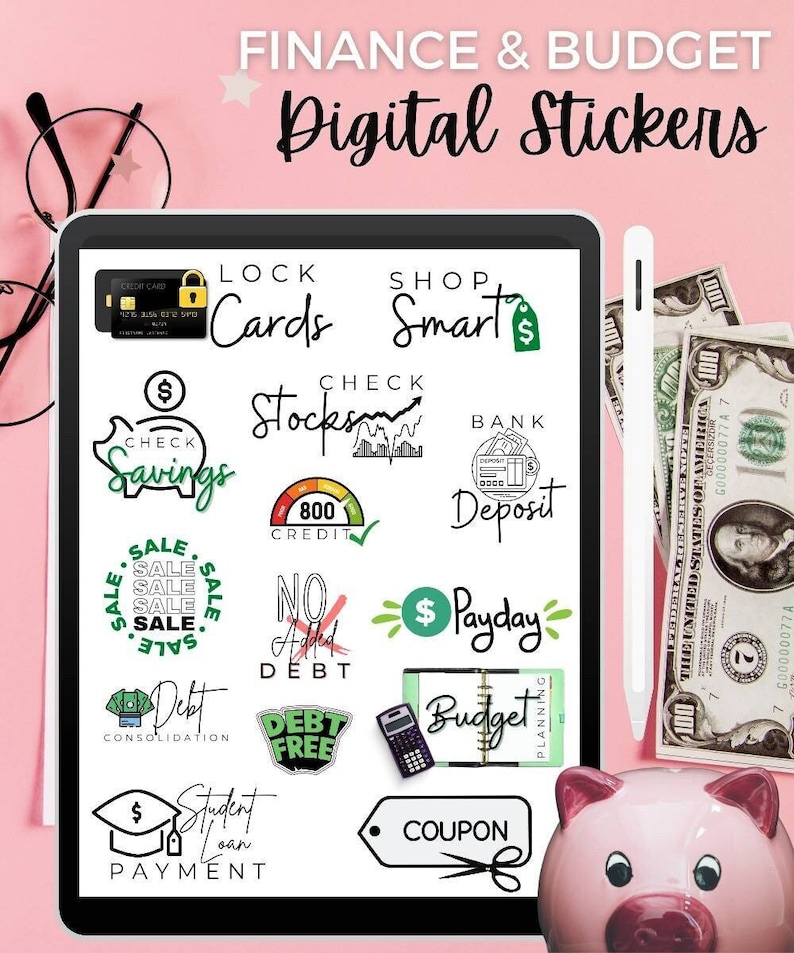
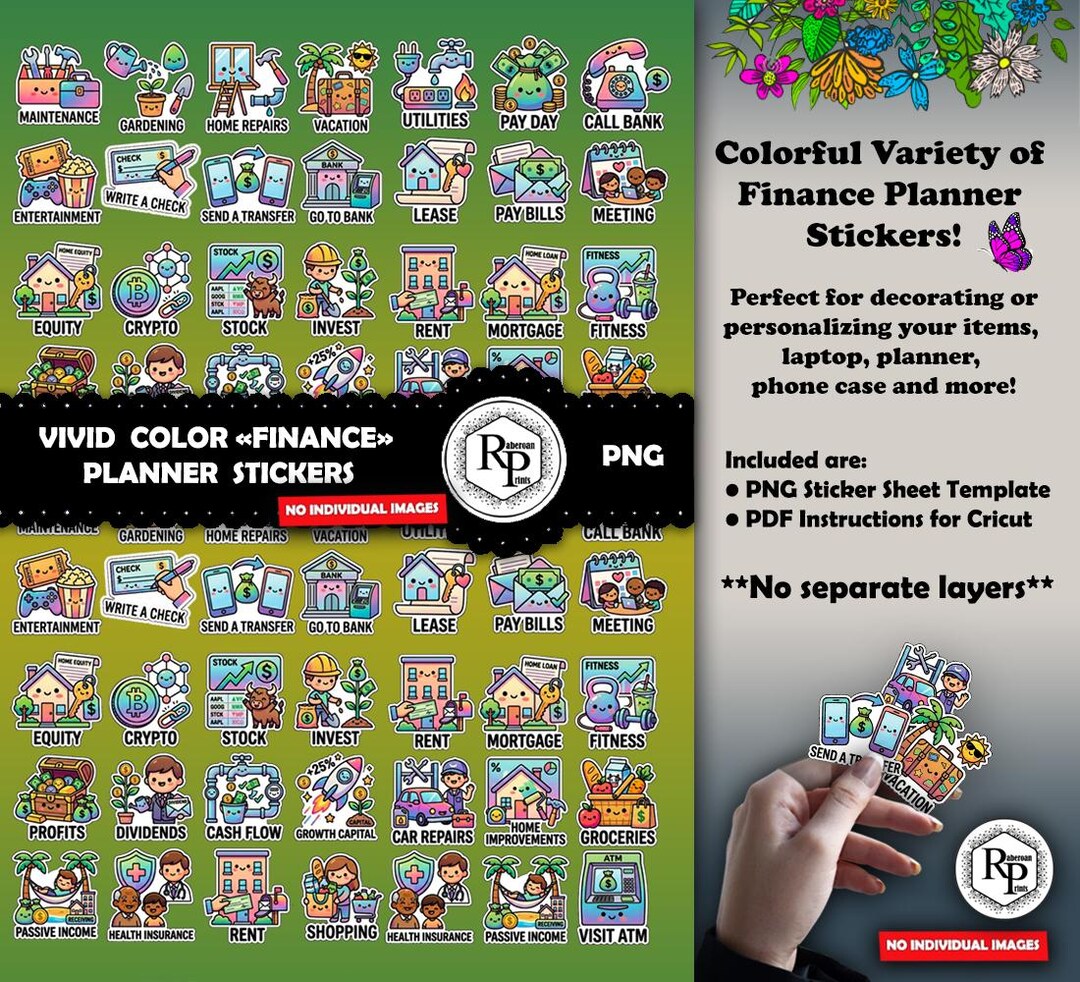
The term Top Finance Journal Stickers comes up a lot in the bullet journal community, usually tied to vendors on Etsy and a few independent shops. The problem is the phrase is used almost as a generic category label now, not a specific brand. Several sellers use it in their titles for search optimization. So when someone links to "Top Finance Journal Stickers," check who's actually printing them and whether the set includes a reference key. Without a key, you'll spend more time figuring out which sticker means "groceries" versus "dining out" than you'll save in tracking time. My current go-to is a set from a vendor I found through a friend of a friend. It runs about $18 for a sheet pack, comes in A5-compatible sizing, and includes a separate legend sheet. The adhesive is permanent but removable with care. That last part matters because I make mistakes when I'm entering transactions after the fact.
How to Set Up a System That Actually Sticks
Stickers alone won't organize your finances. The setup around them does. Here's how I do it, the way it's actually been working for me over the last eight months. Start by defining your categories. Not twenty categories. Five to eight, maximum. I track housing, utilities, groceries, dining, transportation, entertainment, and savings. Anything that doesn't fit gets routed into "miscellaneous" and I review that bucket at the end of every month. If miscellaneous grows past 15% of total spending for two months in a row, I add a sub-category. This keeps the sticker sheet clean and legible. Next, place the legend sheet in the front of your planner, not scattered across multiple pages. I put mine on the inside cover with a clear plastic sleeve. That way when I flip to any month, I know exactly where the key is. A misplaced legend is one of the most annoying things in finance tracking. You'll catch yourself staring at a sticker for thirty seconds trying to remember which color meant subscriptions versus streaming services.
Get the Full Details
Apply stickers at the point of entry, not at the end of the day. When I buy coffee and I'm out, I don't wait until I get home. I pull out the journal, stick the "dining" label, and move on. This habit has cut my evening data-entry time from roughly 20 minutes to under 5. The trade-off is you need your planner with you, which means keeping it in your bag or on your dashboard, not buried in a drawer somewhere.
Edge Cases and Workarounds I've Hit
Here's a problem I ran into that I didn't see coming. I travel about twice a month for work. Hotel and restaurant receipts get blurry when I photograph them for record-keeping. Sometimes the category itself is ambiguous — was that dinner client-related or personal? I ended up creating two temporary sticker variants: one with a small blue dot in the corner for client meals and one with a yellow dot for everything else. The dots came from a separate icon sticker pack I bought for three dollars. It cost almost nothing but it eliminated at least an hour of confusion every month when I was building my quarterly reports for taxes. Another edge case: multi-currency tracking. Early in my process, I tracked expenses in both USD and CAD because I cross the border regularly. The sticker sets are overwhelmingly English-only with US-centric icons. I solved this by adding a tiny currency symbol sticker next to the category label whenever I marked a non-USD transaction. It's manual, but it keeps the ledger accurate without needing a separate notebook.
What This Approach Doesn't Do Well
Let me be blunt about the downsides so you know what you're signing up for. Physical sticker-based tracking doesn't scale. If you have more than roughly twelve recurring expense categories, the sticker sheet gets too dense and you start misreading them. Digital spreadsheets or dedicated apps like YNAB or Monarch handle that volume cleanly. I switched to a hybrid approach — stickers for daily cash and small purchases, digital for everything else. Adhesive failure is real. Cheap sticker sets will lift at the edges after a few weeks, especially if your planner gets warm in the sun or you store it in a glove compartment. Once a sticker starts peeling, anything written over it smudges and the whole entry gets messy. I've replaced about one in every five sheets I've bought because of this.
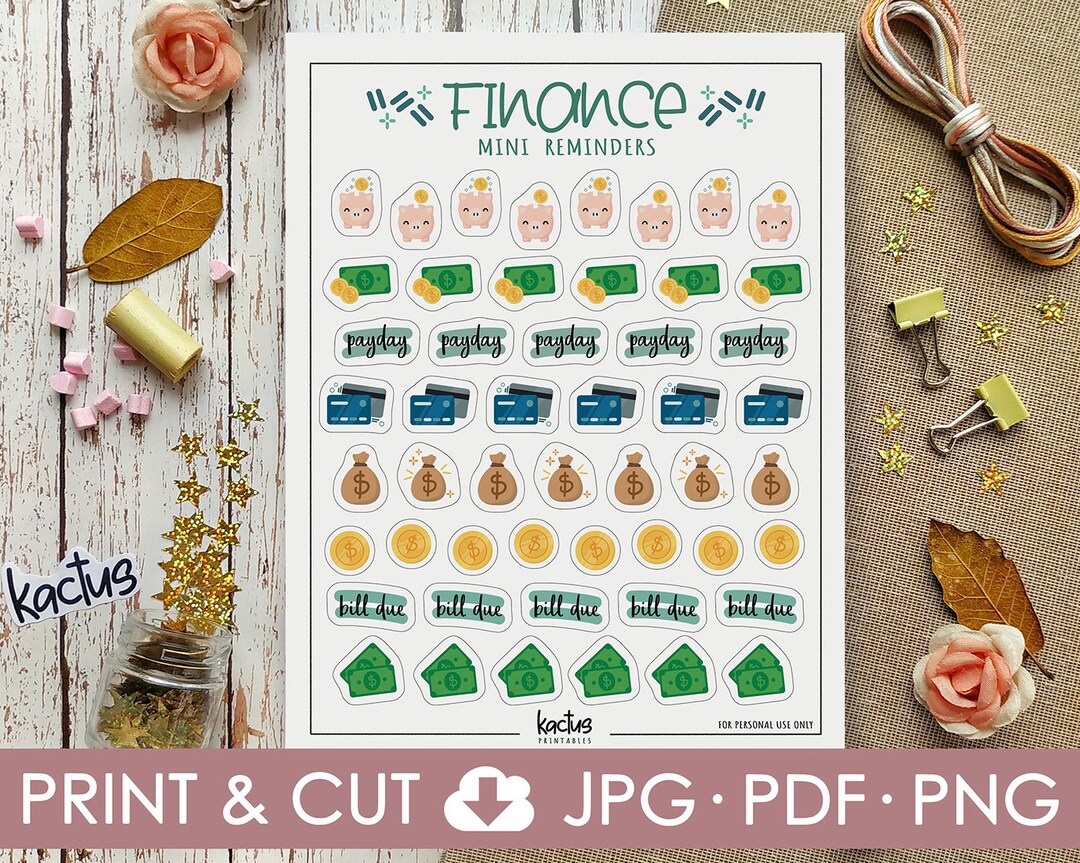
There's also the cost per unit issue. A typical set of finance journal stickers runs between 40 and 80 stickers per sheet, at $12 to $22. If you track daily, you'll go through a set in maybe six to eight weeks. That's roughly $20 to $35 per month on stickers alone. For comparison, a basic spreadsheet template costs nothing and updates in real time. The reason people stick with stickers isn't efficiency. It's the tactile reinforcement. Putting a physical label on a page makes spending feel more concrete than typing a number into an app. That psychological effect matters for behavioral change, even if it's not the most efficient method.
Alternatives Worth Considering
If you're just starting out and don't know whether you'll keep this up, don't buy stickers yet. Print a simple category grid on regular paper, cut it into labels with a paper trimmer, and run a two-week test. It takes about 15 minutes. If you still want it after that, invest in a proper set. I've watched way too many people drop $30 on stickers and then abandon the system within three weeks because the habit never formed. For people who already track consistently and want to level up, consider the combination of a dedicated finance tracker app synced to your bank accounts alongside a minimal sticker system for cash spending. The app handles the volume. The stickers handle the behavior. That's the setup I'm running now and it's the first time I've maintained a complete financial record for more than a year without burning out.