What Tradeline Building Actually Looks Like in Practice
You've probably seen the ads. They promise that if you load up your business profile with tradelines, you'll suddenly qualify for a $100,000 line of credit within 90 days. That's not how it works, and anyone telling you differently is selling something. I spent about three years working directly with commercial lenders after my first small business failed because I understood zero credit mechanics. By the time I figured it out, the information was already fragmented across different forums, half-accurate PDFs, and people who made money teaching this stuff without actually knowing it. Tradelines To Business Credit is the practice of adding credit accounts — trade references, vendor lines, and revolving accounts — to a business profile so that credit bureaus have data to calculate a risk score. It's not a secret strategy. It's basic credit-building, but most business owners start from zero because their business has no separate credit file in the first place. They're using personal credit cards and paying suppliers out of pocket, which means Dun & Bradstreet, Equifax Business, and Experian Business don't have anything to report on.
Getting Started With Tradelines To Business Credit
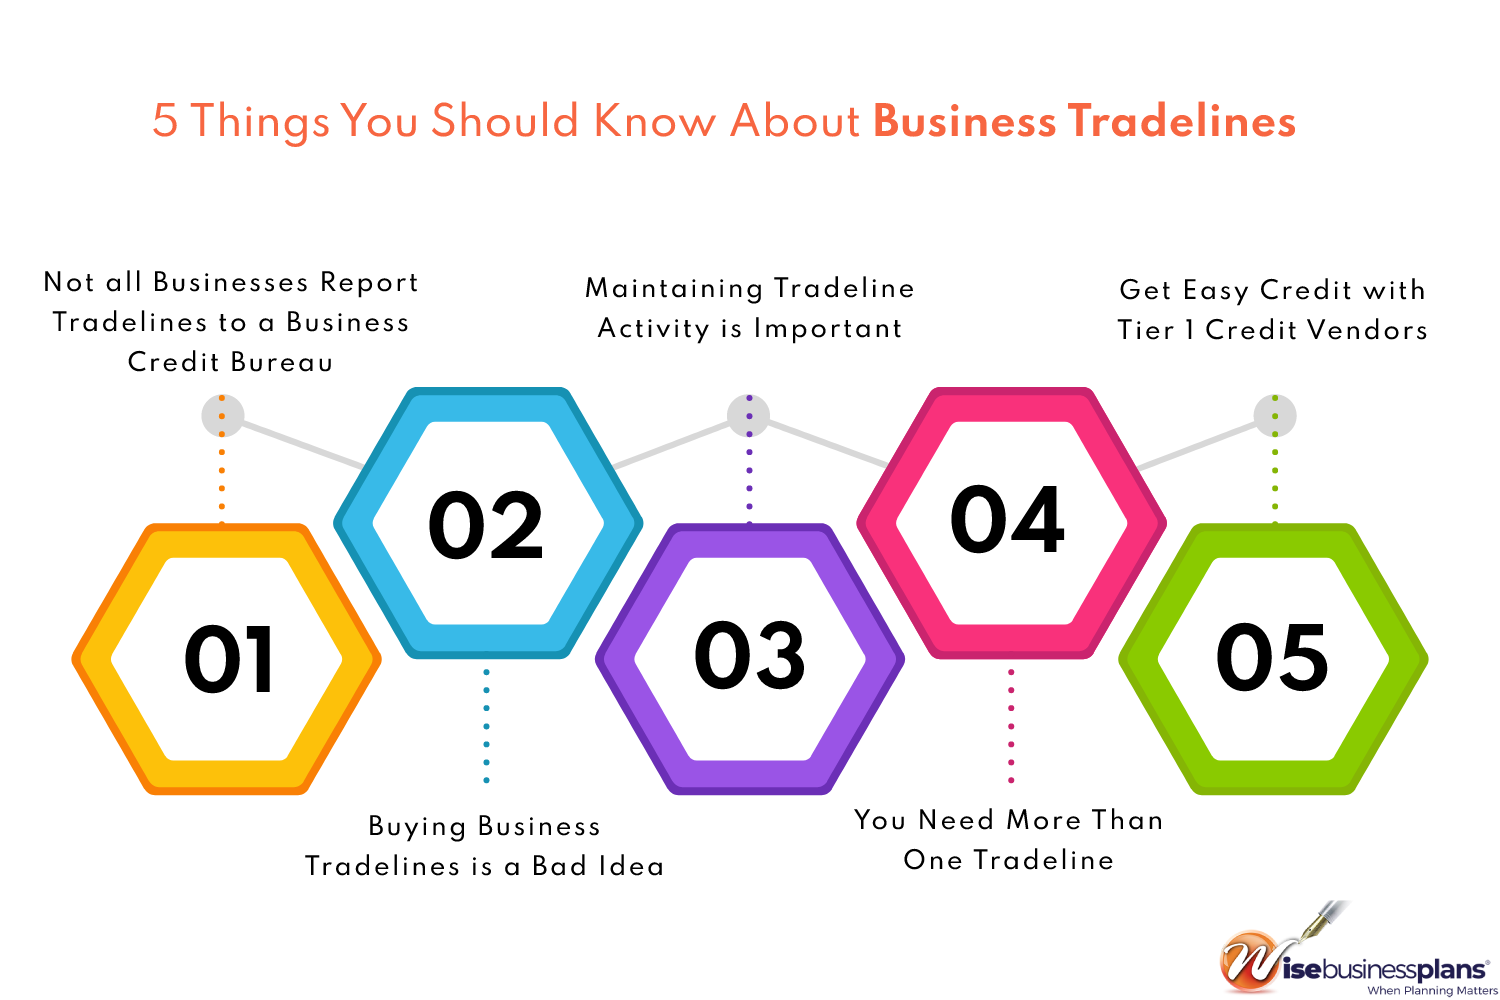
Step one is making sure your business actually exists as a separate legal entity. I can't stress this enough — if you're a sole proprietor and you've never filed for an EIN or registered an LLC, none of this will work. Credit bureaus need a D-U-N-S number from Dun & Bradstreet, and they cross-reference it against your legal business structure. A sole proprietorship without an EIN will bounce off every bureau. Get the EIN from IRS.gov first. Then apply for your D-U-N-S number, which is free and takes about 30 days to process unless you pay for expedited turnaround, which runs roughly $175 through D&B. Once you have both, you need to open accounts that report to business credit bureaus. Not every vendor does. Most small business checking accounts don't report. Your LLC formation documents don't report. You specifically need trade lines from vendors that report to at least one major business credit bureau. Net-30 accounts are the easiest starting point — these are vendor accounts where you buy supplies on credit and pay within 30 days. Companies like Uline, Grainger, and Quill offer these, but here's the part nobody tells you upfront: many of them now require a personal guarantee and a minimum credit check before approving your account. The ones that don't require a background check are harder to get into and often have lower credit limits. I ran into a specific problem with one vendor that took me about six months to solve. I was building out accounts through a major office supply vendor that reported to Dun & Bradstreet but not to Experian Business. After eight months of on-time payments, my D&B score had moved from 35 to 61, which is decent but not enough to unlock the bigger credit products. I needed Experian Business data too. The workaround was applying for a store card at a different retailer that reported to Experian Business specifically, then using that account alongside my existing trade lines to create a cross-bureau presence. You have to map out which bureaus each vendor reports to before you open accounts. There's a free spreadsheet some people in this space share, but I'd just build your own — it takes about ten minutes per vendor to verify reporting status by calling their business credit department directly.
Here's something counter-intuitive that most beginners miss: having more tradelines isn't always better. Lenders look at both the number of accounts and the utilization rate across those accounts. If you open ten Net-30 accounts and run 80% credit utilization on all of them, your scores will actually go down, not up. I learned this the hard way when a prospective lender pulled my business credit file and asked why I had eight accounts with balances close to their limits. My utilization was sitting around 72%. I paid down everything to under 30% within two weeks, waited 45 days for the updates to cycle, and then re-applied. The approval came through on the second attempt. Another thing people get wrong is the order in which they open accounts. You want to start with accounts that have lower reporting thresholds and build from there. Opening a high-limit revolving account too early can backfire because the hard inquiry hits your file and the new account drops your average account age. Start with two or three Net-30 accounts, pay them off in full every month before the due date, and let those reports pile up for 90 days. Then move to a secured business credit card or a vendor with a higher credit limit. The progression should feel slow at first, but that's how it works. I also want to be straightforward about what this approach cannot do. Tradeline building will not get you a $250,000 SBA loan in six months. It will not fix a personal credit score that's below 580 if the lender is doing a hybrid personal-business pull, which many small business lenders still do. It will not help if your business has an active tax lien or a judgment — those are public records and they sit on your business credit report regardless of how many trade lines you have. And it won't work if the vendor you're using doesn't actually report to a major business credit bureau. I've seen people open five accounts with vendors that only report to niche or secondary bureaus, then wonder why no one will lend to them. Verify the reporting before you open the account.
Get the Full Details
The realistic timeline for someone starting from zero is approximately six to twelve months to reach a D&B score in the 75 to 80 range and an Experian Business score that qualifies for standard vendor terms and some smaller credit products. The fastest I've ever seen it happen was around five months, and that person already had a personal credit score above 720, which some lenders factor in even for business accounts. If you have strong personal credit, you can sometimes offset weaker business credit during the initial application process, but that advantage fades as lenders shift toward pure business-file evaluations. The other thing worth noting is that not all tradelines carry equal weight. A revolving account with a $5,000 limit that you use and pay down monthly will move your score more than a Net-30 account with a $500 limit that you barely use. Lenders want to see that you can manage ongoing credit, not just pay an invoice on time once a month. Mix your tradeline types — include at least one revolving account alongside your trade references if you can qualify for one. That combination is what separates a thin file from a file that looks established. If you're doing this right, you're spending maybe 15 to 20 minutes per month managing your accounts and checking your credit reports. You should be pulling your D&B report quarterly at minimum and your Experian Business report every six months. Watch for errors. I've seen the same tradeline reported with two different payment histories on the same bureau file, which tanked a score by about 18 points until it was corrected. Disputes are handled through each bureau's website and usually resolve within 30 days, but you have to catch the errors yourself — no one is going to monitor your file for you.
For most people, this is the foundation. It's not glamorous, it moves slowly, and it requires actual discipline. But it's also the only method that lenders actually recognize. Everything else is noise.