Why Most Transfer Pricing Documentation Fails Its First Audit
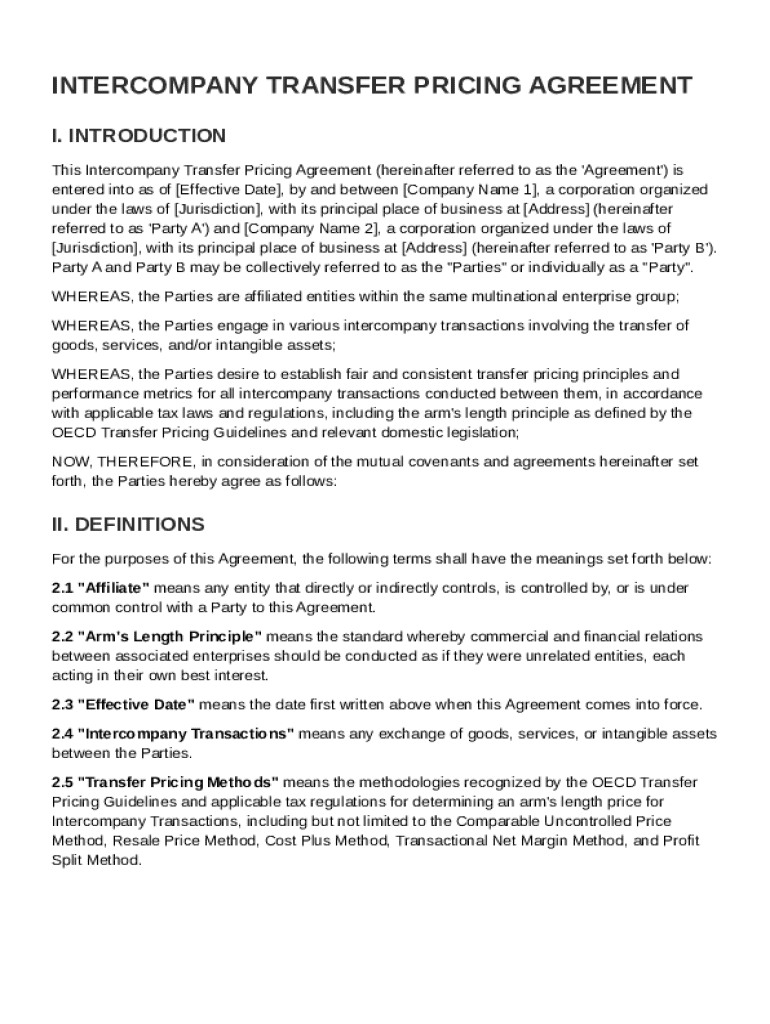
A transfer pricing agreement template is basically a structured framework that defines the terms between related parties for goods, services, or intangibles crossing borders. Most people treat it like a form to fill out. That's wrong. It's a legal and technical document that needs to survive a tax authority reading it cover to cover. I've seen companies spend three weeks on the wrong version because they grabbed a free template from a generic legal site and hoped for the best. The template you need depends entirely on your transaction type. Are you moving physical goods? Licensing intellectual property? Providing shared management services? Each category demands a different structure. A blanket template won't work because the OECD guidelines treat a cross-border service agreement fundamentally differently from a merchandise sale. You need to pick the right starting point first, then customize it for your actual economics. Here is what a proper template should cover at minimum: the party names and legal structures, the nature of the transaction, the pricing method you're applying, the contractual terms that support the economic substance, and the benchmarking analysis that backs up your arm's length margin. Leave any of these out and you have not got a transfer pricing agreement. You have got paperwork.
In practice, I use a version built around the TNMM method as my default starting point. It's the most common method globally and works for 80 percent of routine intercompany transactions. For the remaining 20 percent, I switch to CUP or profit split depending on the uniqueness of the intangibles involved. The template itself is usually a 15 to 20 page document once fully populated. It takes a competent person about four to six hours to draft a solid first version from scratch. A pre-built template cuts that down to maybe two hours of actual drafting time, but only if you know which sections to delete and which to keep.
How to Build One That Actually Holds Up
Start with the functional analysis. This is the step everyone skips. You need to document exactly what each party does, what assets they use, and what risks they bear. Not the org chart version. The real version. I spent two days once going back and forth with a client who claimed their Romanian subsidiary was a full-fledged manufacturer. The functional analysis showed it was actually just a packaging and labeling facility with zero risk-bearing capacity. The original template they were using assumed full manufacturing and would have produced a completely wrong benchmarking result. We rewrote the entire pricing section based on the real functions. After the functional analysis, select your transfer pricing method. This is where beginners make expensive mistakes. The OECD hierarchy says CUP is preferred, then methods like resale price, cost plus, TNMM, and profit split. In reality, CUP is rarely usable outside of commodity trades because truly comparable uncontrolled transactions are uncommon. TNMM is the workhorse. Profit split is for situations where both parties contribute unique intangibles. Pick the method based on data availability and comparability, not convenience. Next comes the benchmarking study. This is where most templates fall apart because the template provides no guidance on database selection, comparability factor weighting, or how to handle outliers. A proper benchmarking exercise using a tool like Orbit or Transfer Pricing Journals typically takes a trained analyst 8 to 12 hours per entity. It generates a range of acceptable margins. Your chosen method and the resulting intercompany price must fall inside that range.
Get the Full Details
The final piece is the contractual terms. Tax authorities increasingly ask whether the contract matches the actual conduct. I had a case last year where a German company's template-based agreement specified a 4 percent markup on cost plus, but their actual invoicing practices showed they were effectively charging a fixed fee per unit. The contract and the conduct diverged enough that the Finanzamt challenged the entire pricing structure. We resolved it by amending the internal documentation to reflect the actual behavior and adjusting the intercompany pricing to match, but the audit delay cost them roughly 11 months and about 40 thousand euros in advisory fees alone.
What Nobody Tells You About Templates
A template is a starting point, not a finished product. The biggest mistake I see is companies treating a downloaded template as sufficient compliance. It isn't. Tax authorities in the EU, Asia, and increasingly in Latin America expect contemporaneous documentation prepared before the filing deadline. A static template from 2019 that you update by changing the company name does not meet that standard. Another hidden issue is local country requirements. Germany requires a full master file and local file under BEPS Action 13. Brazil has its own specific documentation rules through Receita Federal that don't align well with OECD templates. China's SAT has particular expectations around service agreements and royalty payments that a generic template will miss. If your template doesn't account for local filing variations, you're creating work for yourself during the audit phase instead of preventing it. There is also the issue of consistency across jurisdictions. If your US parent files one version of the intercompany agreement and your German subsidiary's tax return references a materially different version, you have created a red flag that no template can hide. The numbers need to tie. The contractual terms need to align. The functional analysis needs to be consistent across all member entities. I track this with a simple matrix mapping each jurisdiction's filing against the master documentation, which usually takes about 30 minutes to set up but saves days of explanation later.
When a Template Is the Wrong Tool
Sometimes the transaction is too unique for any template. I worked with a renewable energy company that had a complex power purchase arrangement between a Swiss holding and a Polish generator. The pricing involved electricity spot market references, currency hedging components, and capacity payment adjustments. No standard template could capture the commercial reality. In that case, we built the documentation from the ground up, using the contractual terms and commercial invoices as the primary reference rather than trying to force the arrangement into a cost plus or TNMM framework. The process took about three weeks instead of three days, but it was the only way to make the documentation defensible. Templates also fail when the economic substance changes significantly year over year. If your intercompany service fees jumped from 2 million to 18 million between fiscal years because the scope of services expanded, a recycled template with updated numbers will raise eyebrows. The tax authority will want to know why the margin structure changed, whether the benchmarking still holds, and whether the original transfer pricing policy was followed. You need to document the change separately and update the benchmarking study, not just tweak the template. If you need a working starting point, the basic structure is straightforward: cover page with party identification, functional analysis section, transfer pricing method justification, benchmarking results, contractual terms, and supporting financial data. Most professional firms build their own template internally and update it annually as regulations shift. Building your own takes time but it pays off because it matches your actual operations instead of the other way around. The cost of building a proper in-house template is roughly equivalent to one hour of senior consultant time per section, so expect 8 to 15 hours total for a complete version that covers master file and local file requirements for a mid-size multinational.