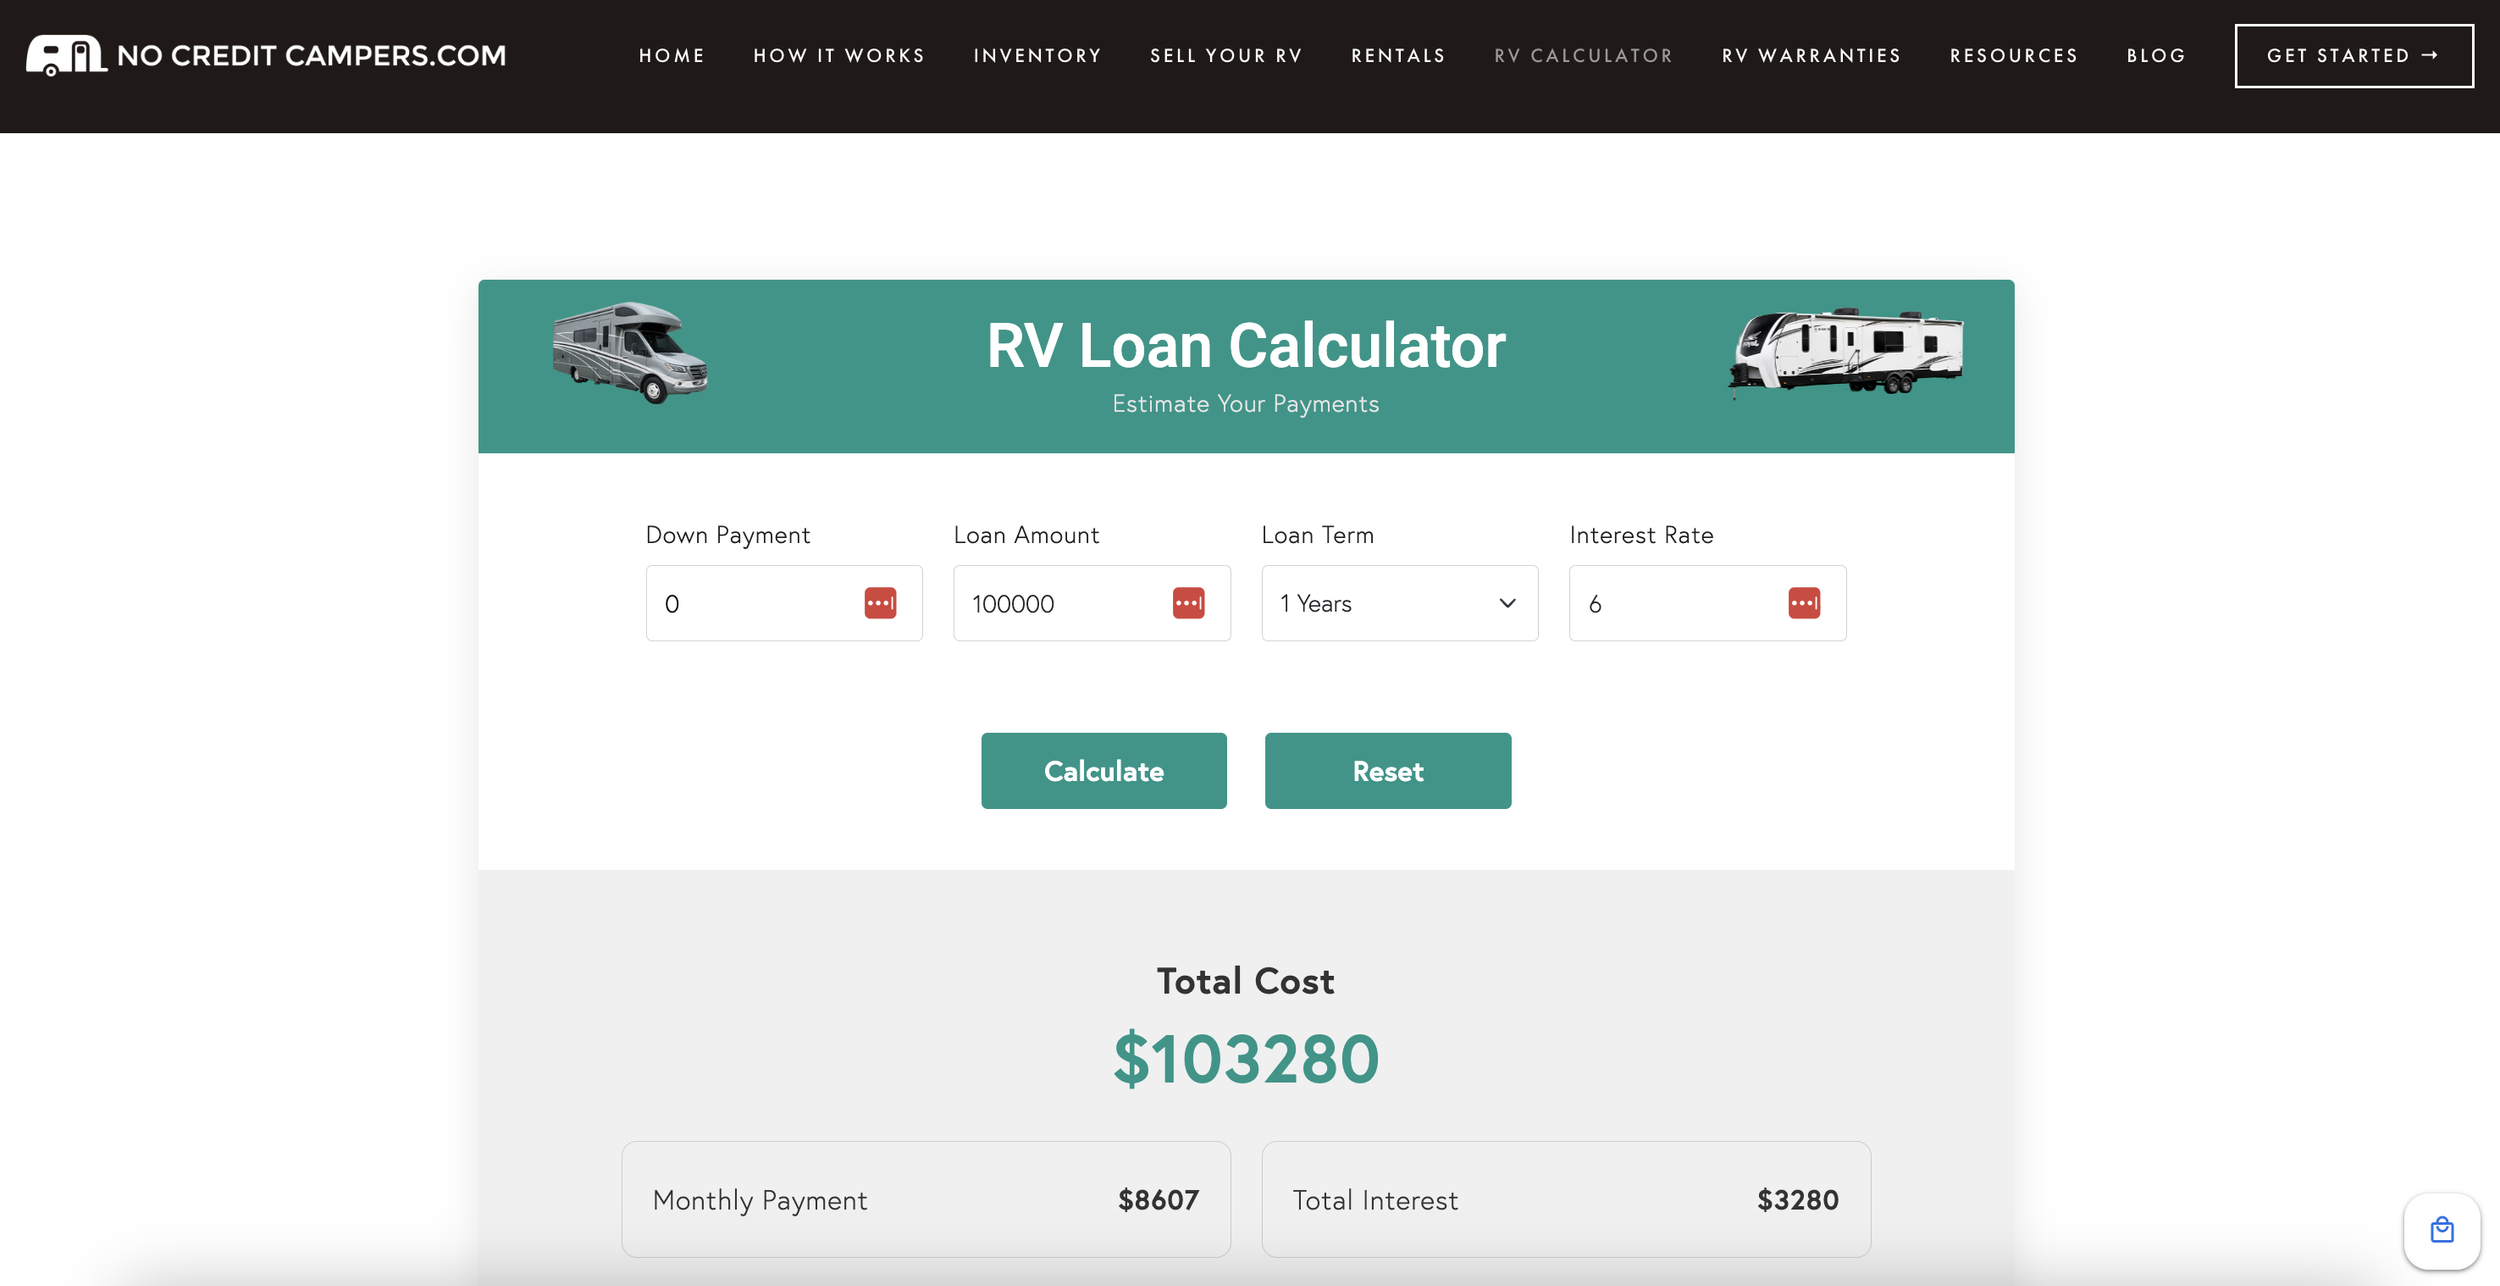
Getting a travel trailer financed doesn't have to be a guessing game
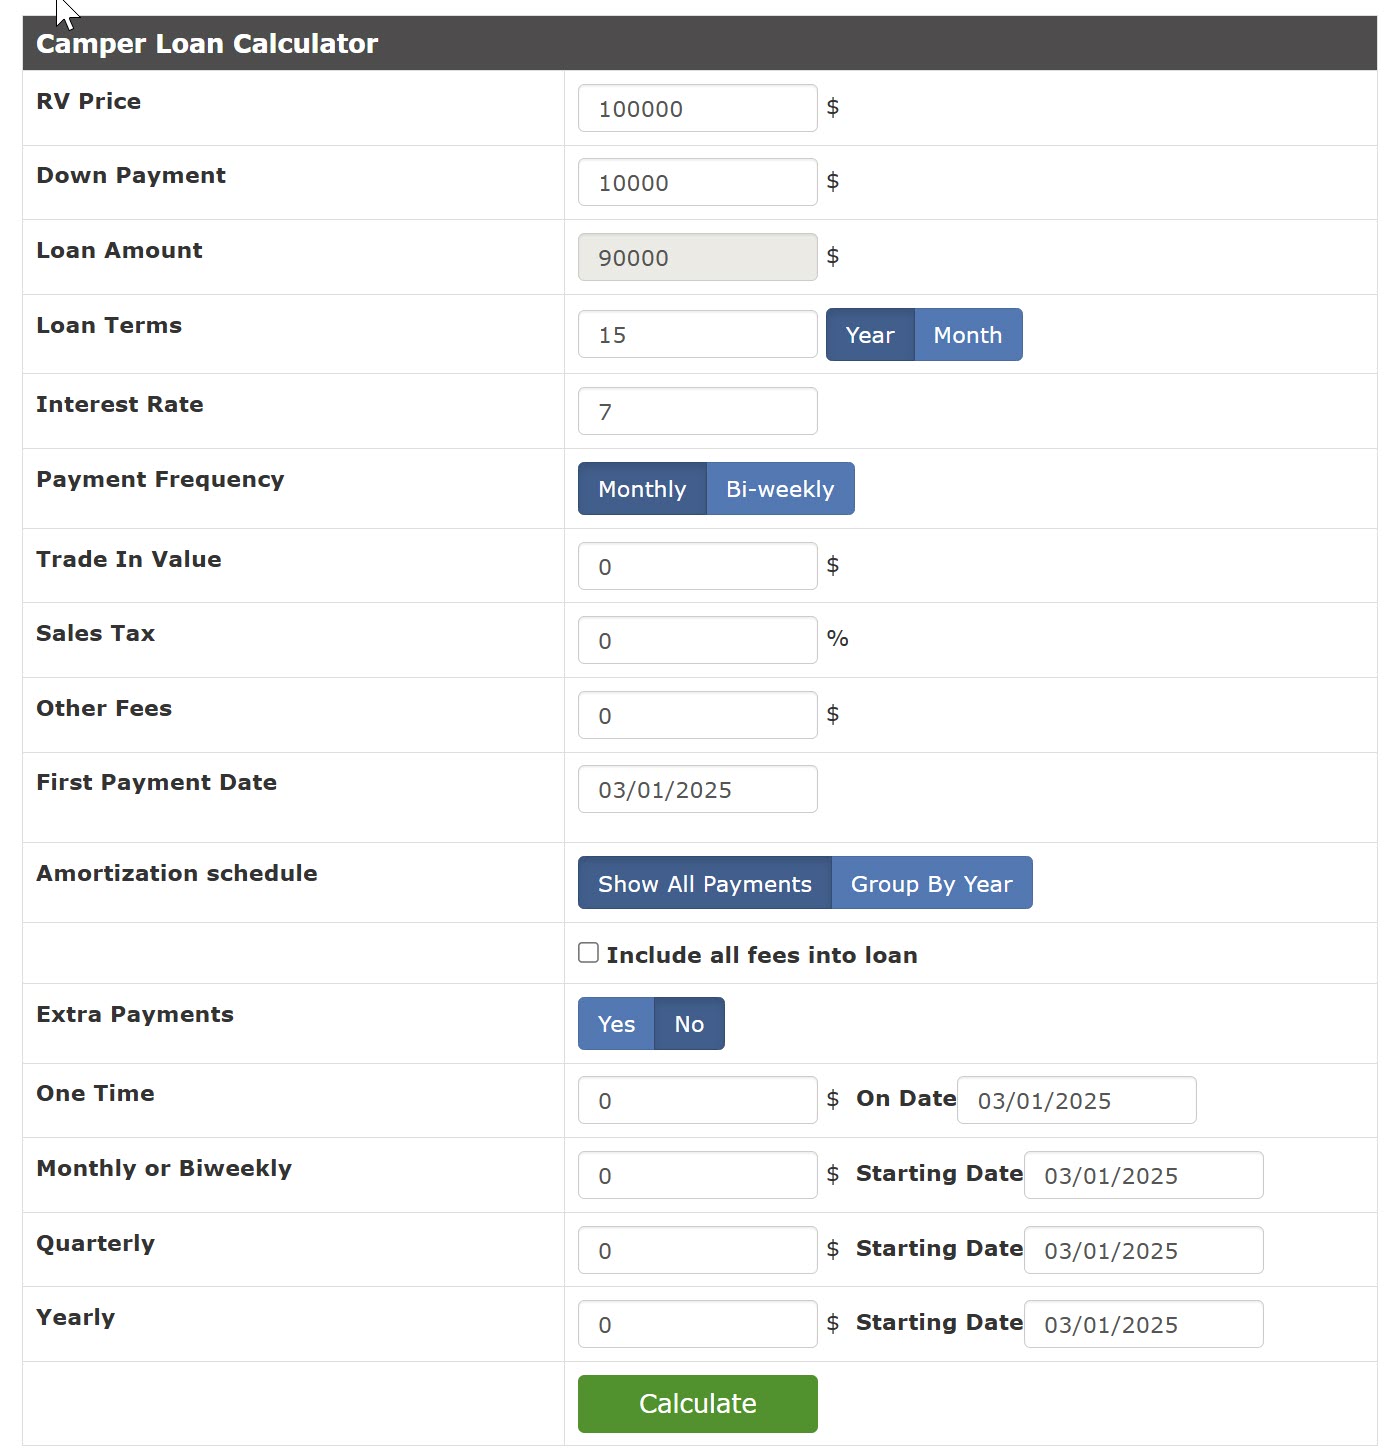
You pull up to the lot, you've got your credit score, you know roughly what you can afford, but then the dealer hands you a stack of paperwork and suddenly you're trying to reconcile monthly payments against a balloon payment, a residual value, and some arcane fee schedule. I've been through this more times than I care to count, and the basic tool that saved me from overpaying repeatedly is straightforward enough that you can build it yourself. At its core, a Travel Trailer Financing Calculator takes four inputs and spits out a monthly payment, an total interest cost, and an amortization schedule. The four inputs are the purchase price, the down payment (as either a dollar amount or percentage), the annual interest rate, and the loan term in months. That's it. The math behind it is the standard amortization formula used by every bank and credit union in the country. The formula itself looks like this:
M = P × r × (1 + r)^n divided by ((1 + r)^n - 1) Where M is your monthly payment, P is the principal (purchase price minus down payment), r is your monthly interest rate (annual rate divided by 12), and n is the total number of monthly payments. It's not complicated. What's tricky is getting the right numbers plugged in, because travel trailer loans have quirks that car loans don't. Here's a concrete example. You're looking at a 28-foot fifth wheel with a sticker price of $42,000. You put 15% down, which is $6,300, leaving a principal of $35,700. The dealer quotes you 7.49% APR for 72 months. Your monthly rate is 0.0749 divided by 12, which equals 0.00624. Plug those into the formula and your monthly payment comes out to about $547. Total interest paid over the life of the loan is roughly $3,984. A basic calculator will give you those numbers in about five seconds. Getting them wrong costs you real money, which is why building your own is worth the fifteen minutes it takes.
Building your own calculator in a spreadsheet
I use a simple Google Sheet. Column A is the label, Column B is where you type the inputs. Row 1 is purchase price, row 2 is down payment, row 3 is annual interest rate, row 4 is loan term in months. Row 6 is your monthly payment, row 7 is total interest, row 8 is total cost. The formula in row 6 uses the PMT function, which handles the math for you. The formula in row 7 multiplies your monthly payment by the loan term and subtracts the principal. Row 8 adds the down payment to the total cost. The PMT function in Google Sheets looks like this: =PMT(B3/12, B4, -(B1-B2)). The negative sign on the principal is important because PMT returns a negative number by default when the present value is positive. Without flipping the sign you'll get a payment that looks like it's coming back to you instead of going out. Once you have the basic sheet set up, you can add a couple more rows for things that dealers love to hide in the fine print. Sales tax is usually calculated on the full purchase price before your down payment, so you need to add tax to the principal before running the PMT calculation. Documentation fees, dealer prep charges, and extended warranty packages often get rolled into the loan, which inflates your principal without you realizing it. I track these separately in the sheet so I can see the difference between the advertised price and the actual financed amount.
Get the Full Details

When a Travel Trailer Financing Calculator falls short
The standard amortization model assumes a fixed interest rate for the entire term. That works fine for most conventional loans, but travel trailer financing frequently comes as a hire-purchase agreement or a lease-purchase hybrid, especially through RV-specific lenders. In those cases, there's a balloon payment at the end equal to a percentage of the original value, usually 20 to 30 percent. The monthly payment your calculator shows will be lower than what you actually owe each month if the balloon isn't factored in, and the total cost will be significantly higher because you're paying interest on the full amount throughout the term even though you never actually finance the balloon portion in the same way. I ran into this exact problem last year when a lender quoted me a monthly payment that seemed absurdly low for the amount I was borrowing. The calculator I'd been using for years showed a payment that was about $120 higher than what they were offering. It took me twenty minutes of pushing back before they admitted the loan had a 25% residual value at term end. The monthly payment was calculable, but the total cost was much worse than a standard installment loan would be. The workaround was simple: I asked for the full amortization schedule including the balloon, ran those numbers through a modified calculator that included the balloon payment as a separate line item, and compared the total cash outflow against a conventional loan from a credit union. The credit union quote ended up being $3,200 cheaper over the life of the loan. Another edge case that trips people up is prepayment penalties. Some RV loans have a clause that charges a percentage of the remaining balance if you pay off the loan early within the first two or three years. A standard calculator won't show this, and it can cost you hundreds if you're planning to refinance or sell the trailer quickly. I always check the loan agreement for this before signing, and I factor it into my sheet as a separate row so it shows up in the total cost calculation.
What the numbers actually tell you
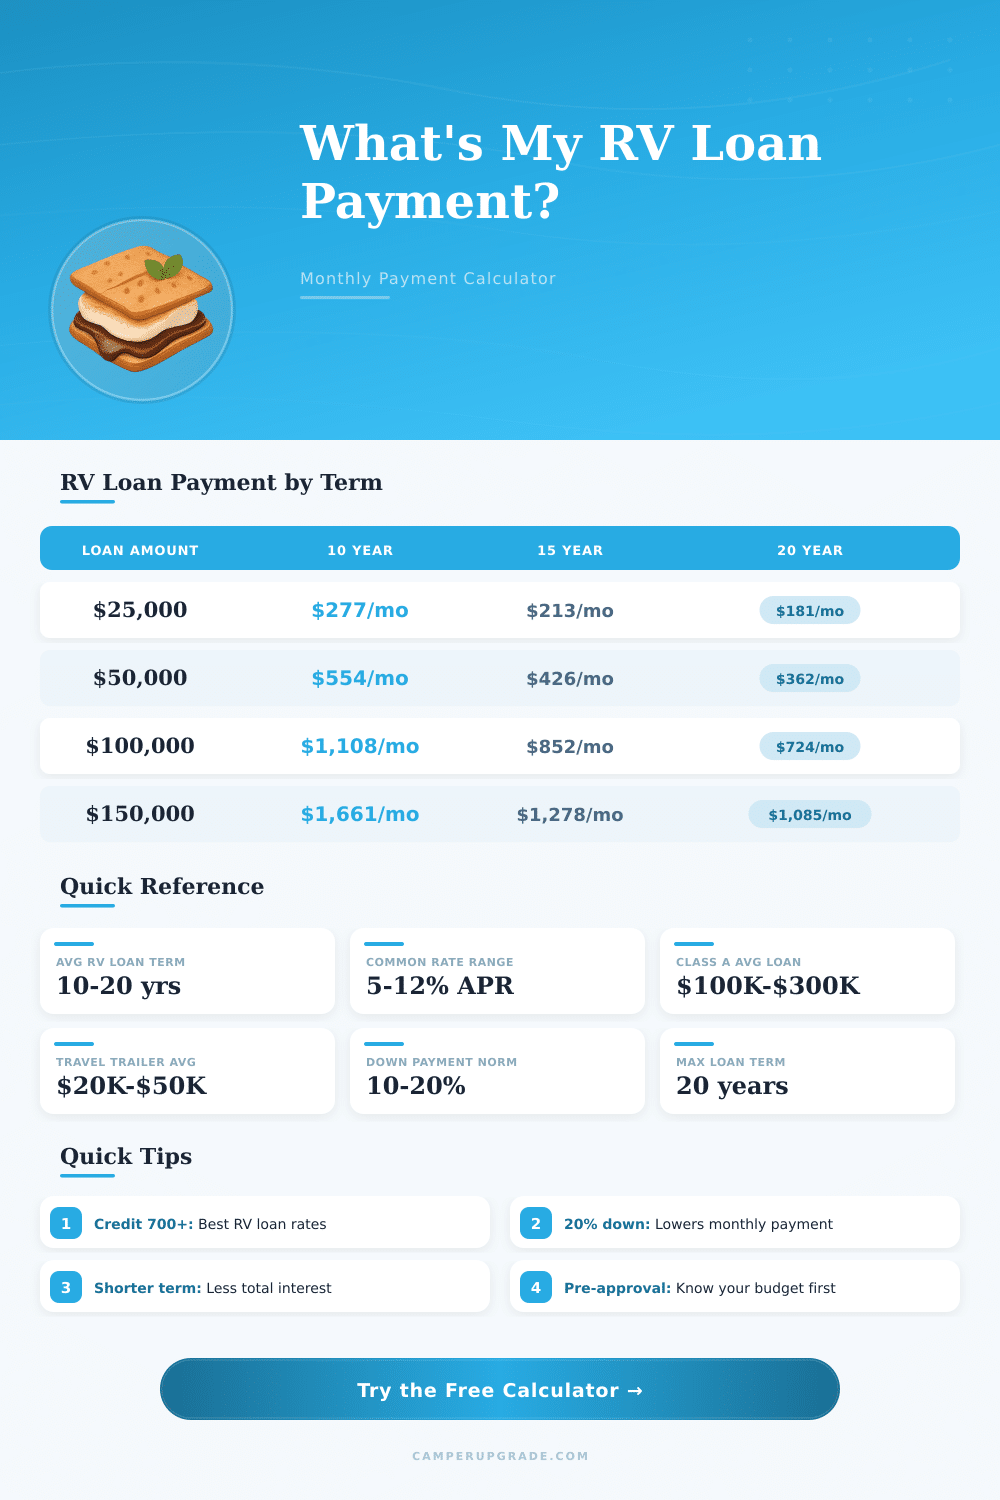
The monthly payment gets all the attention, but it's the total interest cost and the total amount paid that determine whether a loan is actually reasonable. A $400 monthly payment sounds manageable until you realize you're paying $8,400 in interest over five years on a $30,000 loan. That's a 28 percent markup on the principal, which is on the high end for travel trailer financing in the current market. Interest rates for RV loans vary widely depending on credit score, loan term, and whether the trailer is new or used. New travel trailers typically qualify for rates in the 6 to 9 percent range for borrowers with good credit. Used trailers, especially those over ten years old, can push into the 10 to 13 percent range because lenders view them as higher risk. Credit unions generally offer the best rates, but their loan limits and term lengths can be more restrictive than private lenders. If you're running the numbers and the total interest comes to more than 20 percent of the purchase price, you should reconsider your options before signing. That usually means either a longer loan term, a higher interest rate, or both. A 72-month loan at 8 percent on a $35,000 principal will cost you about $5,600 in interest. A 60-month loan at the same rate costs about $4,700. The extra $150 per month for the shorter term saves you nearly a thousand dollars. Most people focus on the lower payment and miss that tradeoff entirely.
The other thing people overlook is the impact of a larger down payment. Dropping from 10 percent down to 20 percent doesn't just cut the principal in half, it can also move you into a better interest rate tier. Lenders often reserve their best rates for loans-to-value ratios below 80 percent, so that extra 10 percent down payment might knock a full percentage point off your rate. On a $35,000 loan at 7 percent for 60 months versus 8 percent, the difference is about $55 per month, or $330 over the life of the loan. It's not dramatic, but it adds up when you factor in the reduced principal as well. You don't need a fancy app or a subscription service to do this math. A spreadsheet, the PMT function, and about twenty minutes of honest input will give you numbers you can take into any dealership and use to negotiate from a position of actual knowledge rather than hope.