How to Actually Use a Travel Trailer Loan Calculator Without Getting It Wrong
Most people treat a travel trailer loan calculator like it's a simple math problem. It isn't. The inputs matter more than you think, and getting them wrong will cost you money at closing, not during the calculation. I spent three years working loan estimates for recreational vehicles before moving into underwriting. I've watched good calculators produce garbage because someone typed in the wrong term or ignored the gap between the trailer's asking price and what the lender will actually appraise it for. The tool itself is fine. Your data entry is where things fall apart.
What a Travel Trailer Loan Calculator Actually Does
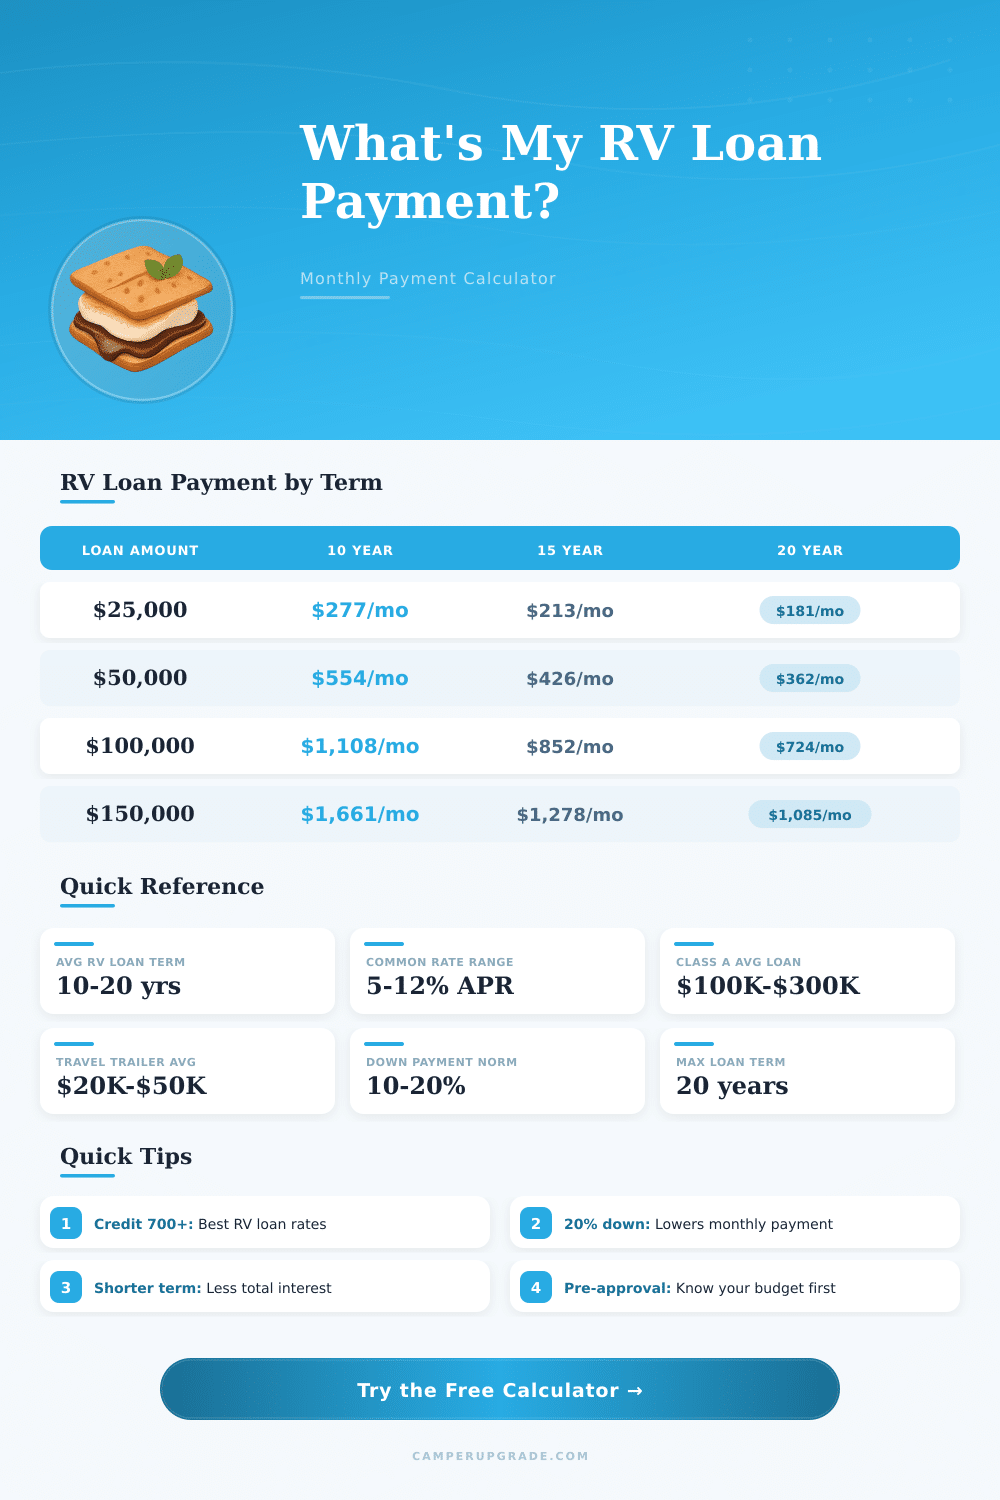
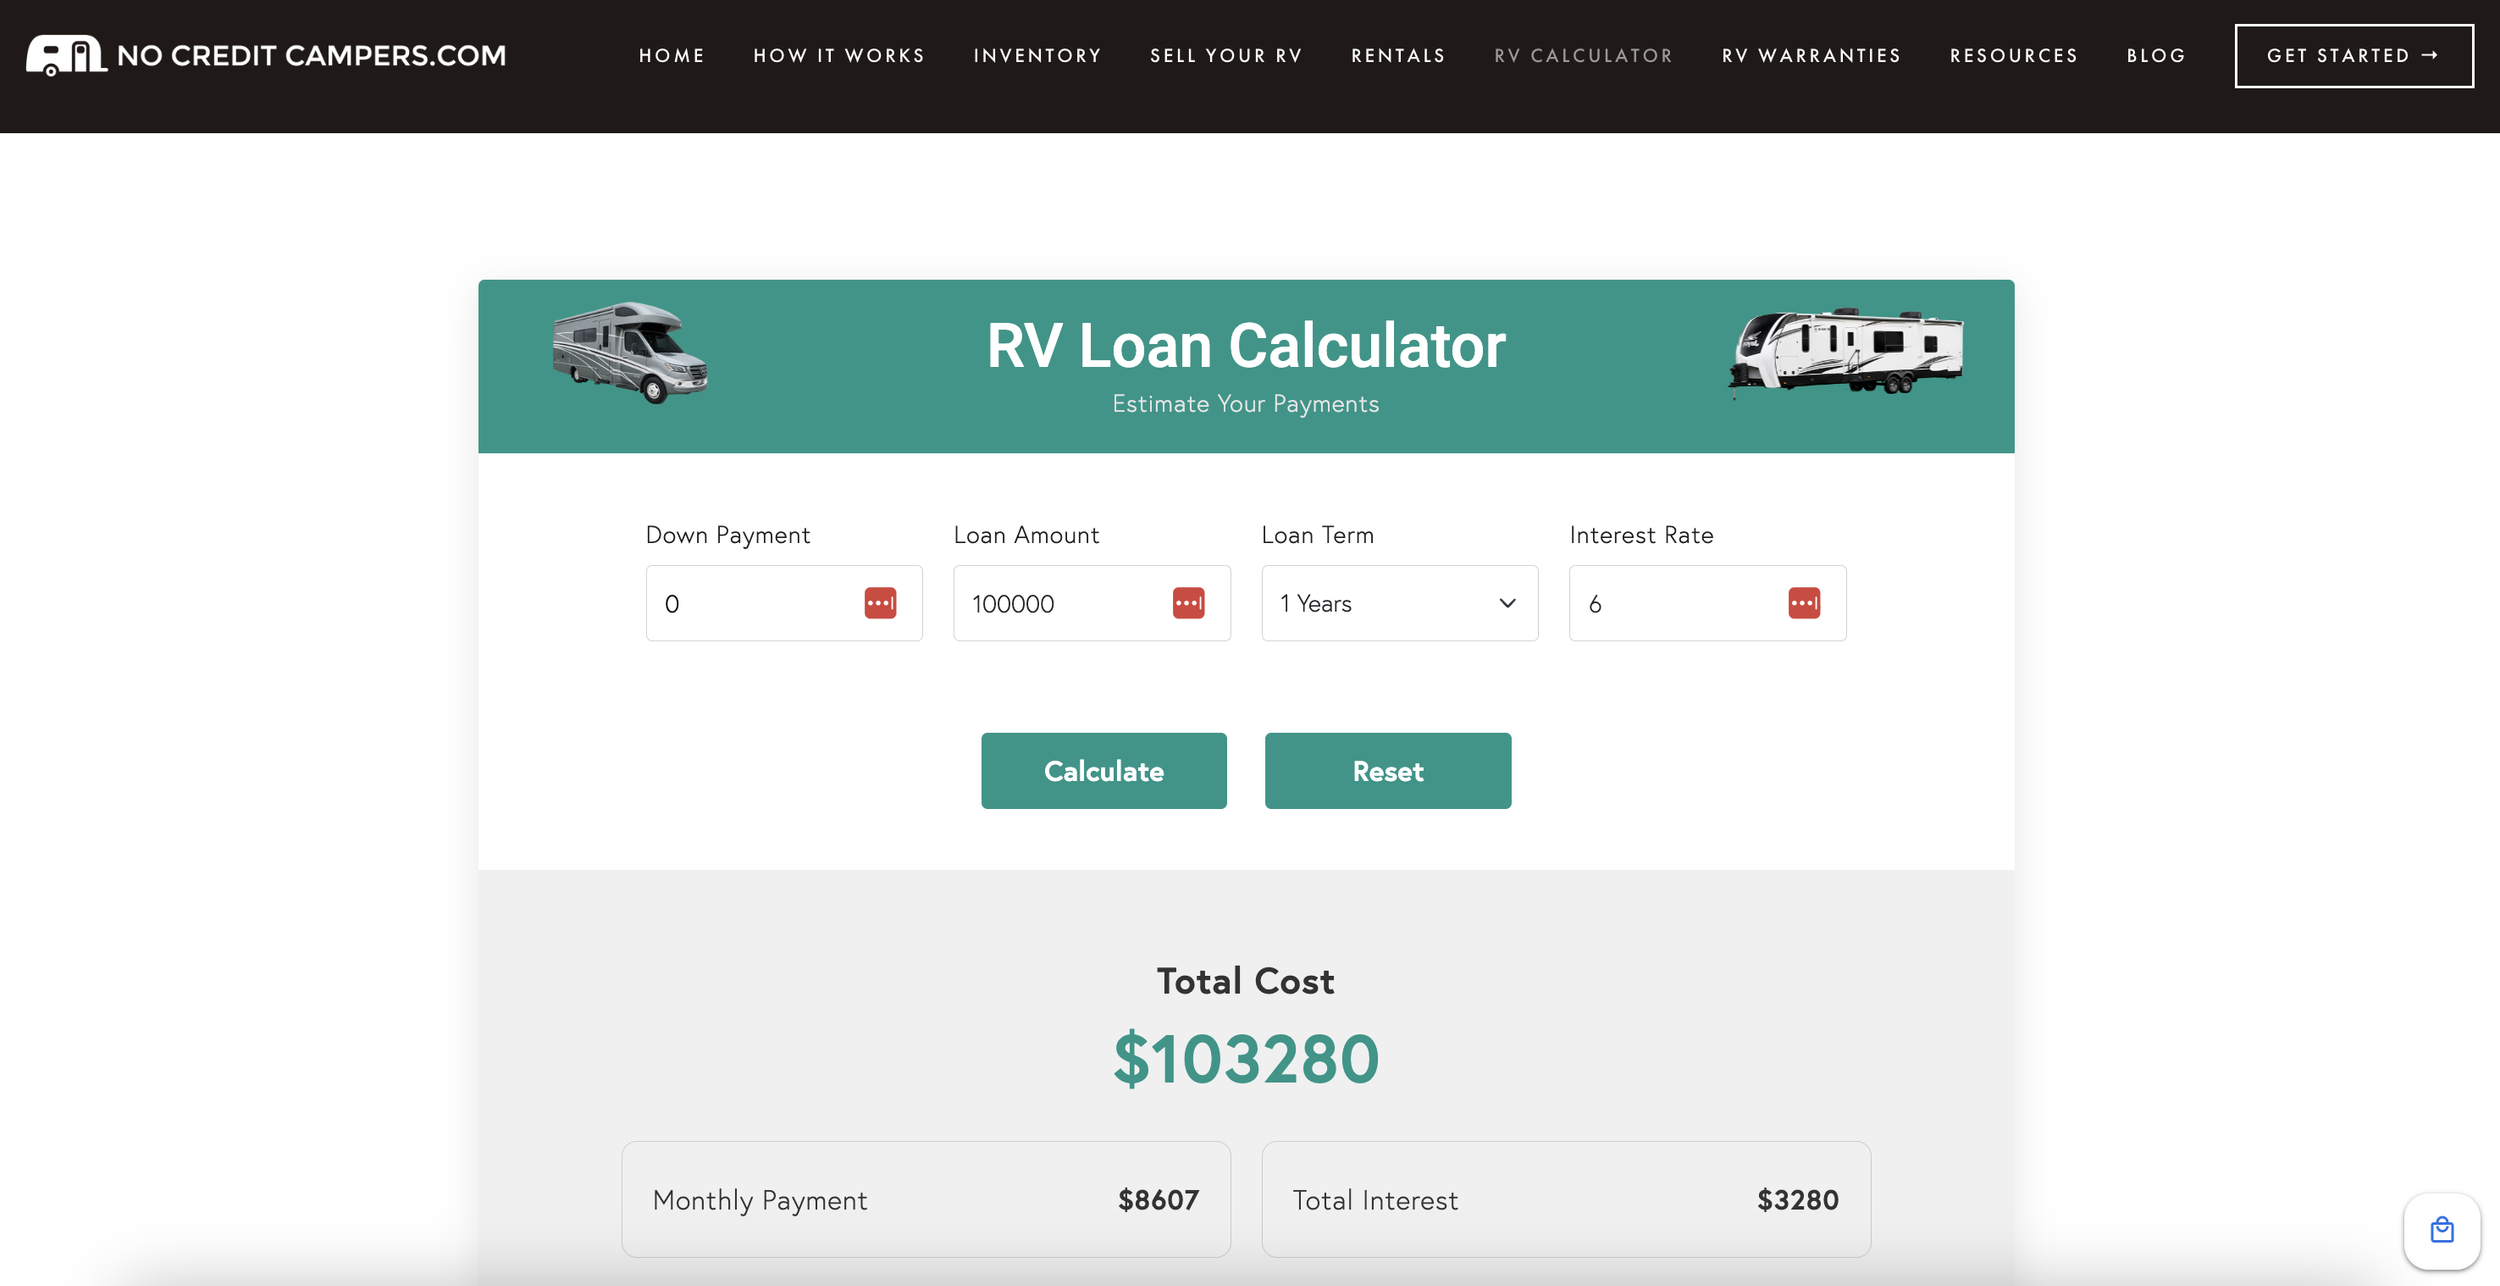
A travel trailer loan calculator estimates your monthly payment, total interest paid, and payoff timeline based on the inputs you provide. That's the basic version. The useful version tells you how changes to your down payment or loan term affect your total cost of ownership. It does both, but only if you feed it real numbers instead of optimistic guesses. Here's the straightforward process: you enter the purchase price, your down payment amount, the interest rate, and the loan term in months or years. The calculator applies the standard amortization formula and spits out a monthly payment. You then compare a few scenarios side by side to see what works for your budget. The formula behind it is straightforward enough that you don't need a calculator for basic cases, but most people use one anyway because they want to run multiple scenarios quickly. The real value is in comparing outcomes, not in deriving a payment from scratch.
Setting Up Your Inputs Correctly
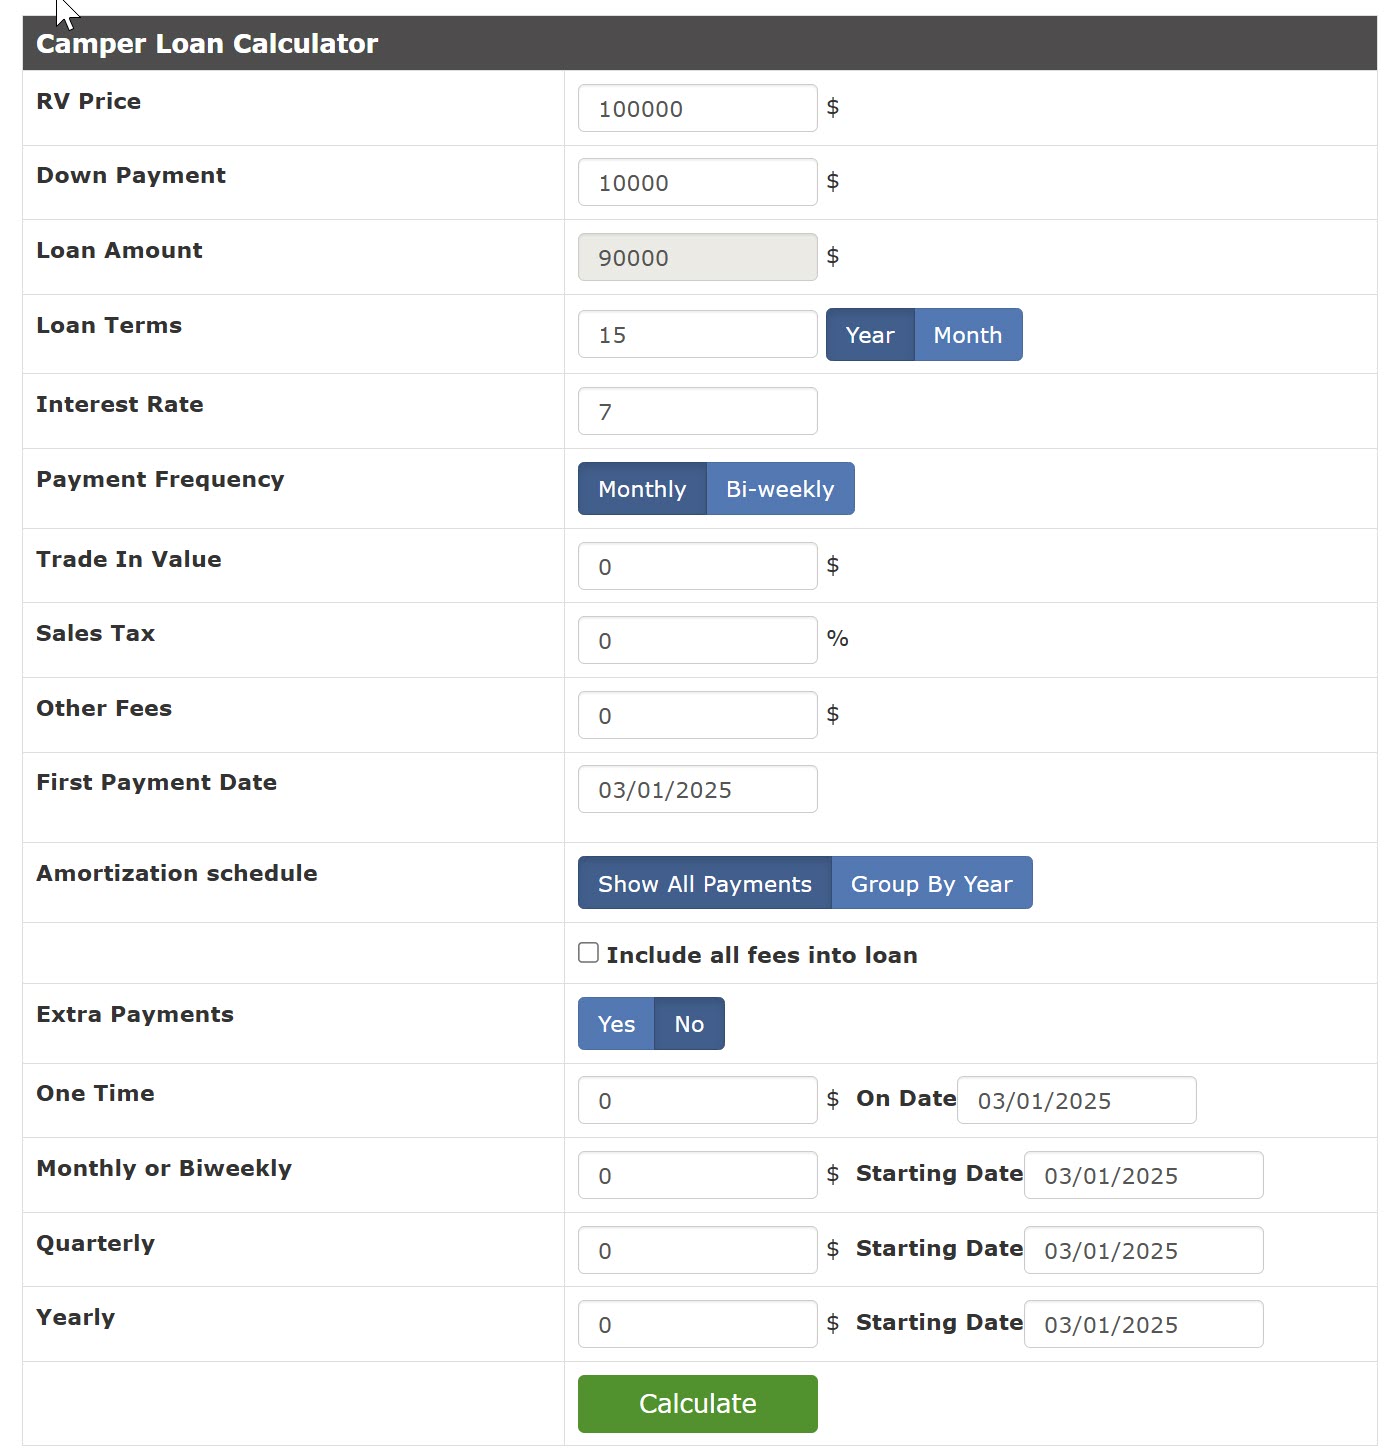
This is where people make mistakes. Let me walk you through each field and what actually belongs in it. Purchase price: Use the negotiated price, not the MSRP or the listing price. If you paid $18,500 but the sticker says $22,000, put in 18,500. Lenders base their financing on what you're actually paying, not what some catalog says. Down payment: This can be a dollar amount or a percentage. Most lenders expect at least 10 to 20 percent for travel trailers. If you're putting down less, your rate will likely be higher, and the calculator might not even show realistic results unless you adjust the interest rate field yourself. I once had a borrower run a calculator with a 5 percent down payment and a 6 percent rate. The bank offered him 9.2 percent. He ended up paying $400 more per month than he thought he would. That's a meaningful difference over a 60-month term.
Get the Full Details

Interest rate: Don't use the national average you found on a news site. Get a real rate quote from at least one lender before you rely on the calculator's output. Travel trailer rates vary widely depending on whether the trailer is classified as personal property or real property, and that classification changes the rate by a full percentage point or more in many markets. Loan term: Shorter terms mean higher monthly payments but significantly less total interest. A 36-month term versus a 72-month term on the same loan can save you thousands in interest. It's not just about monthly affordability. It's about total cost. Trade-in value: If you have a trade-in, subtract it from the purchase price before entering anything into the calculator. Some calculators have a trade-in field. Most don't. When in doubt, do the subtraction yourself and enter the net amount.
Advanced Nuances People Miss
Here's something most beginner guides won't tell you. A travel trailer loan calculator assumes a fixed-rate loan with level payments. That's true for most standard RV loans, but it's not always what you'll actually get. Some lenders offer balloon payments, which the calculator won't reflect without manual adjustment. If a lender gives you a 5-year amortization schedule with a balloon due at month 60, the monthly payment the calculator shows will be lower than your actual payment because the balloon amount is excluded from the monthly calculation. Another thing: property tax and insurance are not part of the loan payment. The calculator won't include them. But your lender will require full coverage insurance and may escrow taxes depending on how the loan is structured. A $18,000 travel trailer in a state with high RV registration fees might add $200 to $400 annually to your actual carrying cost. Factor that in when you're deciding whether the monthly payment fits your budget. The payment is only one piece of the monthly expense. I ran into a specific edge case once. A borrower was comparing a 48-foot fifth wheel against a 30-foot travel trailer. He used the calculator with identical loan terms and interest rates. The numbers looked fine for both. But the lender classified the 48-footer as a commercial vehicle because of its weight rating. That pushed the interest rate up nearly 2 percent. The calculator result was accurate for the inputs given, but the inputs weren't accurate because the classification changed the rate. I had him call the lender first to confirm the vehicle classification before running any calculations. Saved us both about two hours of rework.
Download and Use Your Own Copy
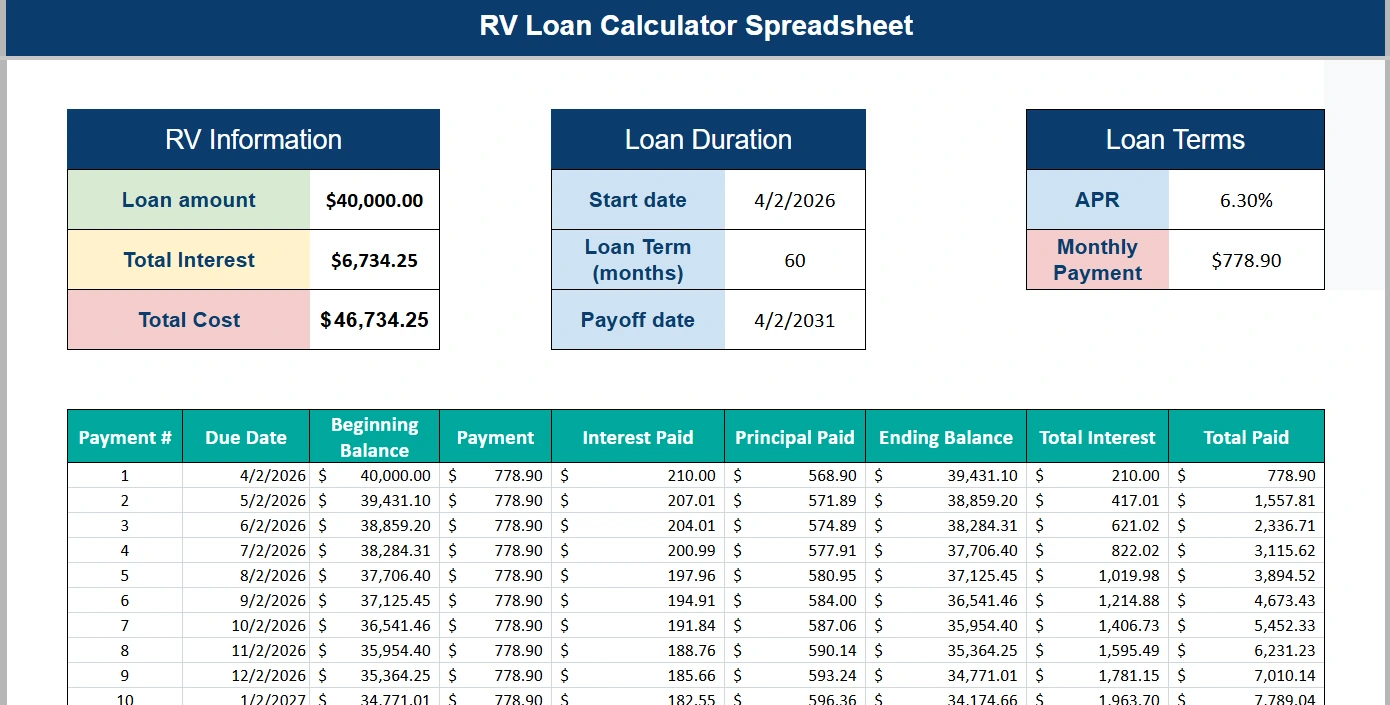
It's useful to have a travel trailer loan calculator you can download and use offline. Browser-based tools are convenient, but they change, disappear, or start charging for features. A local spreadsheet or downloadable file stays consistent. If you want a practical tool, build one in Google Sheets or Excel. Set up five input cells for purchase price, down payment, interest rate, loan term, and trade-in value. Then use the PMT function to calculate the monthly payment. The formula looks like this: =PMT(rate/12, term_in_months, -loan_amount). The rate should be your annual interest rate divided by 12. The loan amount is the purchase price minus the down payment minus the trade-in value. Negative the loan amount in the formula so the result comes out positive. Add a total interest paid cell using the CUMIPMT function. That will show you exactly how much interest you'll pay over the life of the loan. Most online calculators hide this number or bury it in a table. Having it in your own spreadsheet makes it easier to compare scenarios at a glance.
When the Calculator Is Wrong for You
There are situations where a travel trailer loan calculator gives you misleading results, and you should know about them before you trust it. Subprime rates: If your credit score is below 620, the rates you'll actually qualify for may not match whatever rate you assumed in the calculator. Lenders tier their RV rates aggressively at that end of the spectrum. A difference of 3 to 4 percent in rate is common for subprime borrowers. Run the calculator with a range of rates, not just one optimistic number. New versus used: Some lenders offer different rates for new and pre-owned travel trailers. A calculator that doesn't account for that distinction will give you a number that doesn't reflect reality. Check with your lender about whether the rate differs based on the age of the trailer.
Personal property tax variation: If you live in a state that taxes RVs heavily, the calculator won't include that. But your lender may require it to be paid into escrow. Again, the monthly payment the calculator shows is just the principal and interest portion. Your actual monthly obligation could be significantly higher. Short-term financing traps: Some lenders push 60-month terms aggressively because they look cheap on a calculator. But the total interest paid over 60 months can be close to the total interest on a 36-month loan, depending on the rate. The monthly payment drops, but the total cost doesn't improve as much as it seems. Always look at the total interest figure, not just the monthly payment.
Final Reality Check
A travel trailer loan calculator is a planning tool, not a commitment. It gives you a reasonable estimate when your inputs are accurate and your situation is straightforward. For standard fixed-rate loans on conventional travel trailers, it works well. For specialized cases, balloon payments, or subprime financing, it's only as good as your understanding of what it's leaving out. Verify everything with an actual lender before you sign anything. The calculator saved you time upfront, but the lender confirms the real numbers.