Figuring Out What You Actually Pay Each Month
Most people blow past the monthly payment when they're shopping for a travel trailer because they're focused on the sticker price. That's how you end up underwater on a loan you didn't realize was that big. A Travel Trailer Payment Calculator takes the purchase price, your down payment, interest rate, and loan term and spits out what your actual monthly obligation looks like. Simple enough, but the details matter more than most folks realize. I need to be straight with you about something I learned the hard way. A few years back, I was helping a buddy calculate his payment on a used 28-foot fifth wheel. The dealer quoted him a rate that sounded reasonable, and the calculator showed a payment he could swallow. But I missed one thing at first — the loan was structured as a hire-purchase agreement with a residual balloon payment at the end, not a traditional amortizing loan. The monthly looked great, but he was actually committing to a second lump sum he couldn't afford. I had him recalculate with the balloon factored in and the real picture came out completely different. Always make sure your calculator is pulling from the full loan structure, not just the headline number.
How to Use a Travel Trailer Payment Calculator
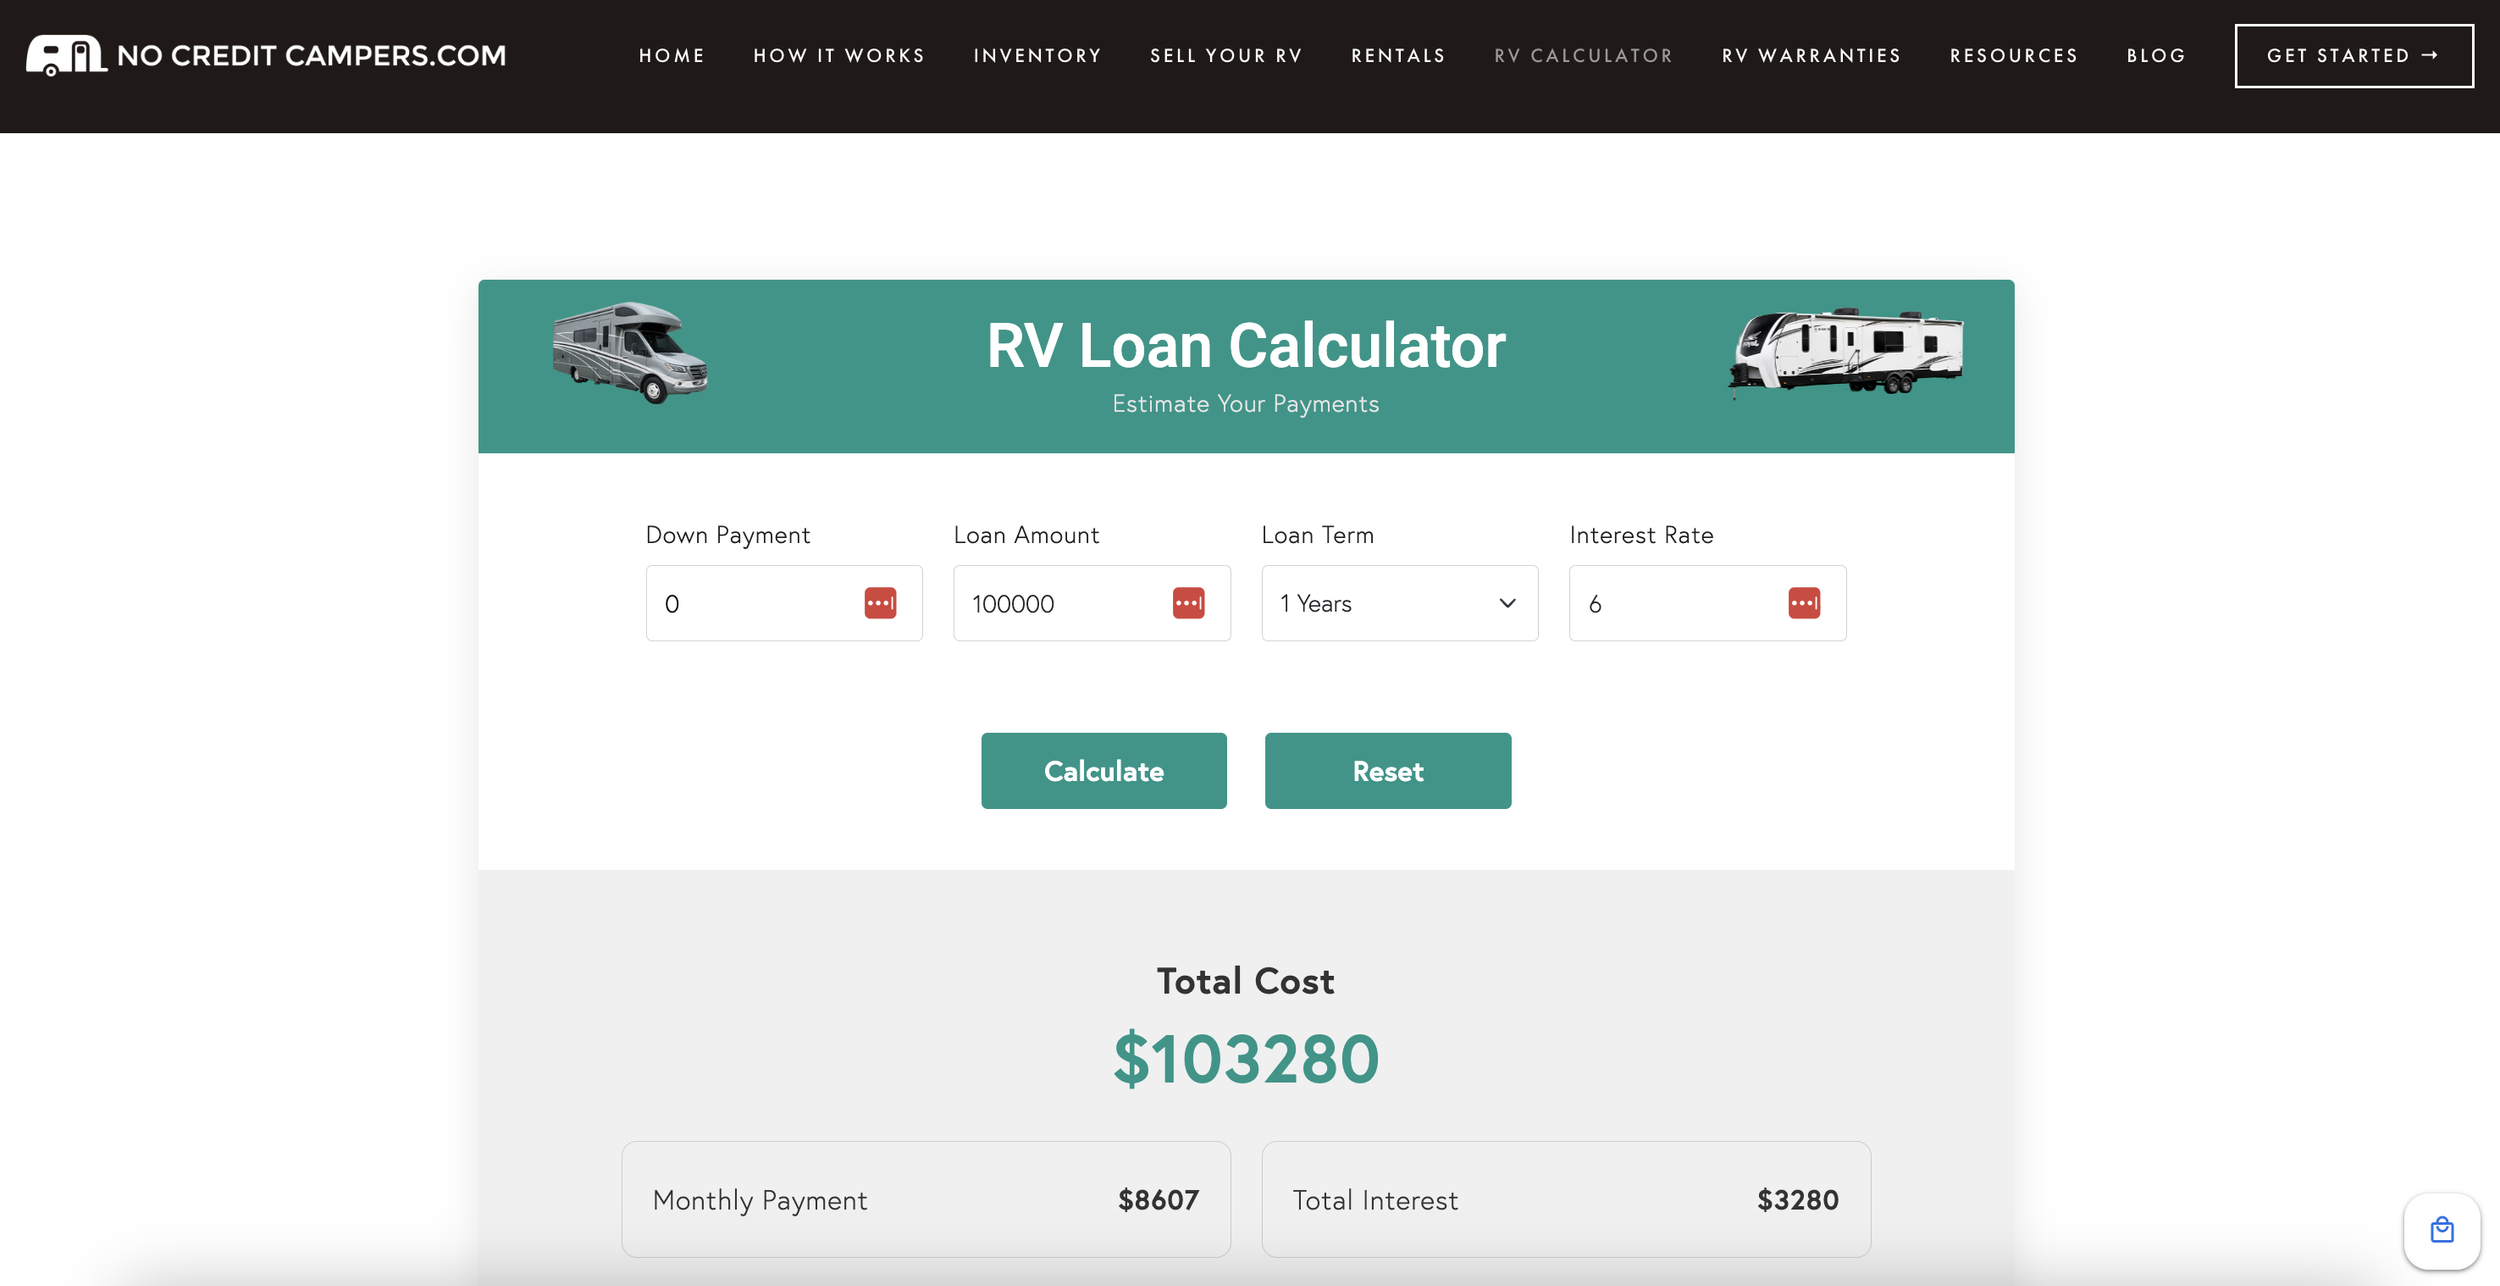
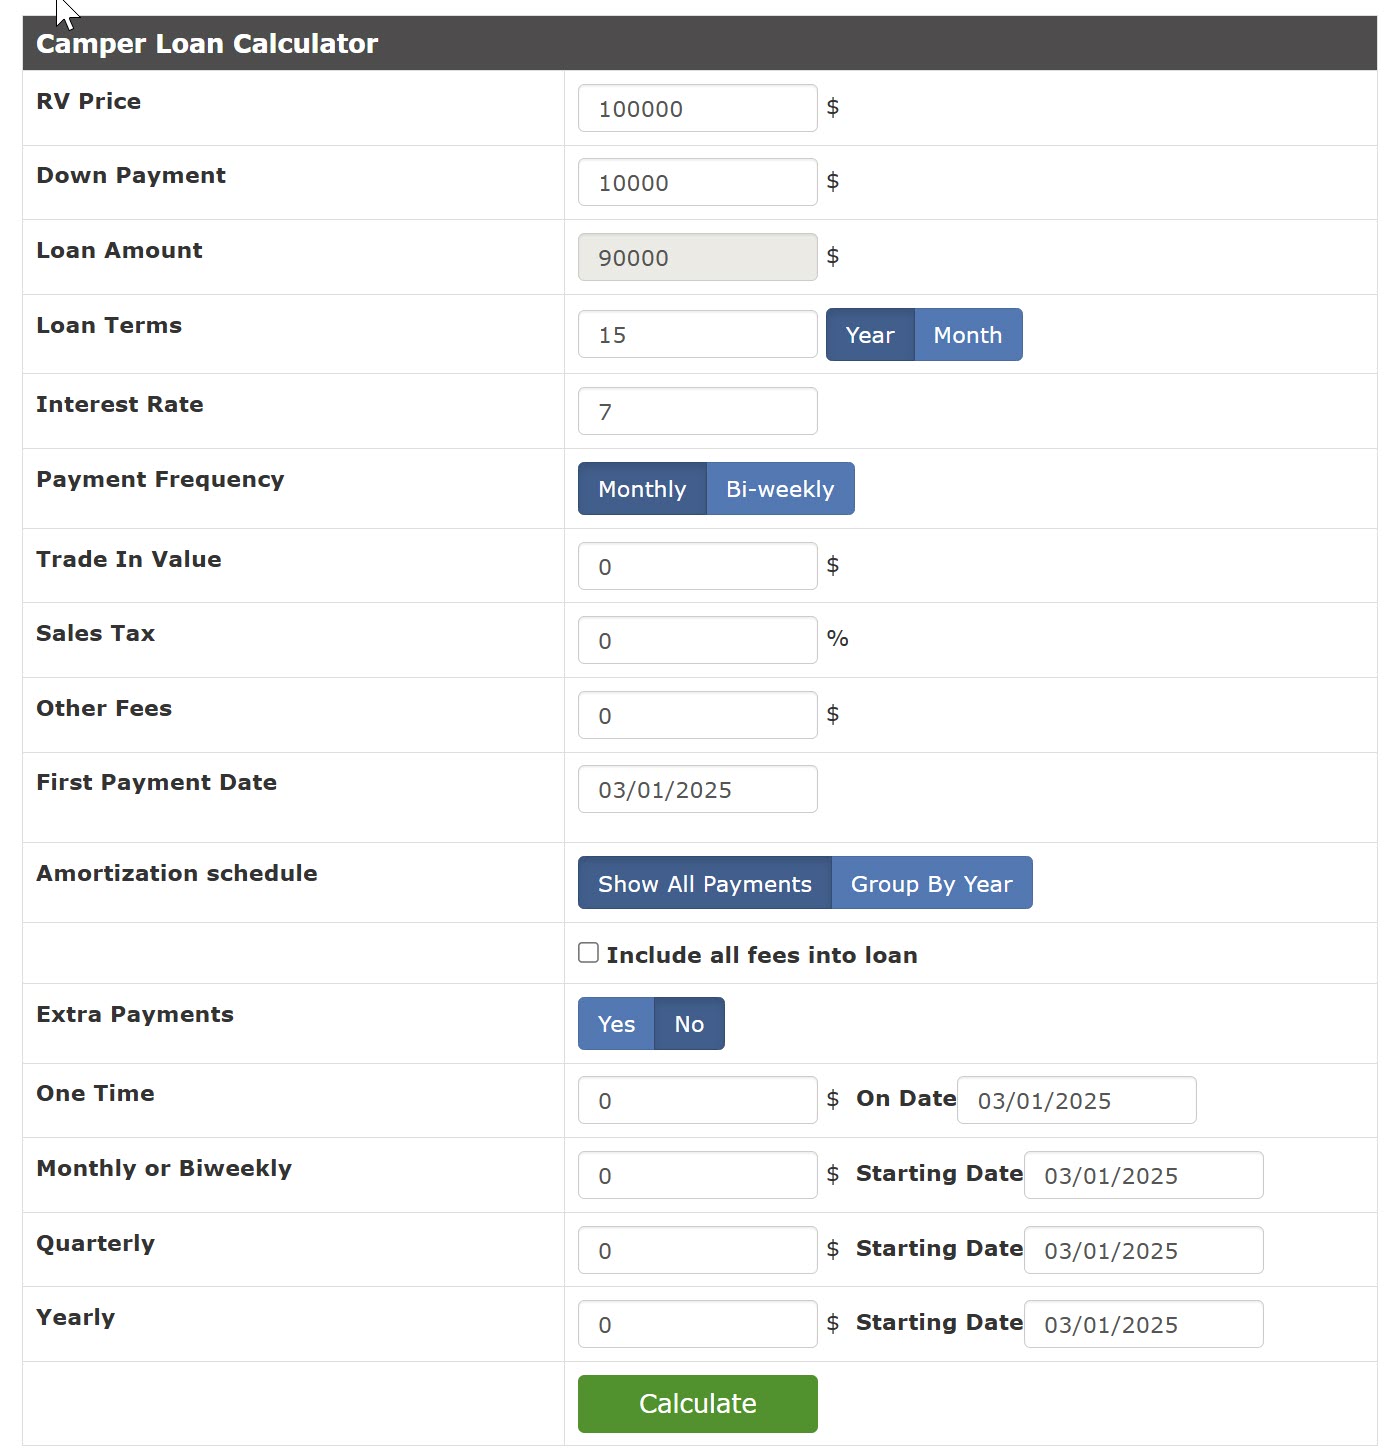
Grab a few numbers before you open anything. You need the total price of the trailer, which includes the base unit plus any dealer-added accessories, extended warranties, or delivery fees rolled into the contract. You need your down payment amount. You need the annual interest rate the lender is offering, and the loan term in months or years. If there's a balloon payment or trade-in credit, factor those in too. Enter the trailer price first. Subtract your down payment and any trade-in credit to get the financed amount. Plug in the annual interest rate and the term length. Hit calculate. The result shows your monthly payment based on standard amortization. Double-check that the calculator is using monthly compounding, which is standard for consumer auto and RV loans in the US. Some older or free online tools use simple interest formulas that will give you a slightly lower number than what the lender will actually charge. For the math behind it, the monthly payment formula is M = P × r × (1 + r)^n / ((1 + r)^n 1), where P is the principal after down payment, r is the monthly interest rate (annual rate divided by 12), and n is the total number of monthly payments. If you don't trust the online tool, you can run it yourself in a spreadsheet pretty quickly.
What the Payment Number Doesn't Tell You
The monthly payment is useful for budgeting, but it obscures several costs that show up later. Insurance premiums for a travel trailer typically run between $300 and $800 a year depending on coverage level and value of the unit. Registration and title fees vary wildly by state and can add another couple hundred dollars annually. Storage fees at a dedicated RV park or lot usually run $100 to $250 per month if you aren't keeping it at your home site. Maintenance and repairs average out to roughly 1 to 2 percent of the trailer's value per year, so on a $35,000 unit you're looking at $350 to $700 annually for things like tire replacements, sealant work, and appliance repairs. Here's a detail most calculators ignore entirely: the difference between the advertised APR and the out-the-door rate. Dealers sometimes quote a rate that doesn't include origination fees, documentation charges, or lender-installed products like gap insurance or tire-and-rim coverage. Those get baked into the actual cost of borrowing. In one case I tracked, a trailer listed at 5.9 percent APR ended up carrying a true cost closer to 7.2 percent once all the add-ons were included in the financed amount. That 1.3-point difference on a $28,000 loan over five years adds roughly $180 a month to the real payment.
Get the Full Details
When the Calculator Falls Short
Standard payment calculators assume a fixed-rate loan with equal monthly payments. They don't handle variable-rate loans, which are rare for RVs but do exist with some credit unions and specialty lenders. They also don't account for prepayment penalties, which some longer-term loans carry for the first two or three years. If you're financing through a private seller rather than a dealership or bank, the calculator still works but you should verify the interest rate is realistic for your credit tier. Personal loans meant for general use often carry higher rates than dedicated RV installment loans, and a calculator won't warn you about that unless you know to compare. Another limitation: these calculators assume you make every payment on time, every month. Late fees, missed payments, and the compounding effect of rolling fees into the balance are not built into any standard tool. If you've ever had a payment missed during a financial tight spot, you know the balance can creep up fast. Keeping a buffer of one to two payments in a separate savings account is something I'd recommend regardless of what the calculator shows.
A Practical Walkthrough
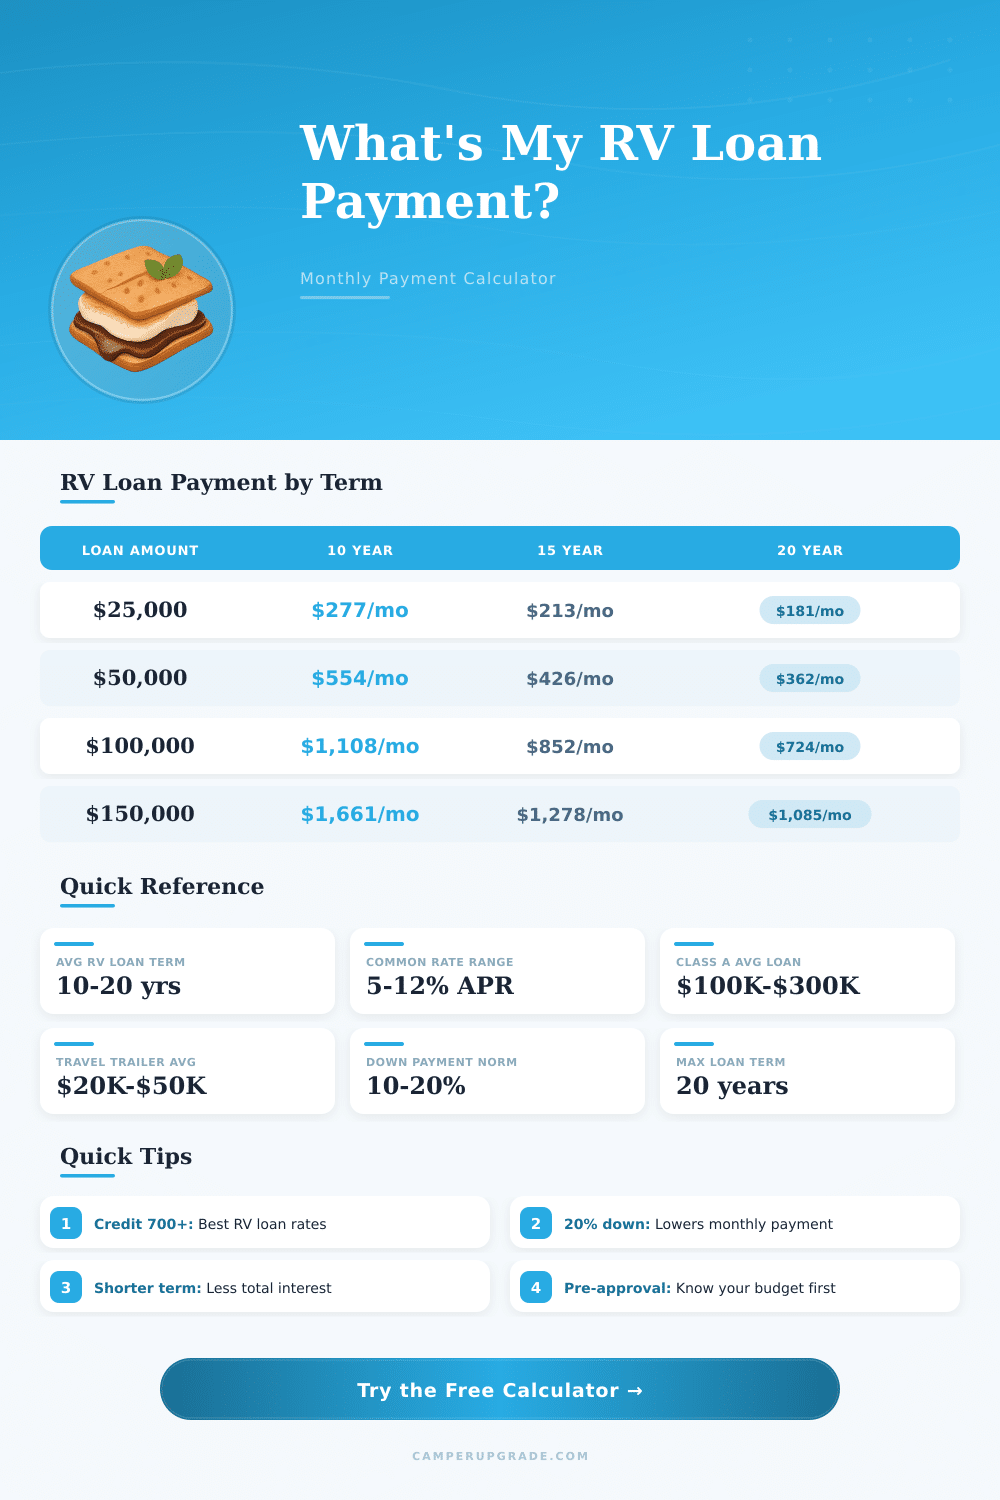
Say you're looking at a 30-foot travel trailer with a total out-the-door price of $42,000. You put down $8,000 and have a $3,000 trade-in credit, so the financed amount is $31,000. The dealer offers a rate of 6.5 percent over 72 months. Plugging those numbers into a Travel Trailer Payment Calculator gives you a monthly payment around $488. Over the full term you'll pay approximately $4,136 in interest, bringing your total cost to about $35,136 in loan payments plus your $11,000 down and trade credit. If you shorten the term to 60 months instead, the payment jumps to roughly $607 per month, but total interest drops to about $3,440. If you extend to 84 months, the payment falls to around $428 but total interest climbs to $5,552. The shorter term costs more monthly but saves you over a thousand dollars in interest. That's the trade-off every time you adjust the term length. I also learned to check whether the dealer is rolling in accessories like a solar kit, upgraded suspension, or a hitch system. Each of those can add $500 to $3,000 to the price before the calculator even runs. I started asking for a line-item breakdown before I input anything, and it saved me from calculating payments on a number that included things I didn't actually want.
Getting the Most Accurate Result
The single biggest improvement you can make to your calculator output is getting the exact terms from the lender before you shop. Dealer quotes are estimates. The final rate depends on your credit score at the time of approval, the specific loan product, and whether you qualify for any lender promotions. Call or apply with a credit union or online RV lender first, get a pre-approval with the real rate, then use that number in your calculator. It removes the guesswork and tells you the maximum you can responsibly spend. You should also verify whether the payment includes taxes and registration. Some calculators let you add those separately, others don't. If your state sales tax on RVs is 6 percent and the trailer is $42,000, that's another $2,520 baked into the financed amount, which shifts your payment noticeably. Run the calculator twice — once with taxes and registration included and once without — and compare. The difference shows you how much of your payment is going to government fees versus principal and interest. Finally, I keep a simple spreadsheet alongside whatever online calculator I use. I track the quoted rate, the calculated payment, the actual payment shown on the promissory note, and any fees that weren't in the original quote. It takes about five minutes per loan and has caught discrepancies three times for me. Once the numbers on paper matched the calculator, I felt confident moving forward. When they didn't, I walked away and shopped elsewhere.