How the numbers actually work when you're buying a commercial truck
Most people treat these calculators like magic boxes that spit out a monthly payment. They don't. They just do basic amortization math, the same way a bank does, with one small tweak: truck loans are usually short-term and have high rates because the asset depreciates fast. That's the baseline. Everything else is just plugging in different variables and seeing what moves.
Using a Truck Financing Calculator properly
The fields are always the same. Purchase price, down payment, interest rate, loan term in months, and sometimes trade-in value or fees rolled into the loan. You enter them, you hit calculate, and you get a monthly payment. The formula behind it is the standard annuity formula:
PMT = P × [r(1+r)^n] / [(1+r)^n - 1]
Where P is the principal, r is the monthly rate, and n is the number of payments. You don't need to type this in yourself, but knowing what's under the hood matters when the calculator gives you a number that feels off. Because it will, sometimes.
I ran into this exact problem last fall when a fleet manager was comparing quotes from two online calculators and one showed a payment $87 higher than the other for the same inputs. Turns out one was including dealer fees and origination charges in the principal automatically, while the other was only using the bare loan amount. He was ready to walk away from the second quote because it looked cheaper, not realizing it was excluding costs he'd actually have to pay. I had him pull the actual loan estimate from the lender and trace it line by line. The difference wasn't in the math. It was in what the calculator counted as the starting balance.
What actually changes the payment more than you'd think
The interest rate and the loan term fight each other every time. A lower rate sounds great, but if the lender extends the term to compensate, you might end up paying more over the life of the loan even though the monthly drops. I've seen this with CMVR loans where extending from 48 to 72 months cut the payment by roughly $120 a month but added nearly $3,400 in total interest on a $80,000 truck at 8.5 percent. The monthly feels better. The total cost does not.
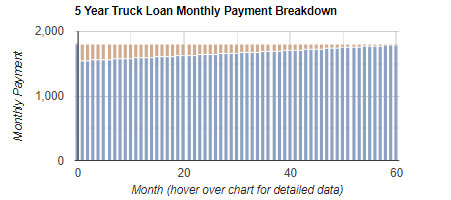
Down payment size has a nonlinear effect. Going from zero down to ten percent drops your payment significantly. Going from ten to fifteen percent? The savings shrink. Each additional percent of down payment moves less and less on the monthly because you're shaving principal at the top of the amortization schedule, not the bottom where the interest sits heavier early on.
Common pitfalls that will cost you money
Balloon payments show up a lot in truck financing. The monthly looks attractive because part of the principal is deferred to the end. If you're not prepared to refinance that balloon or sell the truck before it comes due, you're staring at a large lump sum you didn't plan for. I had a guy sign a three-year deal with a 30 percent balloon at the end. He made every payment on time, felt good about it, and then forgot about it until month thirty-five. He refinanced at a higher rate because his credit had shifted, and the balloon payment ended up costing him more than the savings from the lower monthly ever did.
Another thing people miss: prepayment penalties. Some commercial lenders charge a penalty if you pay off the loan early or refinance within the first two years. It's usually calculated as a percentage of the remaining balance or a set number of months of interest. If you're planning to upgrade trucks every three years, that penalty can eat into your equity and make refinancing less attractive than it looks on paper.
When the calculator breaks down
These tools assume a fixed-rate, fully amortizing loan. They don't handle variable rates, interest-only periods, or leases. If you're looking at a lease or a conditional sale agreement, the calculator output is meaningless for your actual obligation. You need a lease-specific model that factors in residual value, capital cost reduction, and the tax treatment, which is different depending on whether you're leasing or financing.
Applying for a truck loan with less-than-perfect credit changes the math entirely. The rate you see in the calculator might not be the rate you get. Lenders use different risk tiers, and commercial lenders especially tend to price based on the vehicle's value, your debt service coverage ratio, and business cash flow, not just your personal score. Run the numbers at the rate they quoted you in the application, not at the headline rate on the website.
What I actually do before signing anything
I run the calculator with my numbers first, then ask the lender for a written amortization schedule. I compare the schedule to what the calculator showed. If they don't match, I don't sign until I know why. Most of the time it's a simple fee inclusion issue, but occasionally it's a rate misstatement or a term that's slightly different than what was advertised. You catch these things in five minutes with the schedule. You don't catch them later.
A good rule of thumb: the total interest paid over the life of the loan should never exceed about 25 to 30 percent of the truck's purchase price. If it does, you're either financing too much, keeping the loan too long, or accepting a rate that's too high for the risk profile. All three are fixable if you catch them early.