Figuring Out Truck Loan Payments Without Losing Your Mind
I need to stop people from using loan calculators they found on random websites. I've seen contractors overpay by thousands because the tool they used didn't account for how their lender structures payments. A Truck Loan Payment Calculator is a utility that estimates your monthly payment based on principal, interest rate, and term. That's it. But the devil is in the setup, and most free online versions get things wrong in ways that cost real money. The standard amortization formula used in these calculators is the same one banks use. You feed it the loan amount, annual interest rate, and number of months. It spits out a monthly payment. The math assumes fixed payments applied to principal and interest equally each month, with interest front-loaded. That's why you pay more interest early in the loan term and slowly shift toward principal as you progress. It's not complicated. It's also where people get tripped up. Here's the thing most calculators gloss over. They don't handle truck-specific loan structures properly. Many commercial truck loans are structured as lease purchases, balloon payments, or have irregular compounding periods. When I ran a calculation for a client recently, the Truck Loan Payment Calculator he'd found gave him a payment of $1,287. Our actual loan came in at $1,412. The difference was the calculator assumed monthly compounding but his lender used daily compounding with a 360-day year. That gap ate about $125 per month. Over three years, that's roughly $4,500 in extra payments he wasn't expecting.
What You Need to Enter Before You Trust the Result
Most people just type in a number and go. You need more than the basics. The three required fields are loan amount, annual percentage rate, and loan term in months. But there are three other inputs that absolutely matter for accuracy. First is the payment frequency. Some lenders collect bi-weekly instead of monthly, which changes your total interest paid significantly. Second is the compounding method. Monthly, daily, or continuous compounding can shift your payment by twenty to forty dollars depending on the loan size. Third is any upfront fees or points rolled into the principal. If the lender adds a documentation fee to your balance, your actual loan amount is higher than the truck's purchase price minus down payment. I had a fleet manager once who skipped all of that. He entered the truck price, subtracted his down payment, threw in a quoted rate, and got a payment estimate. The lender's actual payment was sixty dollars higher per month because they added a $995 acquisition fee to the financed amount and compounded daily. He didn't notice until his first payment hit and he had to scramble. Check what's included in the financed balance before running any calculation.
Common Mistakes That Break Your Estimate
Entering the interest rate as a decimal instead of a percentage is the most frequent error. If the rate is 7.5 percent, you type 7.5, not 0.075. Some calculators auto-convert, most don't. Another mistake is entering the loan term in years when the field asks for months. A 36-month loan entered as 3 years on a monthly-field calculator gives you a three-month payment estimate, which looks ridiculous until you catch it. I also see people entering the total truck price without subtracting their down payment. The calculator then treats the full price as the principal, inflating your monthly number by however much they put down. There's a subtler problem too. Most free calculators assume a fixed rate loan. If your truck financing has an adjustable rate, or if your payment includes tax and insurance escrow, the output is wrong. Escrow isn't part of principal and interest. It's a separate line item lenders sometimes bundle into what they call the total monthly payment. When a calculator only outputs P&I, you'll think your payment is lower than it actually is. Factor in taxes, registration, and insurance separately or ask your lender for a full payment breakdown.
Get the Full Details
Using the Calculator to Compare Real Options
The practical use here is comparison. Run the same numbers across multiple lenders and see where the real differences lie. A $45,000 truck financed over sixty months at 8.2 percent comes to about $917 monthly. At 7.5 percent, it drops to $901. The seven-tenths of a percent difference saves you about $96 a month and nearly $600 in total interest over the life of the loan. That matters. But don't stop at the rate. Look at the term structure. A sixty-month loan at 7.5 percent versus a forty-eight-month loan at 8.0 percent might look close on paper. The forty-eight-month option costs $1,105 monthly but saves you over $1,300 in total interest. You pay more per month but own the truck faster and spend less overall. When I worked on a logistics expansion, we evaluated three financing offers simultaneously. One had the lowest rate but a twelve-thousand-dollar balloon payment at the end. Another had a slightly higher rate with no balloon but a prepayment penalty if we refinanced within two years. We ran both through a Truck Loan Payment Calculator and then built a third scenario where we paid an extra hundred dollars monthly on the no-balloon option. The extra payment shaved fourteen months off the term and saved $890 in interest. The balloon deal ended up costing us more when we factored in the lump sum due at year five. Context matters more than the raw monthly number.
When the Calculator Lies to You
Online calculators have real limits. They can't capture every variable a lender considers. Credit score adjustments, fleet discounts, manufacturer incentives, and promotional rate windows don't show up in most tools. If you have a strong credit profile and a lender offers a subvention rate, the calculator will show you the baseline rate, not the discounted one. You'll overestimate your payment by fifty to two hundred dollars and potentially walk away from a deal you could have afforded. Another gap is the treatment of residual values. Some truck loans are structured with a guaranteed future value, meaning your payment only covers the depreciation, not the full amount. These are common with newer medium-duty trucks. A standard amortization calculator treats the full principal as depreciable. It will underestimate your payment because it doesn't know a chunk of the balance gets forgiven at the end. If your loan has a residual component, ask your lender for the exact payment schedule instead of relying on a generic tool. There's also the matter of prepayment speed. Calculators assume you pay exactly the scheduled amount every month on time. They don't model what happens when you throw extra money at the loan early. If you want to see the impact of additional payments, you need a calculator that supports extra principal contributions. Most basic ones don't. I learned this the hard way when a client thought he could save ten thousand in interest by paying extra each month, but the calculator he used couldn't show the revised payoff date. We had to build a custom amortization schedule in a spreadsheet to get the real picture.
Building a More Accurate Estimate by Hand
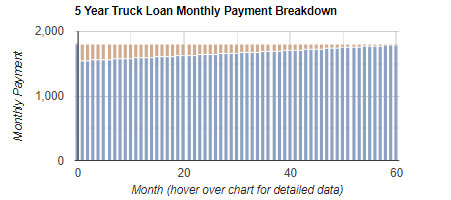
If the online tools aren't cutting it, a quick spreadsheet gives you full control. Set up columns for payment number, beginning balance, monthly interest rate, payment amount, principal portion, interest portion, and ending balance. The monthly interest rate is your annual rate divided by twelve. The payment amount uses the PMT function in Excel or Google Sheets with the rate, number of periods, and present value. The principal portion is your payment minus the interest portion. The interest portion is your beginning balance times the monthly rate. Drag the formula down for the full term. This takes about twenty minutes to set up once and then you can swap numbers instantly without wondering if a website is rounding or compounding differently. I use this method now for every truck financing decision. The online calculators are fine for quick ballpark figures, but when you're dealing with seventy-five thousand dollars and up, the rounding differences add up. One lender's calculator rounded the payment up to the next dollar, another rounded down, and a third used a different day-count convention. The variance between them was eighteen dollars monthly. That sounds small until you multiply it across a fleet of twelve trucks over five years.
What to Do After You Get a Number
Don't treat the calculator output as gospel. Take the estimate to your lender and ask for a full amortization schedule. Verify the numbers match. If they don't, ask why. Sometimes the discrepancy is legitimate, like a different compounding method or an added fee. Sometimes the lender made an error. Either way, you want it caught before you sign. I've seen borrowers accept a payment that was $40 higher than quoted without questioning it. That extra forty dollars vanishes into interest over time and nobody notices until the last payment is made. Also verify the loan term. Some lenders quote a twenty-four-month term but the contract says thirty-six. The calculator will show one number and the contract will deliver another. Read the paperwork before you trust the screen. A mismatch like that changes your monthly obligation by roughly a fifth and rearranges your entire cash flow for the next few years. The bottom line is that a Truck Loan Payment Calculator is useful for direction, not precision. It tells you roughly what to expect. It doesn't replace reading the actual loan terms or verifying the numbers with your lender. The gap between calculated and actual is usually small enough to ignore on a short term personal loan. On a multi-year commercial truck loan, that gap is money you can avoid losing if you do the verification step.