Understanding Trust Busting in US History
The term trust busting refers to the legal and political effort to break up monopolies and powerful business combinations that restrict competition. In the United States, this became a major federal policy tool starting in the late 1800s and continuing through the 1900s. The Sherman Antitrust Act of 1890 was the first real federal weapon, and it gave the government the authority to challenge combinations "in restraint of trade." That phrase was pretty vague on paper, which meant early cases were all about figuring out what it actually covered. At its core, trust busting is the government's use of antitrust laws to dissolve or restrict monopolistic business trusts. A trust is just a legal arrangement where stockholders hand their shares to a board of trustees who then control multiple companies as a single unit. Standard Oil used this structure famously. You can look at the Northern Securities case from 1904, where the Supreme Court ordered the breakup of a massive railway holding company, or the later Standard Oil breakup in 1911 that created seven separate companies including what would become Exxon and Mobil. Those are the textbook examples everyone learns in high school civics, but the reality was messier than that. The Clayton Act of 1914 filled in some gaps left by the Sherman Act. It specifically prohibited price discrimination that lessened competition, exclusive dealing agreements, and interlocking directorates where the same people sat on the boards of competing firms. The Federal Trade Commission was also created the same year to enforce these rules. Before that, enforcement was basically just litigation, which is slow and expensive. Having a dedicated agency changed the calculus significantly.
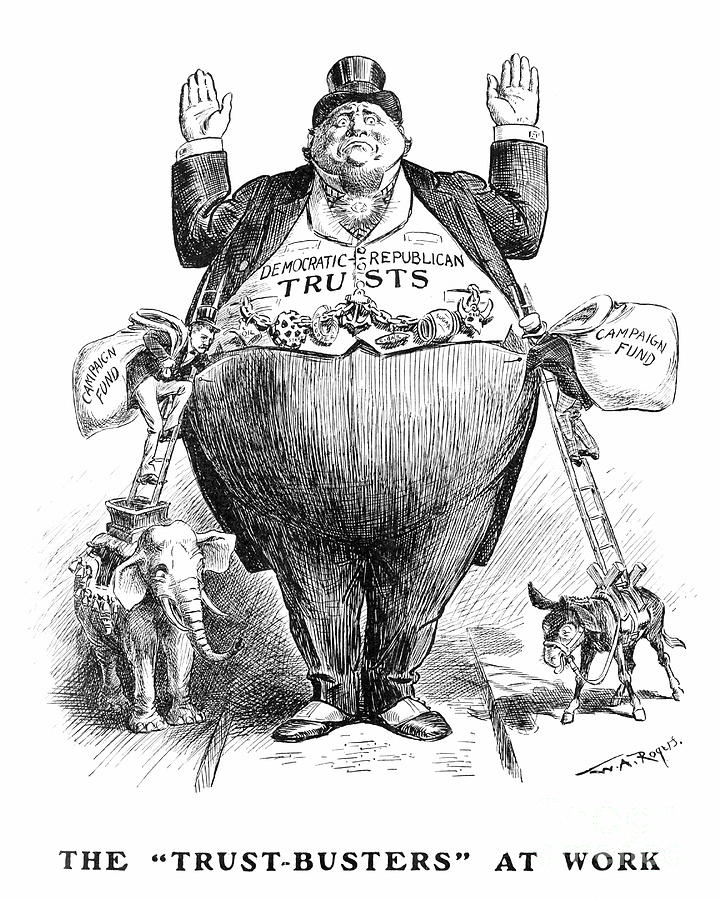
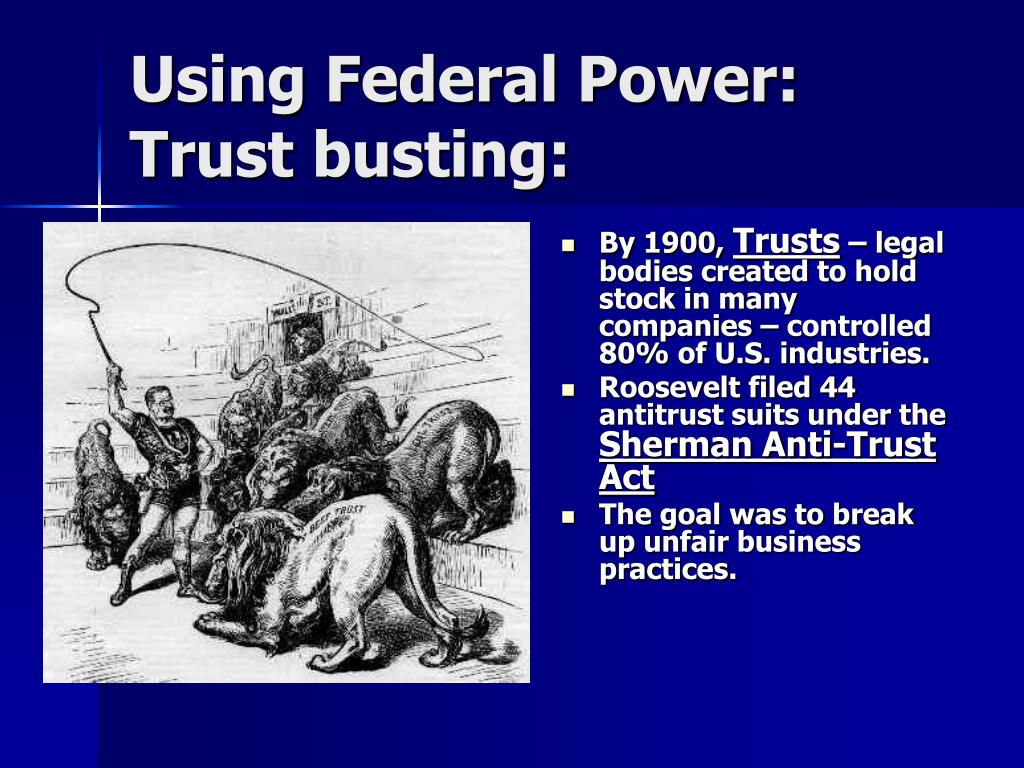
Here is something most people do not realize: trust busting was never just about economics. It was deeply political. The Progressive Era populists had genuine anger toward concentrated corporate power, and politicians from both parties leaned into it because their constituencies felt squeezed by railroad rates and oil prices. Theodore Roosevelt earned the nickname "trustbuster" but he actually distinguished between good trusts and bad trusts. He went after Northern Securities because it was an obvious predatory monopoly, not because he opposed all large companies. That nuance gets lost in textbooks. Roosevelt even defended the existence of some big corporations as natural outcomes of efficient industrial organization. Woodrow Wilson took a harder line in practice through the Clayton Act and the FTC, but his administration was also constrained by World War I, which shifted federal priorities toward production and price controls rather than antitrust enforcement. The 1920s were essentially a quiet period. Courts became more sympathetic to businesses, and the Department of Justice under Harding and Coolidge pursued very few major cases. The Great Depression revived interest, and FDR's administration filed more antitrust suits than any president before him, though many of those cases were slow to resolve.
How Trust Busting Actually Worked in Practice
The process started with a complaint or an investigation. The DOJ could file a civil suit seeking an injunction or a breakup, or in rare criminal cases pursue felony charges against individuals. The burden of proof rested on the government. Under the Sherman Act, you had to demonstrate that a combination restrained trade. Early courts interpreted that narrowly. In United States v. E.C. Knight Co. (1895), the Supreme Court ruled that manufacturing was not commerce, so the Sugar Trust escaped federal scrutiny. That decision effectively neutered the Sherman Act for nearly two decades and shows why the legal framework mattered as much as the political will. When the courts did side with the government, remedies varied. Some cases ended in consent decrees where the company agreed to change its behavior without admitting guilt. Others resulted in full structural breakups. United States v. American Tobacco Co. (1911) is a good example. The Court found the tobacco trust had illegally monopolized the market and ordered it split into several independent companies, including what became Liggett & Myers and R.J. Reynolds. The decree took years to implement because untangling shared patents, brand identities, and distribution networks is enormously complicated. One practical challenge that comes up repeatedly is defining the relevant market. Is the market national or global? Is it product-specific or does it include close substitutes? In the Standard Oil case, the government argued a national gasoline and kerosene market. Standard Oil countered that foreign imports and alternative fuels mattered. The Court ultimately accepted the government's view, but market definition remains one of the most contested issues in antitrust litigation. You see it again in modern cases involving digital platforms, where the relevant market might be online advertising or app distribution rather than the consumer product itself.
Get the Full Details
I should mention a specific edge case from my own reading of the records: the United States v. U.S. Steel (1920) case. The government argued that U.S. Steel's acquisition of Tennessee Coal, Iron and Railroad Company in 1907 violated the Sherman Act because it increased concentration. The Supreme Court disagreed, ruling that the acquisition itself had not been illegal at the time and that mere size did not equal monopoly power. This is a critical lesson. Being big is not a crime under antitrust law. Abusing that size is what triggers enforcement. That distinction matters enormously and it is where a lot of modern cases get stuck. Companies can grow to enormous scale through efficiency and innovation without crossing into illegal territory. The Justice Department'santitrust division has internal guidelines for evaluating mergers and conduct. The Herfindahl-Hirschman Index measures market concentration. Below 1500 is considered unconcentrated, between 1500 and 2500 is moderately concentrated, and above 2500 is highly concentrated. Mergers in highly concentrated markets face intense scrutiny. These tools did not exist in the early trust-busting era, which is why outcomes were so unpredictable back then. Lawyers and judges were basically making it up as they went along.
Limitations and Why Trust Busting Fails Sometimes
Trust busting has real limitations. One is timing. By the time a case is filed, investigated, and litigated, the market may have already changed. Technology shifts, new entrants appear, or consumer preferences move. Standard Oil was broken up in 1911, but the oil industry had already begun shifting toward automobiles and away from kerosene. The breakup did not prevent the emergence of new giants. Another issue is that structural remedies do not guarantee competition. Splitting Standard Oil into thirty-five companies did not create a perfectly competitive market. Many of those companies still held dominant regional positions. There is also a political dimension that cuts both ways. When enforcement succeeds politically, it can embolden further action. When it fails, it can chill future efforts. The decline of antitrust enforcement in the 1970s and 1980s under the influence of the Chicago School is a case in point. Scholars like Robert Bork argued that consumer welfare should be the sole standard, and that many practices previously condemned were actually efficiency-enhancing. This shifted the legal framework dramatically. The Department of Justice under Reagan filed far fewer cases, and when it did sue, it often lost. AT&T's breakup in 1982 was an exception, and even that was driven more by regulatory negotiation than pure antitrust ideology. The global dimension is another constraint. American antitrust law does not apply extraterritorially in a straightforward way. Foreign companies operating in the US are subject to it, but coordination among competitors across borders raises jurisdictional questions that the courts have struggled with. The International Trade Commission and the DOJ have worked together on cases involving import cartels, but the legal authority is narrower than domestic enforcement.
If you are studying this period for a paper or a project, I would recommend looking beyond the famous cases. The administrative records of the FTC and the DOJ from the 1910s through the 1930s contain hundreds of smaller investigations that never reached the Supreme Court. Those matter because they shaped business behavior through the threat of enforcement, not just through courtroom victories. Most companies complied voluntarily rather than fight. The deterrent effect was arguably more important than any single breakup. One counterintuitive finding from the historical record: the earliest trust-busting cases actually strengthened rather than weakened the position of large firms in some industries. After Standard Oil was broken up, the new companies learned to coordinate pricing through informal channels rather than formal trusts. The structure changed but the behavior did not entirely. That is a recurring pattern in antitrust enforcement. Companies adapt around restrictions. This is why modern antitrust scholars focus more on conduct than structure. The conduct-based approach tries to address the behavior directly rather than assuming that splitting a company solves the problem. The evolution from the Sherman Act through the Clayton Act and the FTC Act represents a broadening of the legal toolkit. But the underlying tension remains unresolved: how do you balance efficiency gains from scale against the risks of concentrated power? There is no clean answer, and that is probably why trust busting continues to be debated over a century later.