What the TSP C Fund Actually Is and Why It Matters
The TSP C Fund is the Thrift Savings Plan's equivalent of an S&P 500 index fund. It tracks the performance of large-cap U.S. stocks — the 500 biggest publicly traded companies in America. That's it. No fancy derivatives, no sector concentration, no active management. Just a broad market cap-weighted index with an expense ratio around 0.03%, which is about as cheap as it gets. If you're looking at Tsp C Fund Today, you're probably trying to figure out whether it belongs in your allocation and how much of it. The C Fund has been the workhorse of the TSP for most participants who want stock exposure. It's not the only stock fund available — there's the F Fund for total U.S. market, the G Fund for the government securities side, and the international exposure through I and S funds — but the C Fund remains the default choice for a reason. Here's the thing most people miss: the C Fund and the F Fund overlap significantly. The F Fund covers the entire U.S. large, mid, and small-cap market, while the C Fund covers only the large caps that make up the S&P 500. About 80% or more of the F Fund's holdings are also in the C Fund. When someone allocates heavily to both, they're not really diversifying — they're just buying the same stocks twice with slightly different weighting.
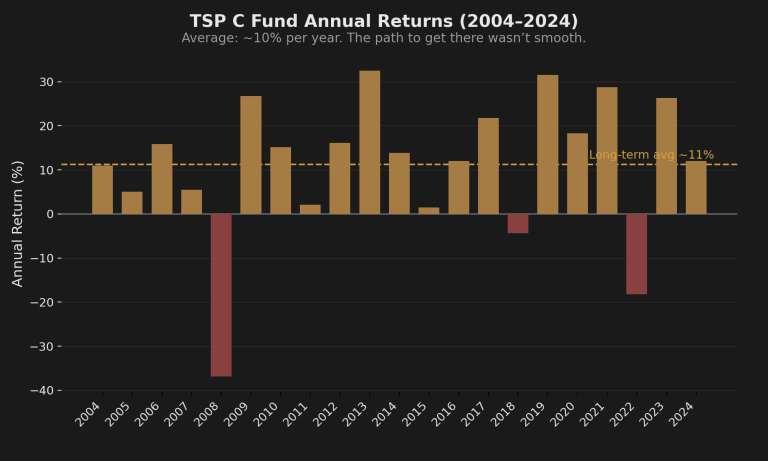
I ran into this exact problem a few years ago when a colleague was building what he thought was a diversified TSP portfolio. He had 40% C Fund, 30% F Fund, and 30% G Fund. On paper it looked balanced. In reality, his stock allocation was essentially all large-cap U.S. with a tiny bit of small and mid-cap tacked on through the F Fund. I showed him the overlap numbers and he switched to a simpler split — 60% C Fund, 40% G Fund — and stopped worrying about it. Less is genuinely more here. The C Fund's main weakness is its concentration in a handful of mega-cap stocks. At various points in the last decade, the top 10 holdings have accounted for well over 25% of the fund's total value. When tech stocks rally, the C Fund rides that wave. When they correct, it doesn't matter how diversified the S&P 500 supposedly is — you're still getting hit hard. This isn't a reason to avoid the fund, but it is a reason to understand exactly what you're holding instead of treating it as some kind of universal solution. Another counter-intuitive point: the C Fund is not the best stock fund for pure long-term growth if you're young and have decades before retirement. The F Fund, which includes small and mid-cap stocks, has historically outperformed the C Fund over full market cycles by a meaningful margin. The tradeoff is higher volatility and deeper drawdowns. If you can stomach seeing your balance drop 40% and not panic-sell, the F Fund makes more sense. Most people can't stomach that, which is why the C Fund stays popular.
How to Actually Use the C Fund in Your TSP
Contributing to the C Fund is straightforward — you log into your TSP account, go to Contributions, and enter the percentage you want allocated. You can change this at any time with no restrictions. The real question is what percentage, and that depends entirely on your age, risk tolerance, and whether you plan to keep working. Here's a practical framework that actually works in practice. If you're under 40 and not expecting to retire early, a 70-80% stock allocation split between C and F funds is reasonable. Add the G Fund for stability if markets get scary, which they will. If you're over 50 and closer to retirement, shift more into the G Fund. The C Fund isn't going anywhere, but you need capital preservation once you're within five years of pulling money out. One edge case that catches people off guard: the autoLifecycle fund. If you're enrolled in one of these and also making manual contributions, your manual dollars go where you tell them and the auto fund keeps doing its thing. I've seen people accidentally double up on stock exposure because they thought their manual C Fund contribution was replacing the auto fund's stock allocation. It's not. Both are happening simultaneously. Check your actual allocation page, not just your contribution settings.
Get the Full Details
Withdrawals and the C Fund
When you start taking money out, the C Fund becomes a liability if you're withdrawing during a down market. This is sequence of returns risk, and it's the single biggest threat to retirees who kept 80% of their portfolio in stock funds. A 30% drop in the C Fund right when you start withdrawing can permanently damage your portfolio's longevity. The standard workaround is keeping at least two years' worth of expenses in the G Fund or a money market fund, so you're not forced to sell C Fund shares at a loss. The LOA and SEP options also interact with the C Fund in ways people don't always think about. If you take a Loan Against your TSP balance, the borrowed amount continues to be invested according to your allocation. That means if you have 60% in the C Fund and take a loan, your loan balance is effectively also exposed to market movements. During the 2022 correction, I watched several people lose ground on their loans because the C Fund dropped while they were still paying it back with after-tax dollars. It's a double hit — you owe the money and you lost value on it. If you're considering leaving the FSE or taking a Separation from Federal Service, the C Fund doesn't need special handling beyond your normal allocation preferences. You can roll it into an IRA, leave it in the TSP, or take a lump sum. The tax implications are the same regardless of which fund the money came from. What matters is your overall tax situation and whether you want to keep the TSP's low fees or move everything to a brokerage account.
The C Fund will continue to be a core component of TSP portfolios for the foreseeable future. It's not exciting, it doesn't outperform the broader market, and it won't save you from making bad decisions. But for someone who just wants broad U.S. stock exposure at the lowest possible cost, it does exactly what it promises. The trick is knowing when to use it and when to step back.