Learning to do accounting properly in 2026 is less about memorizing debits and credits and more about understanding what changed since the last cycle of software updates and regulation shifts.
I spent the first three weeks of my junior year of university trying to reconcile a practice set in QuickBooks that had a vendor invoice split across two months because of a timing glitch in the import function. The journal entry needed to span November and December, but the software auto-posted it to a single date based on the document upload timestamp rather than the invoice date. I stared at a mismatched balance for an hour before someone pointed out that the "Match by" setting was on Created Date instead of Invoice Date. That was my first real lesson: the tool works correctly when configured properly, but it doesn't work correctly by default, and fixing it requires reading the settings rather than forcing the numbers to cooperate. The accounting landscape in 2026 looks very different from ten years ago. Automation handles most of the data entry that used to eat up a third of a junior accountant's week. Receipt scanning, bank feed reconciliation, and automated categorization mean the entry-level work has shifted from transcription to verification and exception handling. The skill that matters now is knowing when the automated system got something wrong and how to correct it without breaking downstream reports.
Tutorial For Accounting 2026: Where to Actually Start
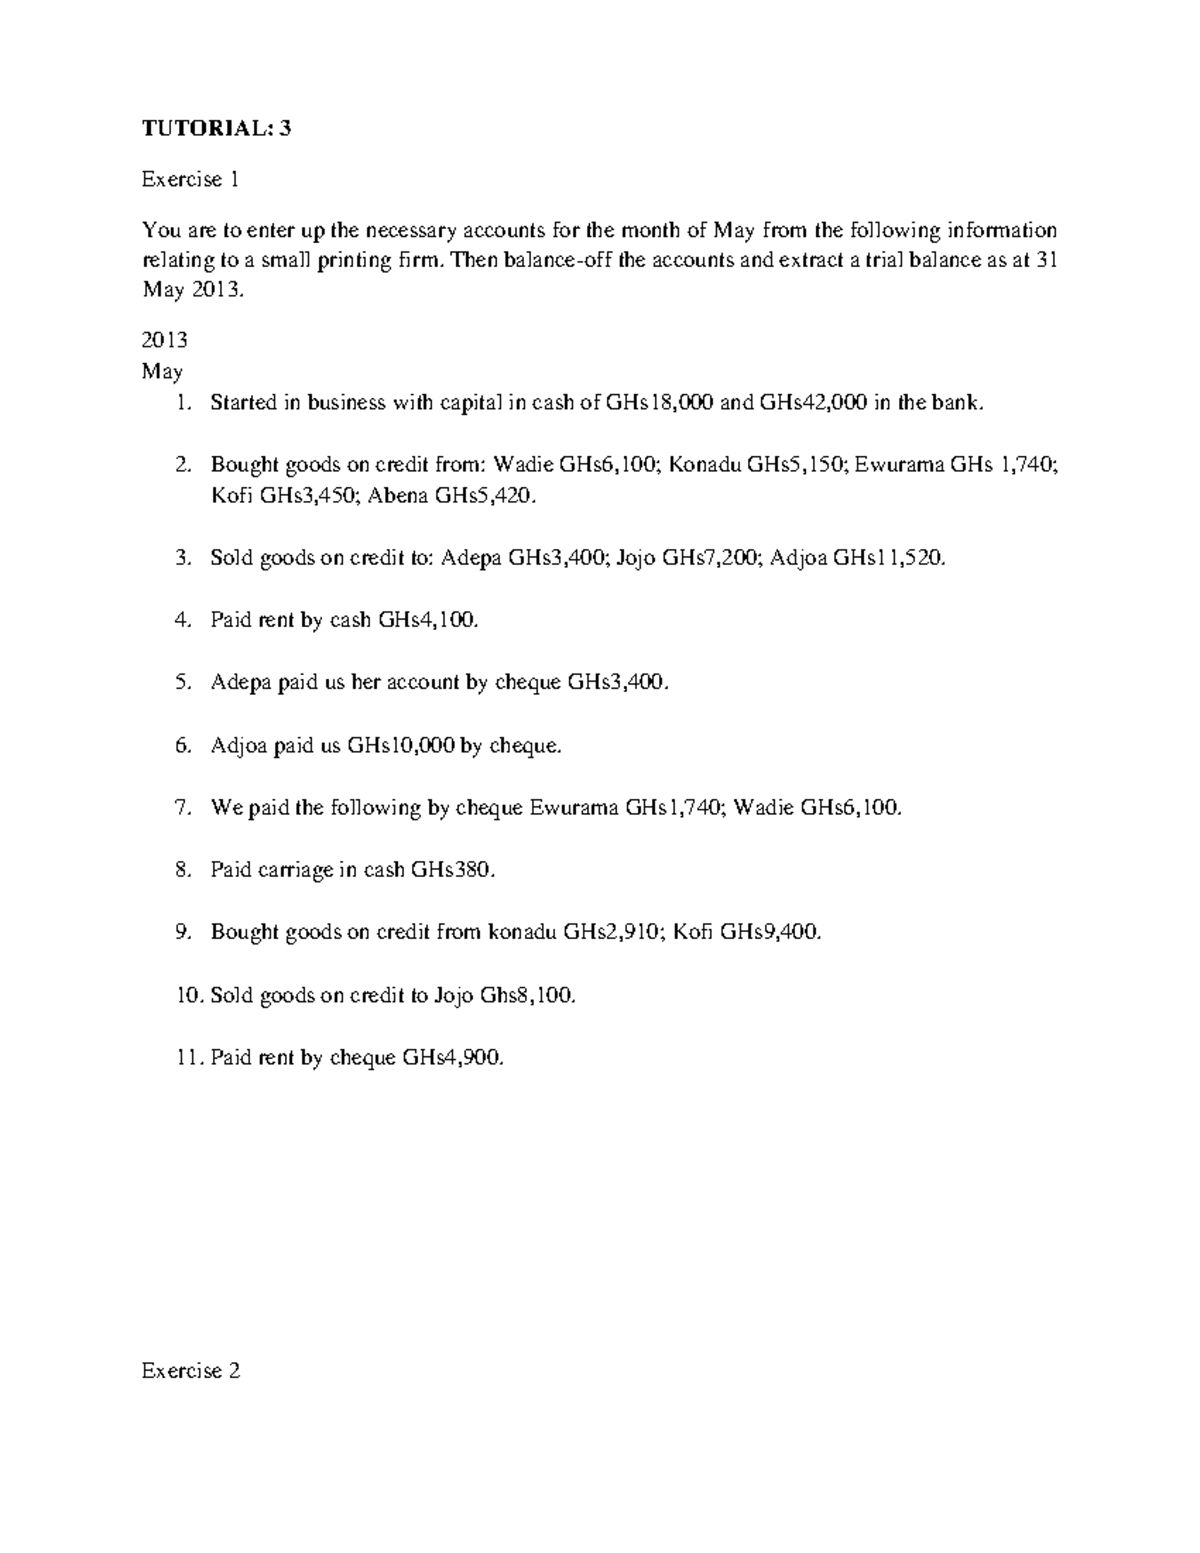
Most people begin studying accounting with financial accounting principles, which is fine if your goal is corporate reporting or public accounting. But if you're trying to get practical fast, start with bookkeeping fundamentals and work backward into the theory. Understanding how a journal entry flows from source document to general ledger to trial balance gives you a concrete mental model before you ever touch accruals or revenue recognition standards. The theory is easier to absorb when you can visualize the path a transaction takes through the system. I recommend using a combination of free resources and one paid course. YouTube channels like AccountingStuff and Farhat's Accounting Lectures cover the conceptual side well. For the hands-on portion, grab a QuickBooks Online or Xero trial, create a dummy business with ten transactions, and walk through the full cycle: set up chart of accounts, enter opening balances, record sales and purchases, run a P&L, adjust for depreciation, and close the period. Do it twice. The second time you'll understand why each step exists. The biggest gap in most introductory materials is how they treat tax. In 2026, the IRS and most international tax authorities have moved toward real-time or near-real-time reporting. The US has been piloting 1099-int integration with financial institutions, meaning interest income often gets reported before the taxpayer even knows it exists. Europe's ATAD 2 directive and the DAC7 regulation have created similar expectations for digital platforms. A proper tutorial for accounting 2026 needs to address compliance reporting as a core skill, not an afterthought. If you're learning in the US context, spend time understanding the difference between cash and accrual basis not just theoretically but in terms of how it affects your quarterly estimated tax payments and whether you qualify for the small taxpayer exception under the simplified method for home office deductions.
Here's something most beginners miss: the trial balance balancing does not mean the books are correct. A trial balance only checks that debits equal credits. It will not catch a transaction posted to the wrong account, a duplicate entry, or a revenue recognition violation. I learned this when reviewing a client's books where the Accounts Receivable subledger was $14,000 out of sync with the GL control account. The trial balance was perfect. The discrepancy came from a manual journal entry that debited AR but credited a clearing account instead of Unbilled Revenue, which cascaded into a revenue misstatement that wasn't visible until the subledger reconciliation. Always reconcile subaccounts. Always. Another counter-intuitive point: spreadsheet skills matter more than most accounting curricula admit. Excel remains the universal language of finance, and in 2026, Power Query and dynamic arrays have made it even more powerful for financial analysis. Learn to build a pivot table that pulls from a live bank feed export, create a VLOOKUP or XLOOKUP mapping between GL codes and department codes, and use Data Validation to prevent entry errors in recurring templates. These are practical skills that will save you hours every week. When it comes to software, the market has consolidated around three major platforms: QuickBooks Online for small to mid-size businesses, Xero for its clean interface and strong third-party integrations, and Sage Business Cloud for users who need more industry-specific features. There are also emerging tools like Bill.com for AP/AR automation and Pilot for accounting done-for-you services. None of these replace the need to understand what's happening underneath the buttons. I once had a client who used an automated expense tool that classified every restaurant receipt as "Meals and Entertainment" even when the meeting was with a vendor, not a client. The tax implication was significant because Meals and Entertainment has different deductibility rules depending on the current tax code provisions. The software couldn't distinguish between those categories without manual overrides. The fix was to create a custom expense class with specific sub-account mappings and train the staff on when to use each one.
Get the Full Details
If you're studying for a certification, the CPA exam underwent structural changes that took effect in 2026, introducing a new core section and modifying the discipline options. The REG section now places heavier emphasis on business valuation and intangible assets, areas that have grown in relevance with the rise of digital economy taxation. The FAR section has been updated to reflect ASU 2023-06 and subsequent lease accounting and revenue recognition updates. Make sure your study materials are dated 2026 or later. Older materials will miss these changes and could cost you points on the exam. For practical bookkeeping, here is the minimum workflow that covers most scenarios: each business day, pull bank and credit card feeds, match transactions to open bills or invoices, review unmatched items for manual categorization, run a weekly profit and loss and balance sheet review, and reconcile every account at least monthly. The reconciliation step is non-negotiable. A monthly bank reconciliation takes about 15 minutes for a small business with moderate transaction volume and catches errors before they compound. Skipping it is how mistakes become problems. The one area where most free tutorials fall short is month-end close procedures. Learning to close a month efficiently involves knowing the order of operations: accrual entries first, then depreciation, then intercompany eliminations if applicable, followed by subledger reconciliations, and finally the close checklist sign-off. Some companies use a soft close where they lock the period but allow reversal entries during a window, while others do hard closes with no reopening permitted. Understanding both approaches and when to use each is a practical skill that separates someone who can do accounting from someone who can produce reliable financial statements on schedule.
For downloading resources, the AICPA's accounting standards transition resource library offers free access to implementation guides, and the FASB Accounting Standards Update database provides the current text of all pronouncements. The IRS website has a small business tax kit that covers the most common filing requirements. Avoid downloading accounting textbooks from unofficial sources, as edition dates matter significantly in this field and outdated material can introduce errors in your understanding. If you're starting from zero and need a structured path, enroll in a community college accounting course for the foundational knowledge, supplement it with a QuickBooks or Xero certification program for the software proficiency, and maintain a side project where you apply what you're learning to a real or simulated business. The side project is the most important part. Theory without application sticks poorly, and the exceptions and edge cases that actually matter in practice only become clear when you encounter them yourself.