Setting Up an Accounting System That Actually Works
Most people who ask about basic accounting end up drowning in spreadsheets within three months. They start with good intentions, track every receipt they can find, and then abandon the whole thing because it becomes too cumbersome to maintain. What I am going to walk you through is a stripped-down method that keeps things functional without demanding your full attention every single day. Start with just three categories: income, cost of goods, and operating expenses. Do not overthink the chart of accounts. The temptation to create detailed subcategories like "office supplies miscellaneous" or "client entertainment" sounds organized but ends up being a trap. You will spend more time filing transactions than doing actual work. Keep it boring and broad for the first year at least. Here is the part most beginners skip. Set up a separate bank account exclusively for business transactions. Not a separate sub-account. A real checking account at a bank or credit union. I learned this the hard way in 2019 when I was reconciling a combined personal and business account for a client who ran a freelance design shop. We spent six hours untangling grocery purchases from equipment buys because everything fed through the same account. The reconciliation took a full afternoon that could have been twenty minutes. Open a business account on day one. Even if it is just a basic online checking account with no monthly fee.
Automate bank feeds immediately. Every system you will look at offers some version of automatic transaction importing. Plaid, Yodlee, direct bank APIs. Connect your business account and your primary credit card. This eliminates manual data entry for roughly eighty percent of your transactions. The remaining twenty percent are cash expenses and miscellaneous items that still need to be logged, but they are far fewer than you would handle otherwise. Reconcile monthly. Not weekly unless you are processing high volume. Not annually because then you are dealing with twelve months of confused memory and missing receipts. Pick the same day each month, sit down for maybe twenty minutes, and match your bank statement line by line against your recorded transactions. If something does not match, investigate it right then instead of pushing it into a pile called "later." Later never comes. I once had a client who deferred reconciliation for eight months and found a duplicate vendor payment of forty-two hundred dollars buried in there. He recovered it, but it required a phone call to the vendor and a written demand letter. Reconciliation takes twenty minutes a month. The alternative takes weeks. For the actual software choice, I usually point people toward either Wave, GnuCash, or the basic tier of QuickBooks depending on their situation. Wave works well if you are truly solo and need invoicing plus basic expense tracking with zero monthly cost. GnuCash is free desktop software with double-entry accounting built in. It looks outdated and the interface is not friendly to newcomers, but it does not lock you into a subscription and it handles everything a small operation needs. QuickBooks at the cheapest tier is the path most people eventually take because it scales reasonably well and integrates with payroll and merchant services. Pick one and stick with it. Switching mid-year causes more headaches than people expect.
Receipt management is where systems normally fail. The workflow is straightforward: photograph every receipt the moment a purchase happens, save it to a folder labeled by month, and attach it to the corresponding transaction in your accounting software. Use an app like Shoeboxed or Dext if you want automated parsing, but those cost money and introduce another subscription. A phone camera and a simple folder structure in Google Drive or Dropbox works fine. I have done it this way for over a decade. The one edge case that trips people up is digital payments through PayPal, Stripe, or Venmo business accounts. These platforms send periodic settlement deposits that combine multiple customer payments into one bank entry. Your accounting software will see one deposit but you have ten sales to record. The workaround is to use the "batch deposit" or "settlement report" feature inside each platform, pull the report, and reconcile as a batch in your system instead of trying to match individual transactions manually. Invoicing should happen the same day the work is done. Delayed invoicing is the single biggest reason small businesses have cash flow problems. You finish a project, you feel good about it, you do not send the invoice until two weeks later because you assume you will get to it. You do not. Put it in your calendar as a rule: invoice upon completion. If you charge hourly, track time in real time using whatever timer you prefer and submit the invoice with the timesheet attached. If you charge a flat rate, send the invoice immediately upon delivery of the final product or service. Here is something most beginner guides will not tell you. The profit and loss statement you generate at the end of the year is less useful than the month-over-month comparison. A single annual P&L hides everything. Did your costs spike in March because of a one-time purchase or a recurring problem? Was June actually profitable or did you eat into the profits from April? Run a monthly comparison report every quarter. It takes five minutes and it catches trends that would otherwise surprise you.
Get the Full Details
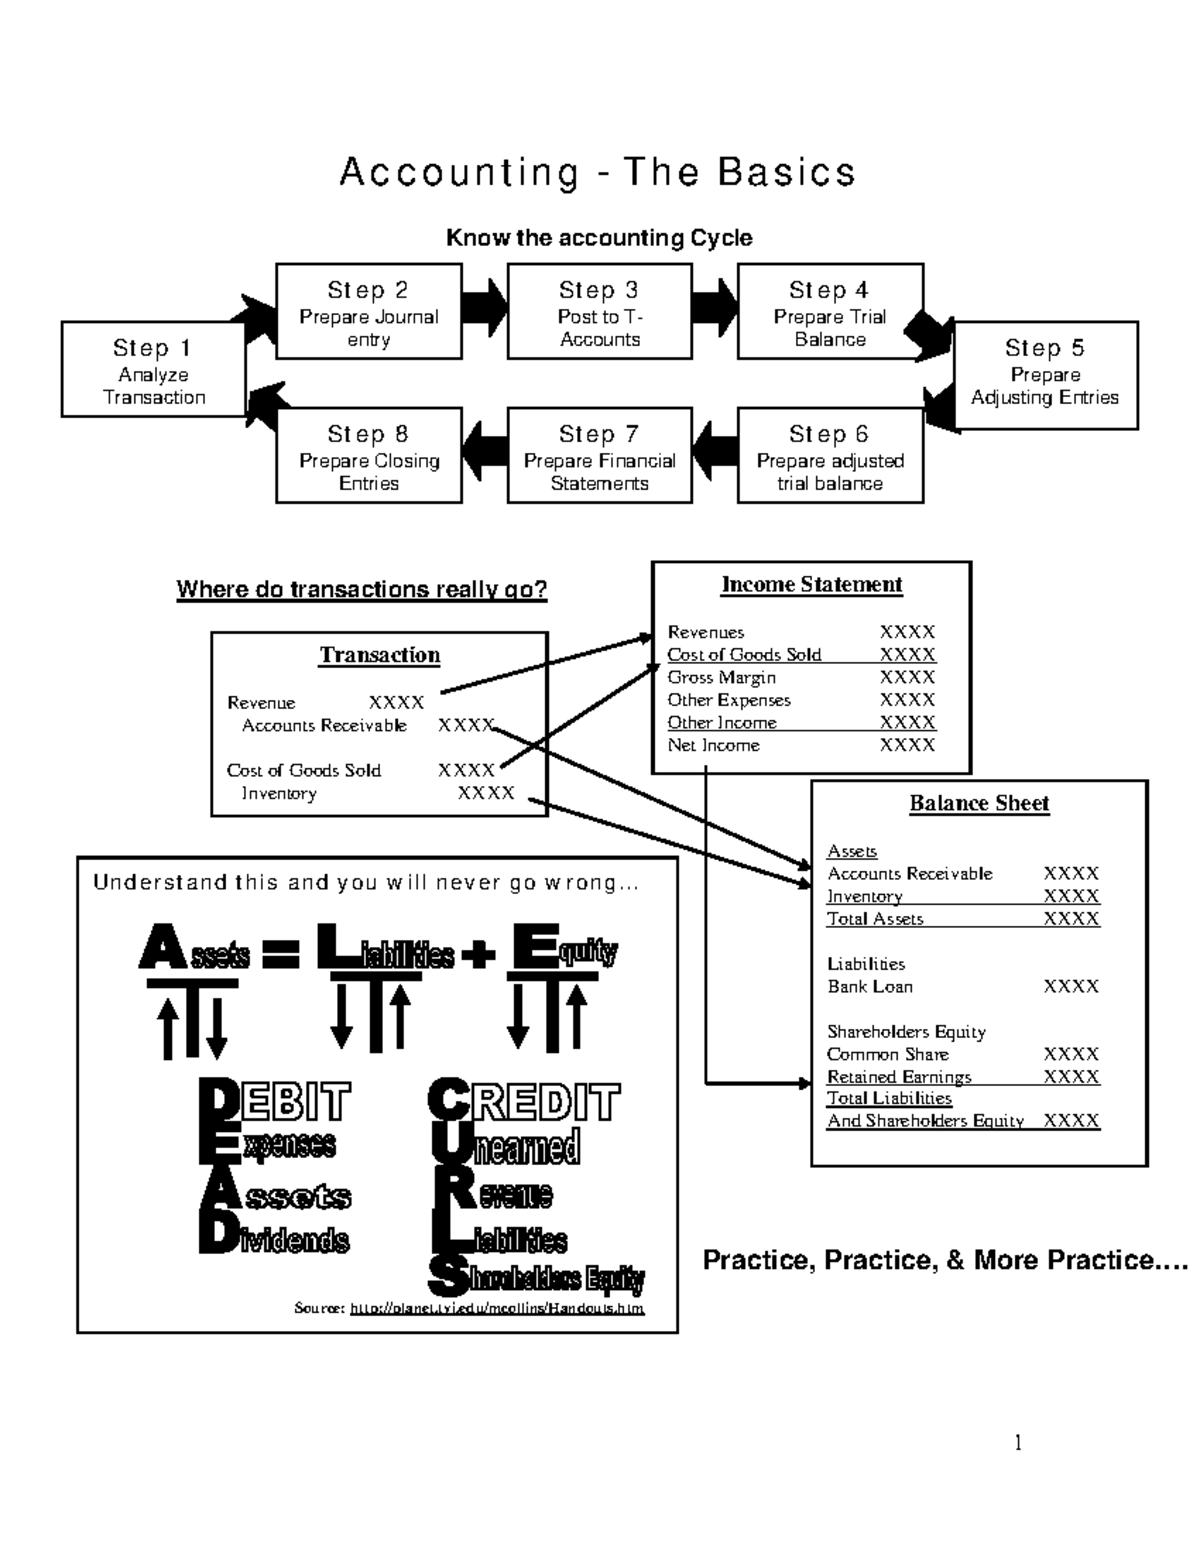
Another counter-intuitive point: prepayable expenses should not all be expensed immediately if the amount is significant. If you pay six months of insurance upfront for three thousand dollars, recording that as a three thousand dollar expense in one month will make that month look terrible and the following five months look artificially profitable. Set up a prepaid expense asset account and amortize it across the coverage period. Most simple accounting systems support this. It is one additional step during setup but it prevents your financial reports from looking misleading. The system above is not perfect. It assumes you are a sole proprietor or a small partnership with straightforward income. If you hold inventory, manage employees, or operate in a regulated industry, this simplified approach will fall apart quickly. Inventory tracking alone requires perpetual counting systems and cost of goods sold calculations that the basic tools I mentioned handle poorly. In those cases, you need something like QuickBooks Advanced or a specialized platform. But if you are a freelancer, consultant, or small service business, this method keeps you compliant and gives you readable financials without becoming a part-time job. Download links for the software I referenced are available directly from their official websites. Wave at waveapps.com, GnuCash at gnucash.org, and QuickBooks at quickbooks.intuit.com. Avoid third-party resellers or download mirrors. Accounting software touches your financial data directly and downloading from unofficial sources is a real risk.
If you want to start today, the first three things to do are open a business bank account, install or sign up for one of the programs mentioned, and connect your bank feed. Everything else builds on top of that foundation. Do it in that order and you will save yourself several months of rework.


